GSR Weekly - Oct 26, 2026
Slater Santer
Research Analyst
Carlos Guzman
Research Analyst

Slater Santer
Research Analyst
Carlos Guzman
Research Analyst
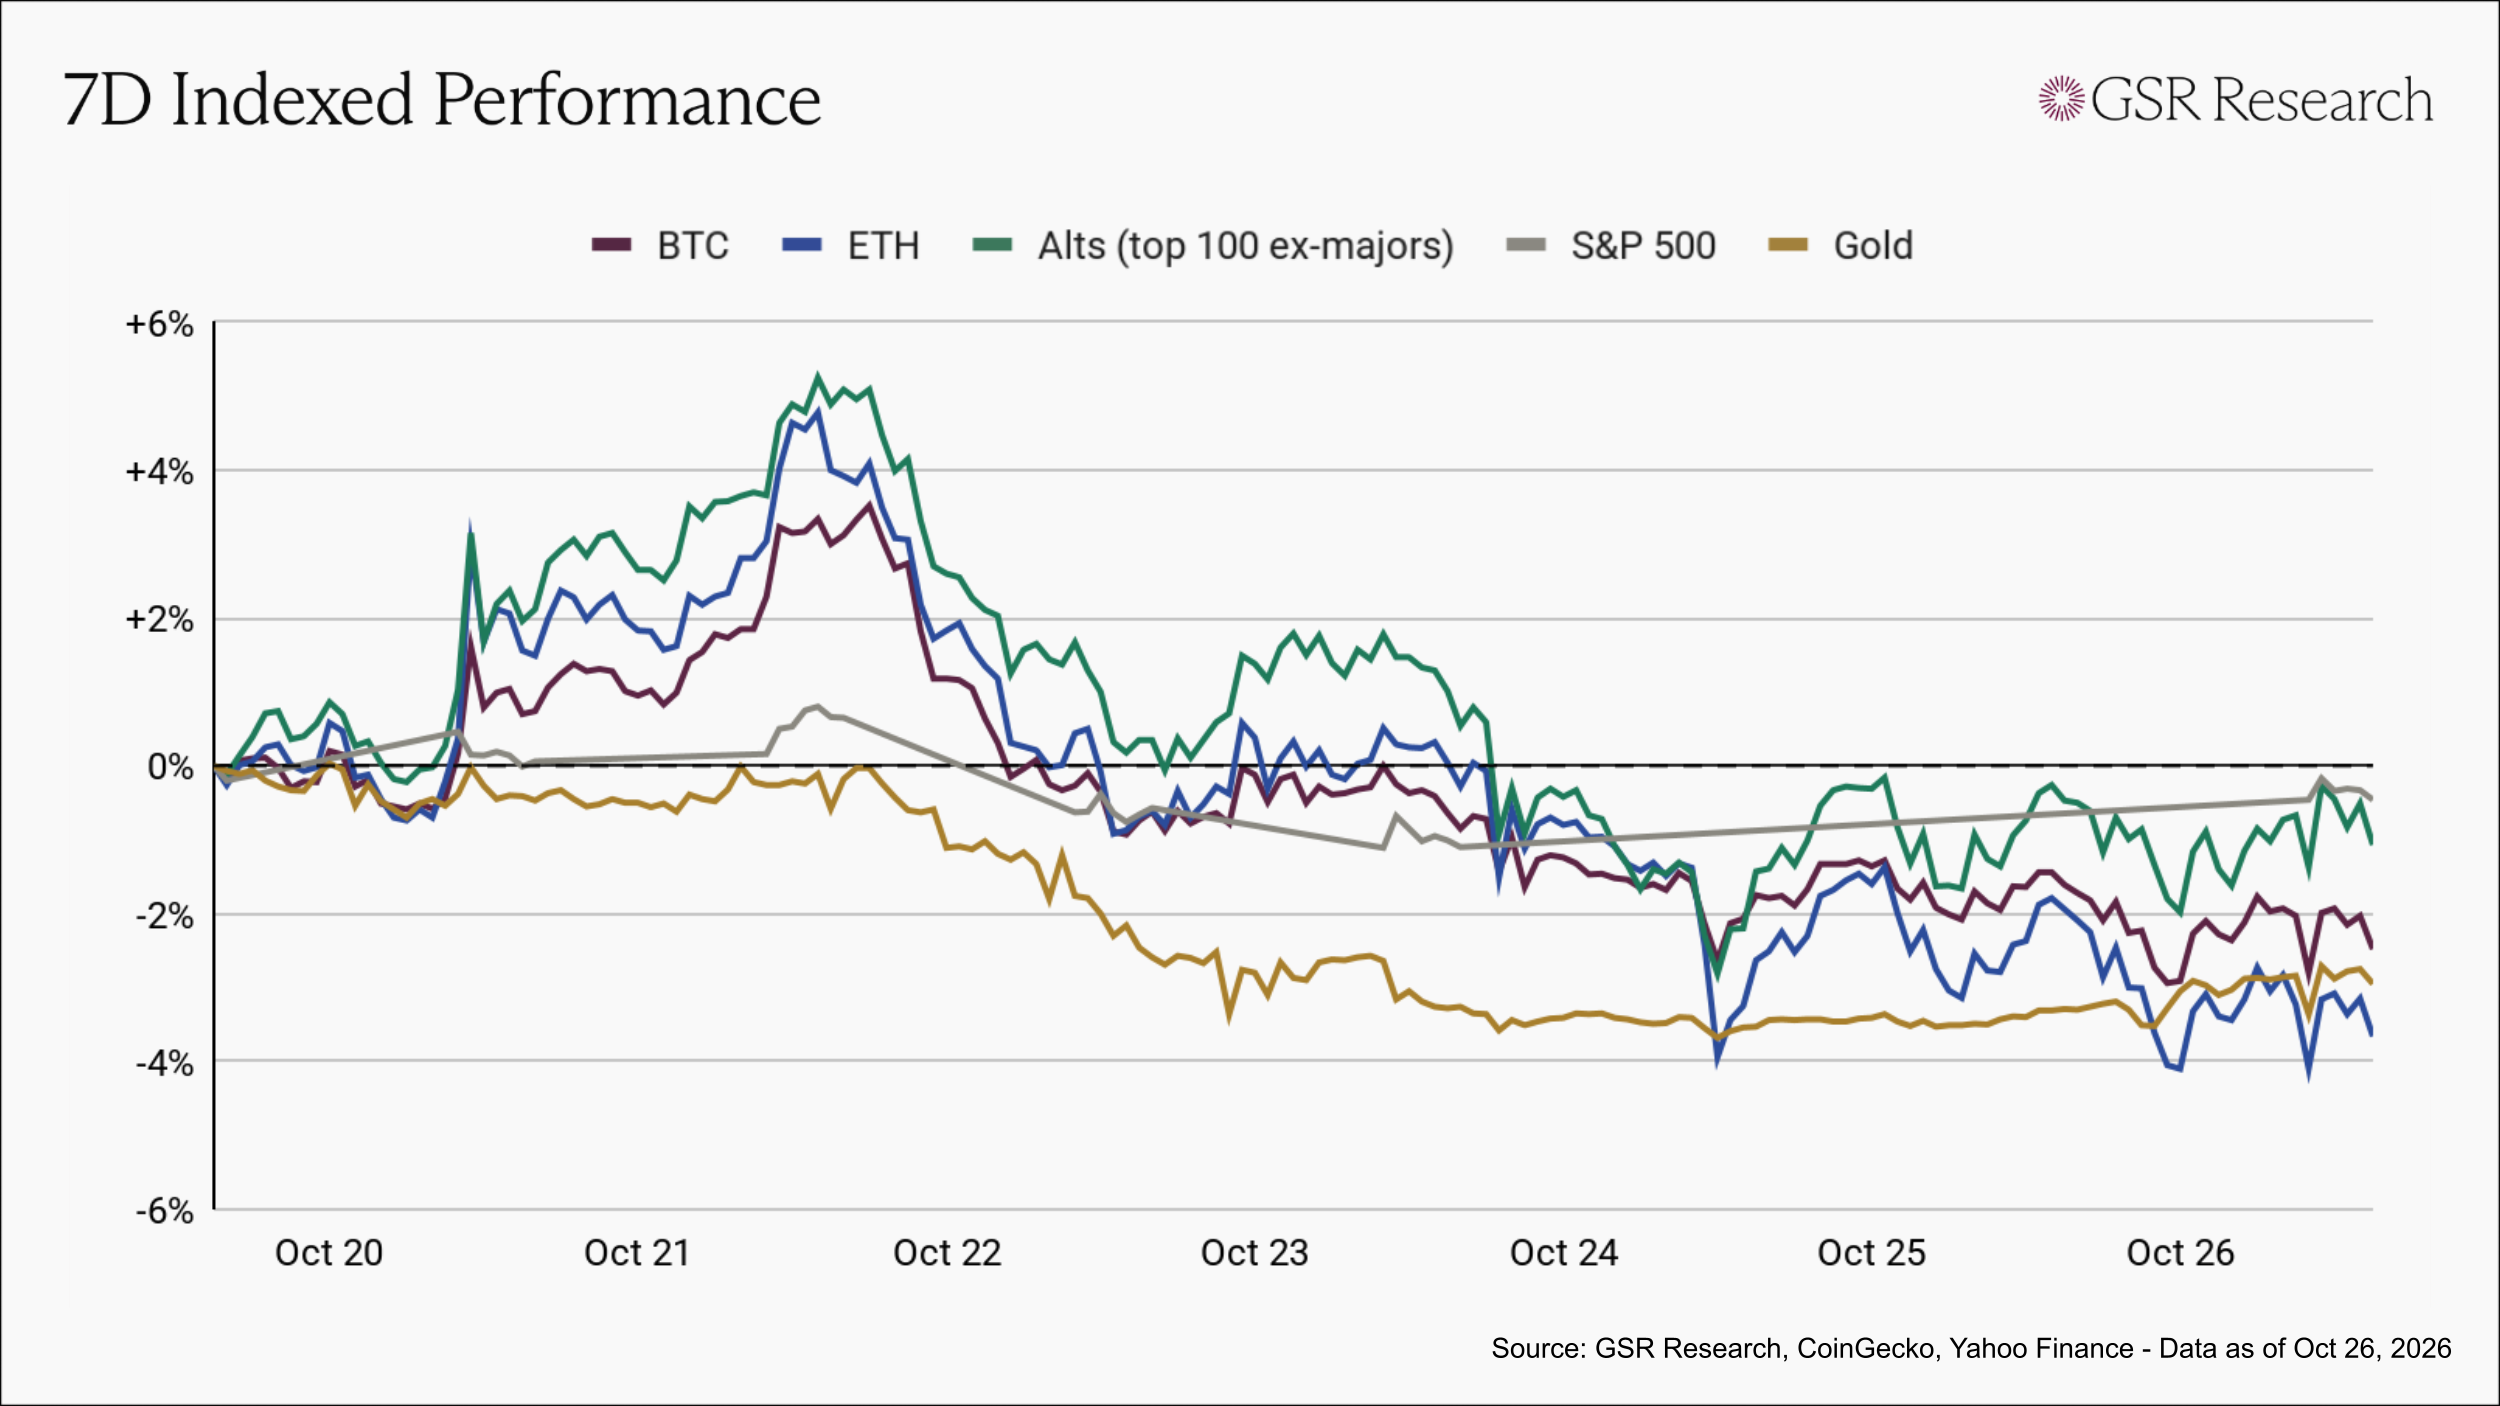
Spot Bitcoin ETFs opened the week with $526.7M of inflows on Monday, led by IBIT's $665.2M, its largest single-day intake since October 2025. BTC ETFs would go on to add another $548.0M across Tuesday and Wednesday for a three-session total of $1.07B. BTC climbed to a weekly high of $84,778 on Wednesday, even as Brent pushed above $111 on Tuesday due to renewed attacks in Saudi Arabia and against shipping in the Strait of Hormuz.
However, sentiment shifted midweek after Meta reported their earnings following Wednesday's close, narrowing its 2026 capex range to $135-145B from $130-145B, with free cash flow turning negative at -$2.1B for the quarter. The stock lost 7% on Thursday, taking the Nasdaq to its largest daily decline since early June. Against that backdrop, spot Bitcoin ETFs shed $635.6M, erasing Wednesday's inflow, and BTC fell to roughly $80,790 before recovering above $81,000 overnight. Friday's flash PMIs showed selling prices rising at the fastest pace since August 2022, and Brent settled at $116.72, its highest close since April, after Houthi attacks across Saudi Arabia and a report that the U.S. and Israel have drawn up plans to resume strikes on Iran after the November 3 midterms. Spot Bitcoin ETFs lost another $137.9M on Friday, leaving the week at +$301.2M, while CME FedWatch odds of a hike at this week's FOMC fell to ~10% from ~15% a week earlier, with markets still leaning toward a December hike. BTC finished down ~3% at $80k, ETH ~4% lower, the alt basket down ~2%, gold ~3% lower, and the S&P 0.5% lower.
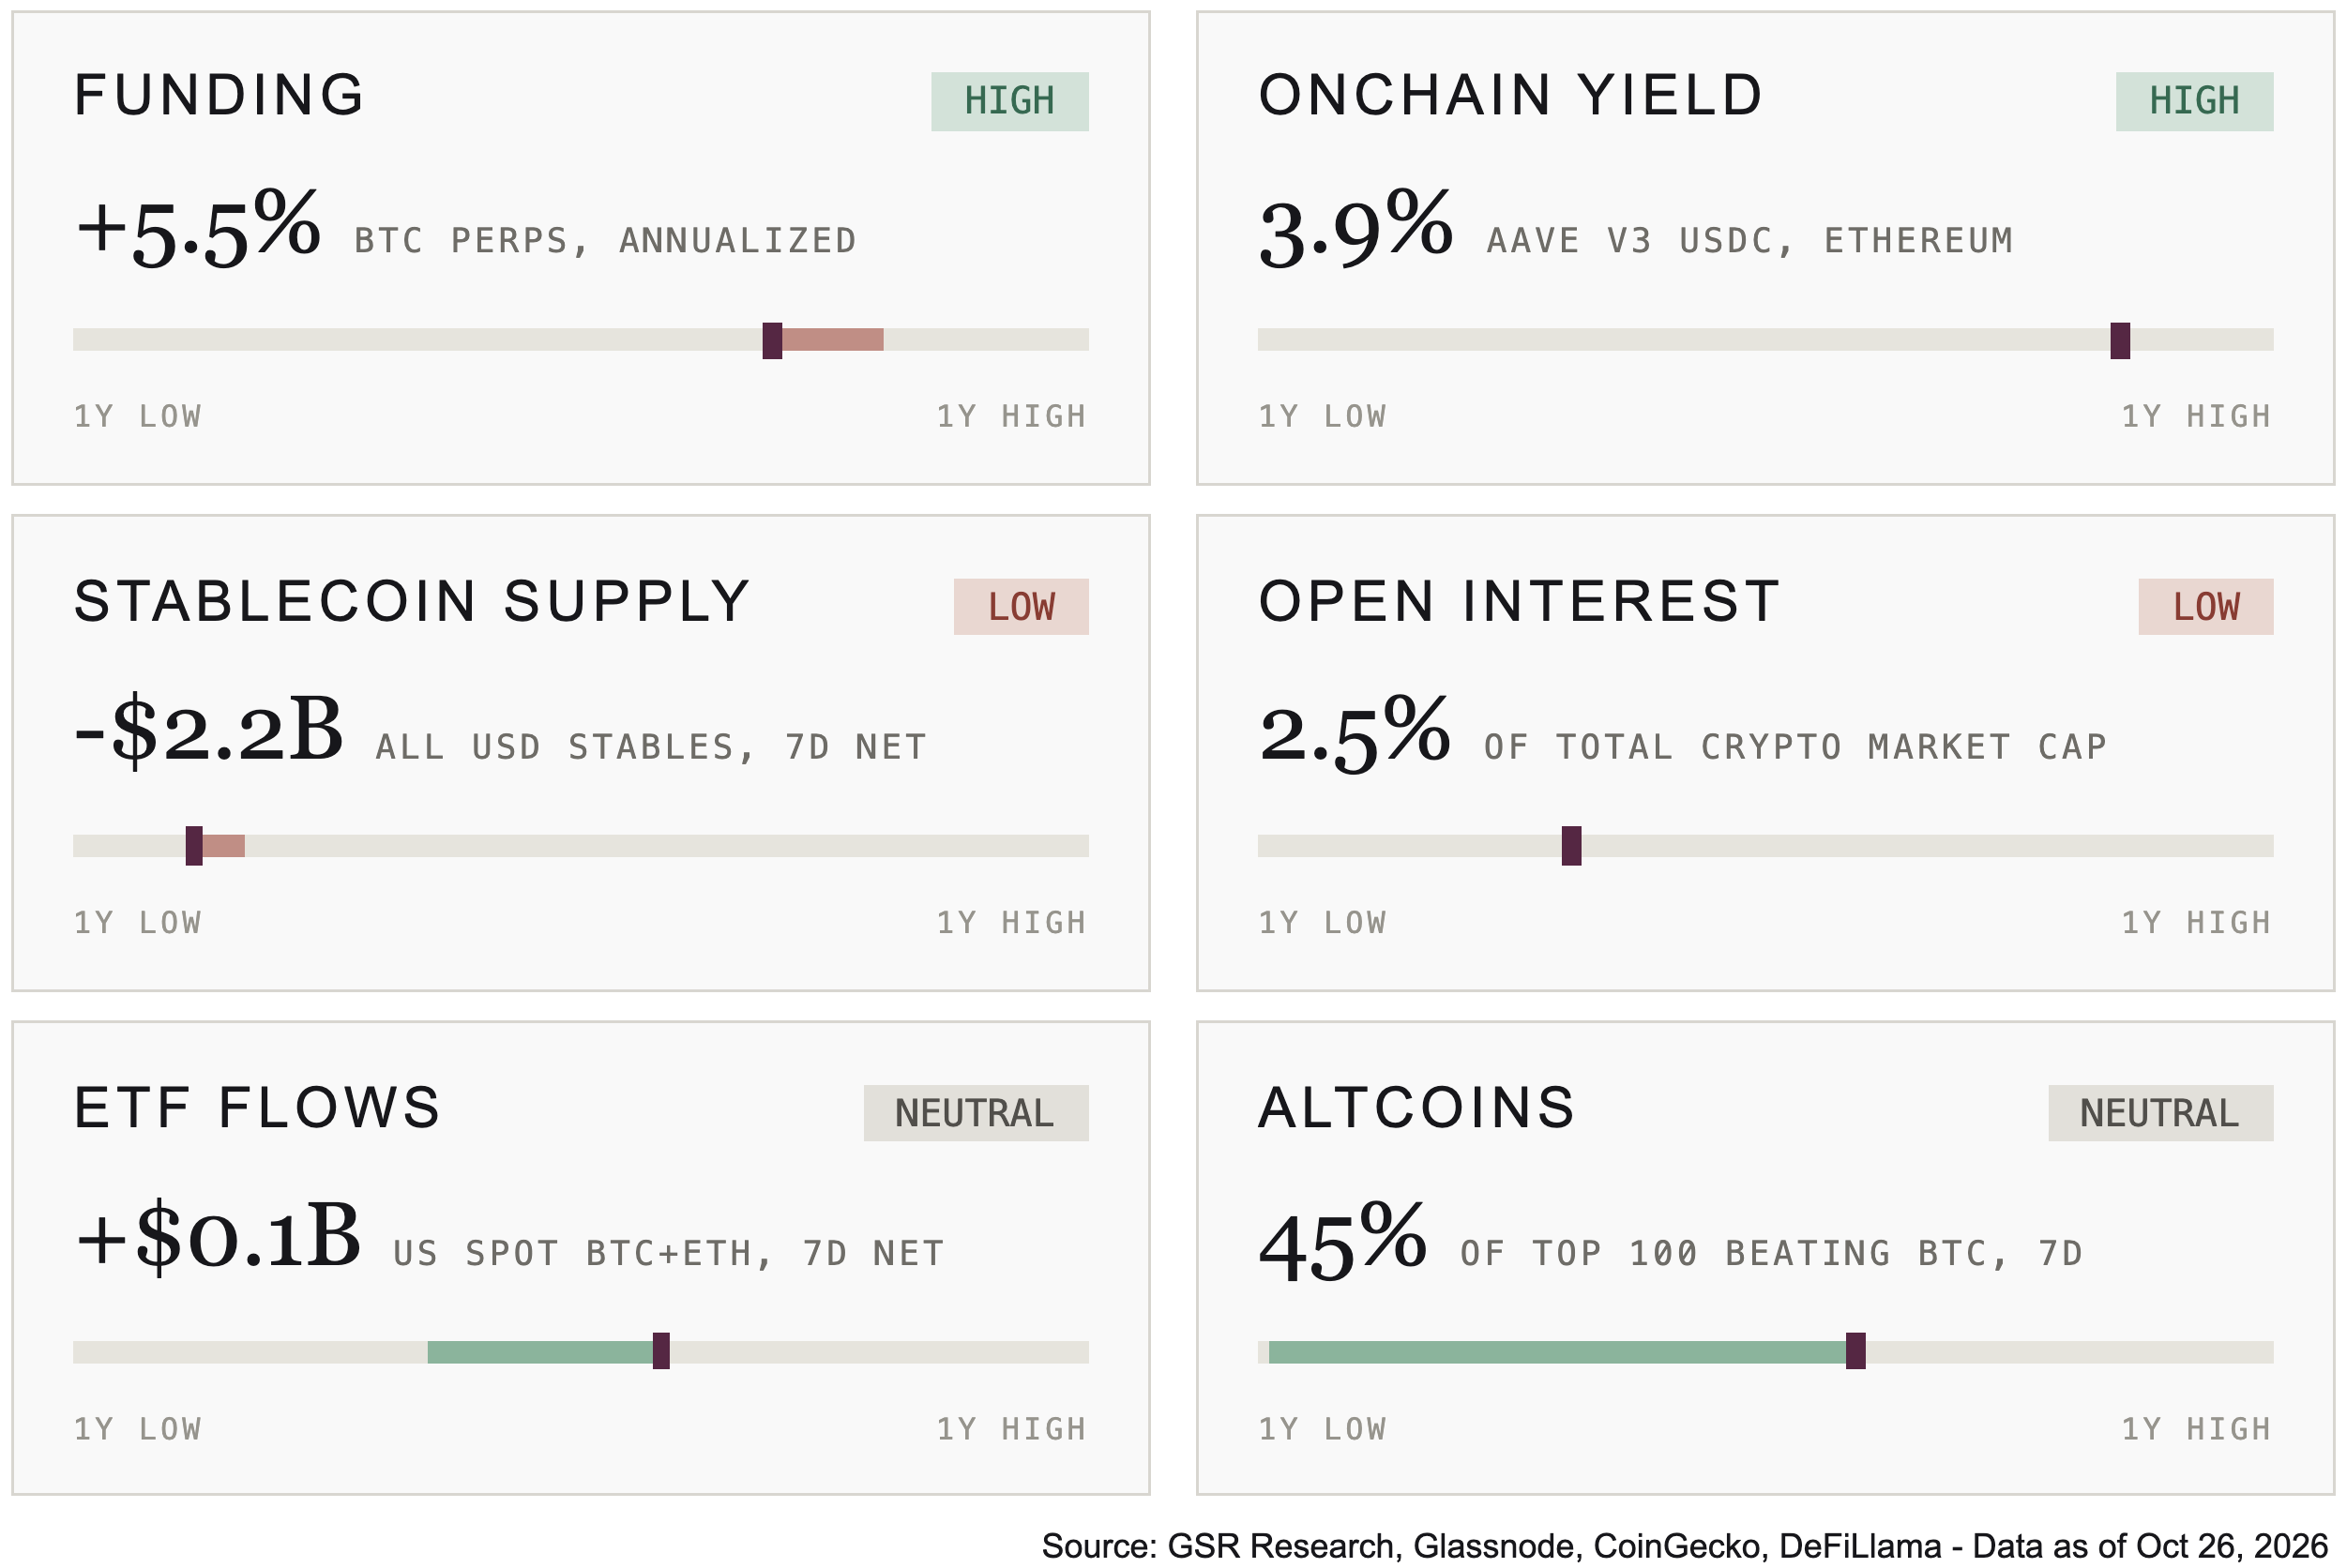
The market pulse gauges improved this week, with ETF flows and altcoin breadth both returning to the neutral range. ETF flows turned positive, rising from -$0.5B to +$0.1B after two negative weeks, and 45 of the top 100 altcoins beat Bitcoin, up from 16 the week prior. Funding and Stablecoin Supply change both declined, with funding easing from +6.5% to +5.5% annualized while staying in the high range, and Stablecoin Supply change falling further from -$1.7B to -$2.2B, a third straight week of net contraction. Onchain yield edged up from 3.8% to 3.9%.
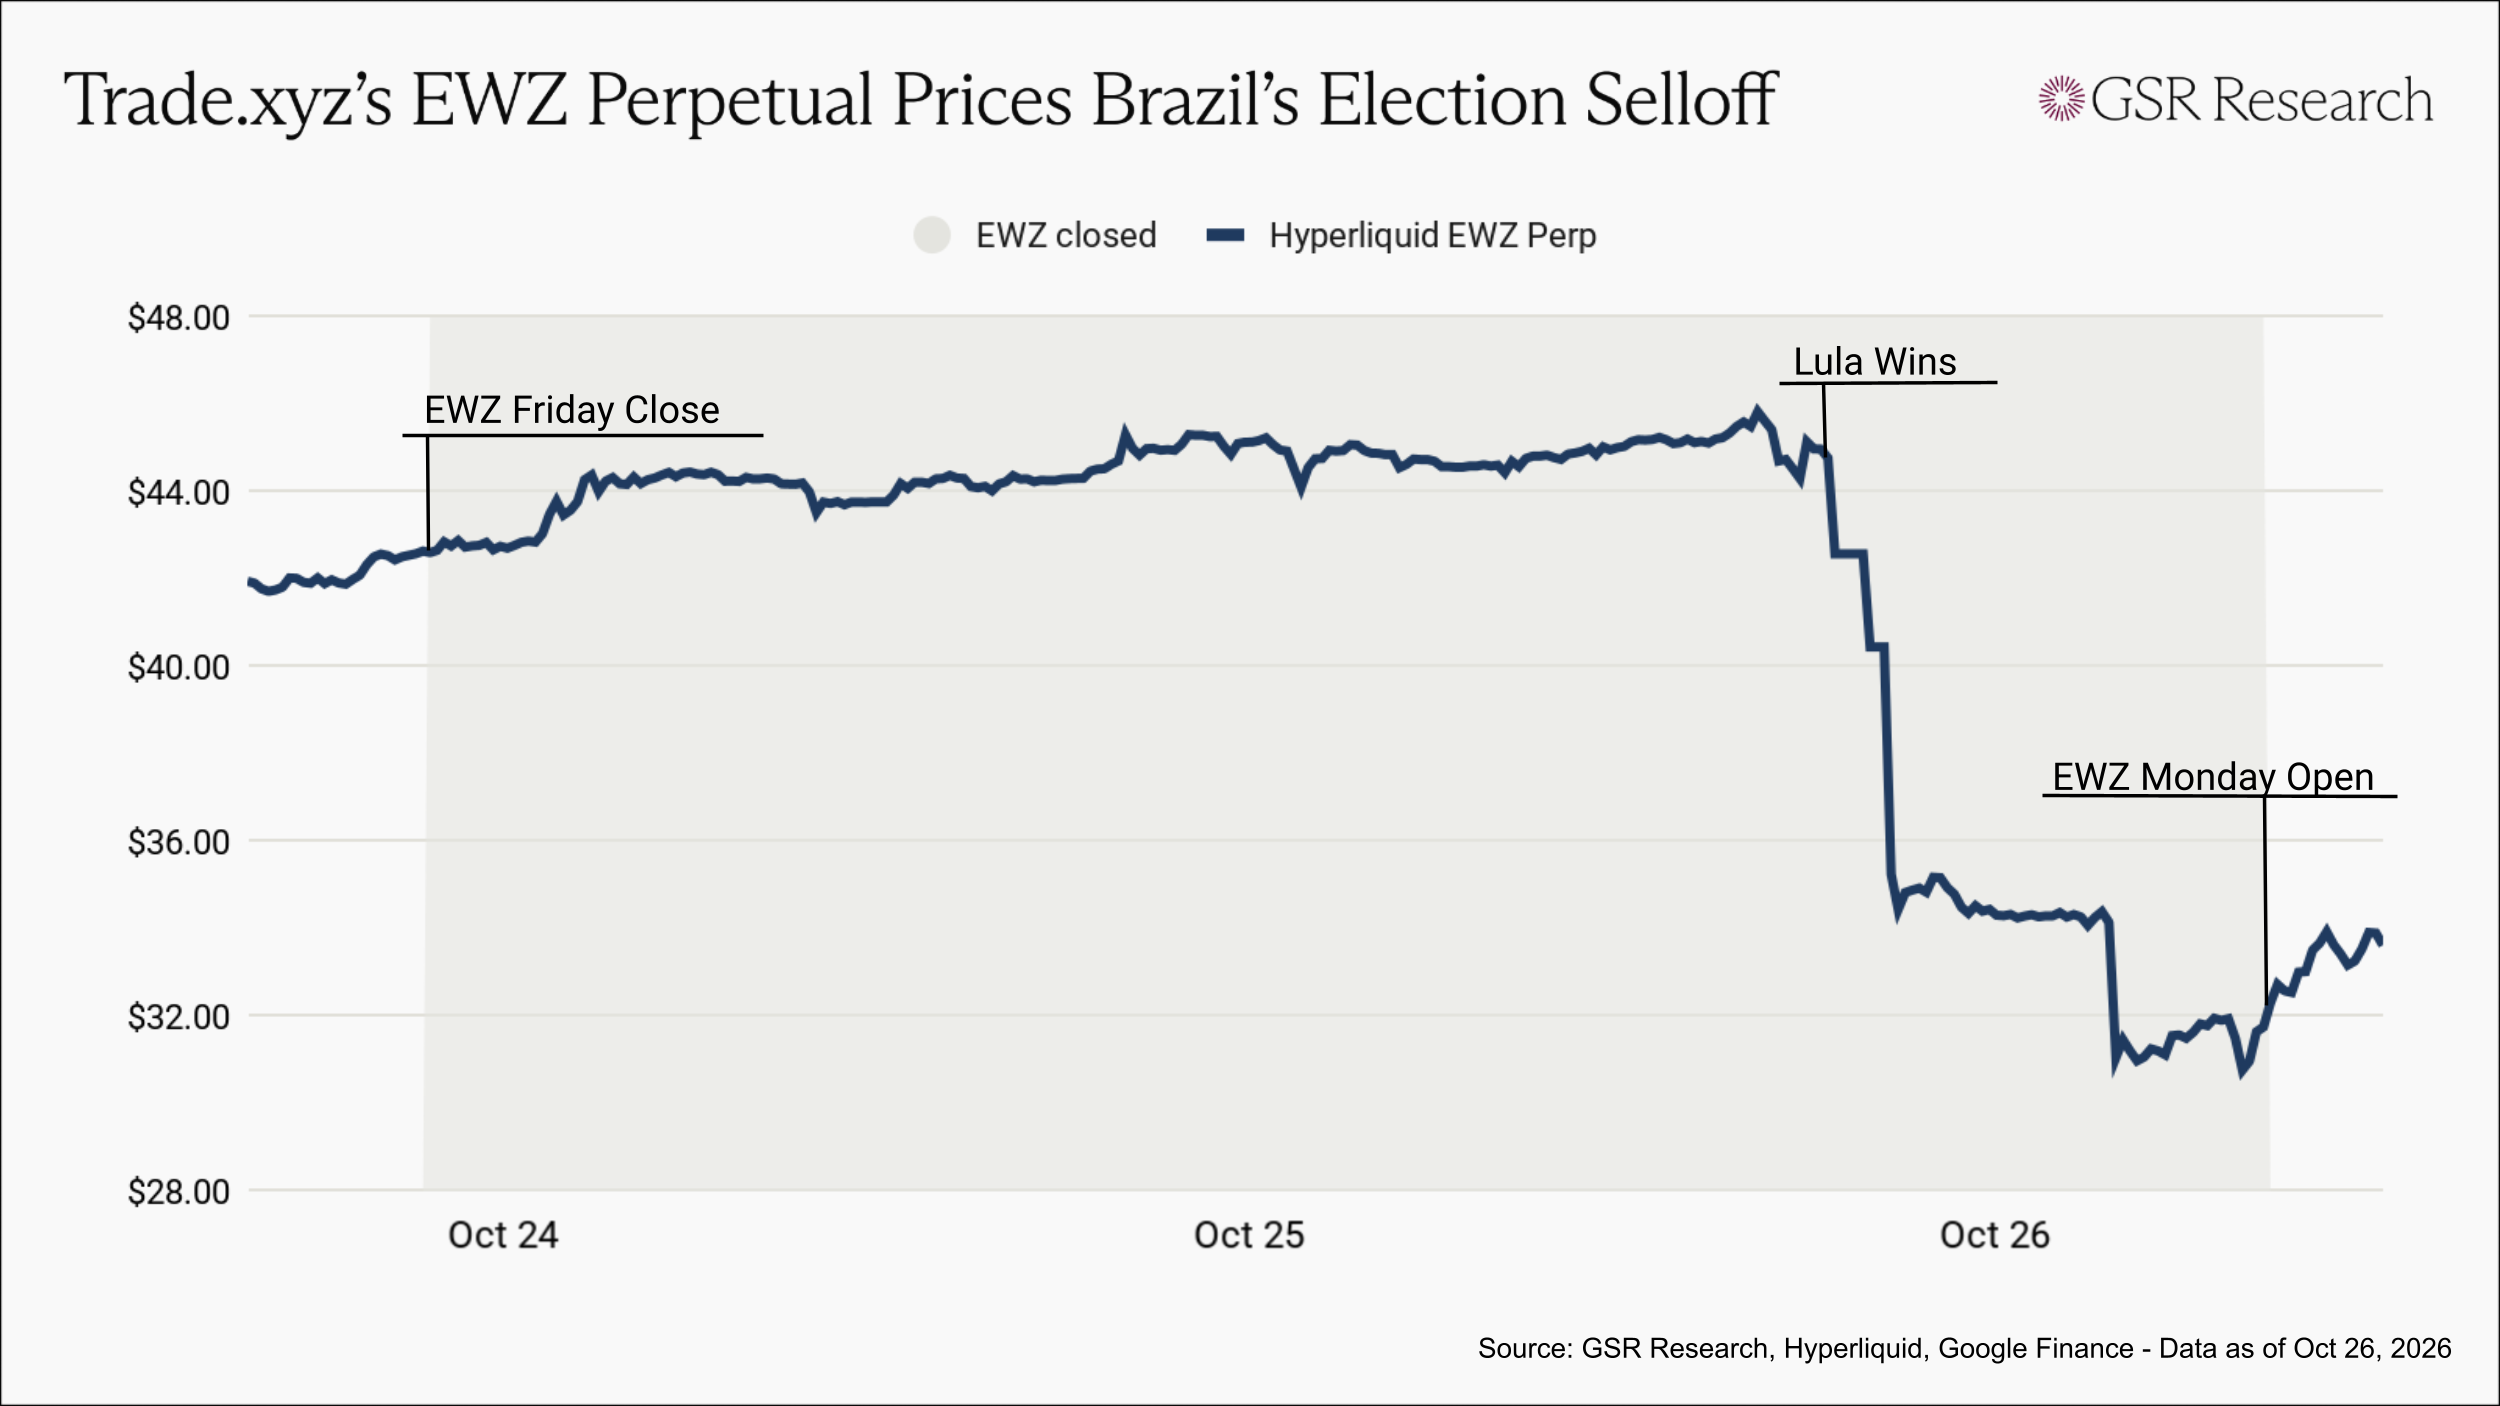
Brazil's presidential runoff was decided on Sunday, October 25, while U.S. and Brazilian stock exchanges were closed, leaving 24/7 venues to price the result before Monday’s regular session open. Lula won 51.79% to 48.21% after most polls had Flávio Bolsonaro narrowly ahead, and because investors had been primarily positioned for a Bolsonaro win, the market repriced heavily upon the news. Trade.xyz's EWZ perpetual on Hyperliquid traded nearly 8% above EWZ's $42.59 Friday close before the count, then fell into the low $30s overnight as the result became clear.
However, Hyperliquid was only one of several venues that priced the move. At 7:46 pm ET on Sunday, EWZ perpetuals on Binance and Bybit were already trading at $37.24 and $37.10, while trade.xyz's EWZ market on Hyperliquid held at $40.456. Blue Ocean's overnight session opened at 8 pm ET with EWZ trading between $34 and $35, and when trade.xyz's external pricing restarted at 8:05 pm ET, using Blue Ocean as its oracle during that session, its EWZ market dropped to $34.92. EWZ traded at $31.83 in Monday's premarket session, down 25.3% from Friday's close, and fell as much as 26% to $31.40 after the open, putting it on track for its worst day since its July 2000 launch.
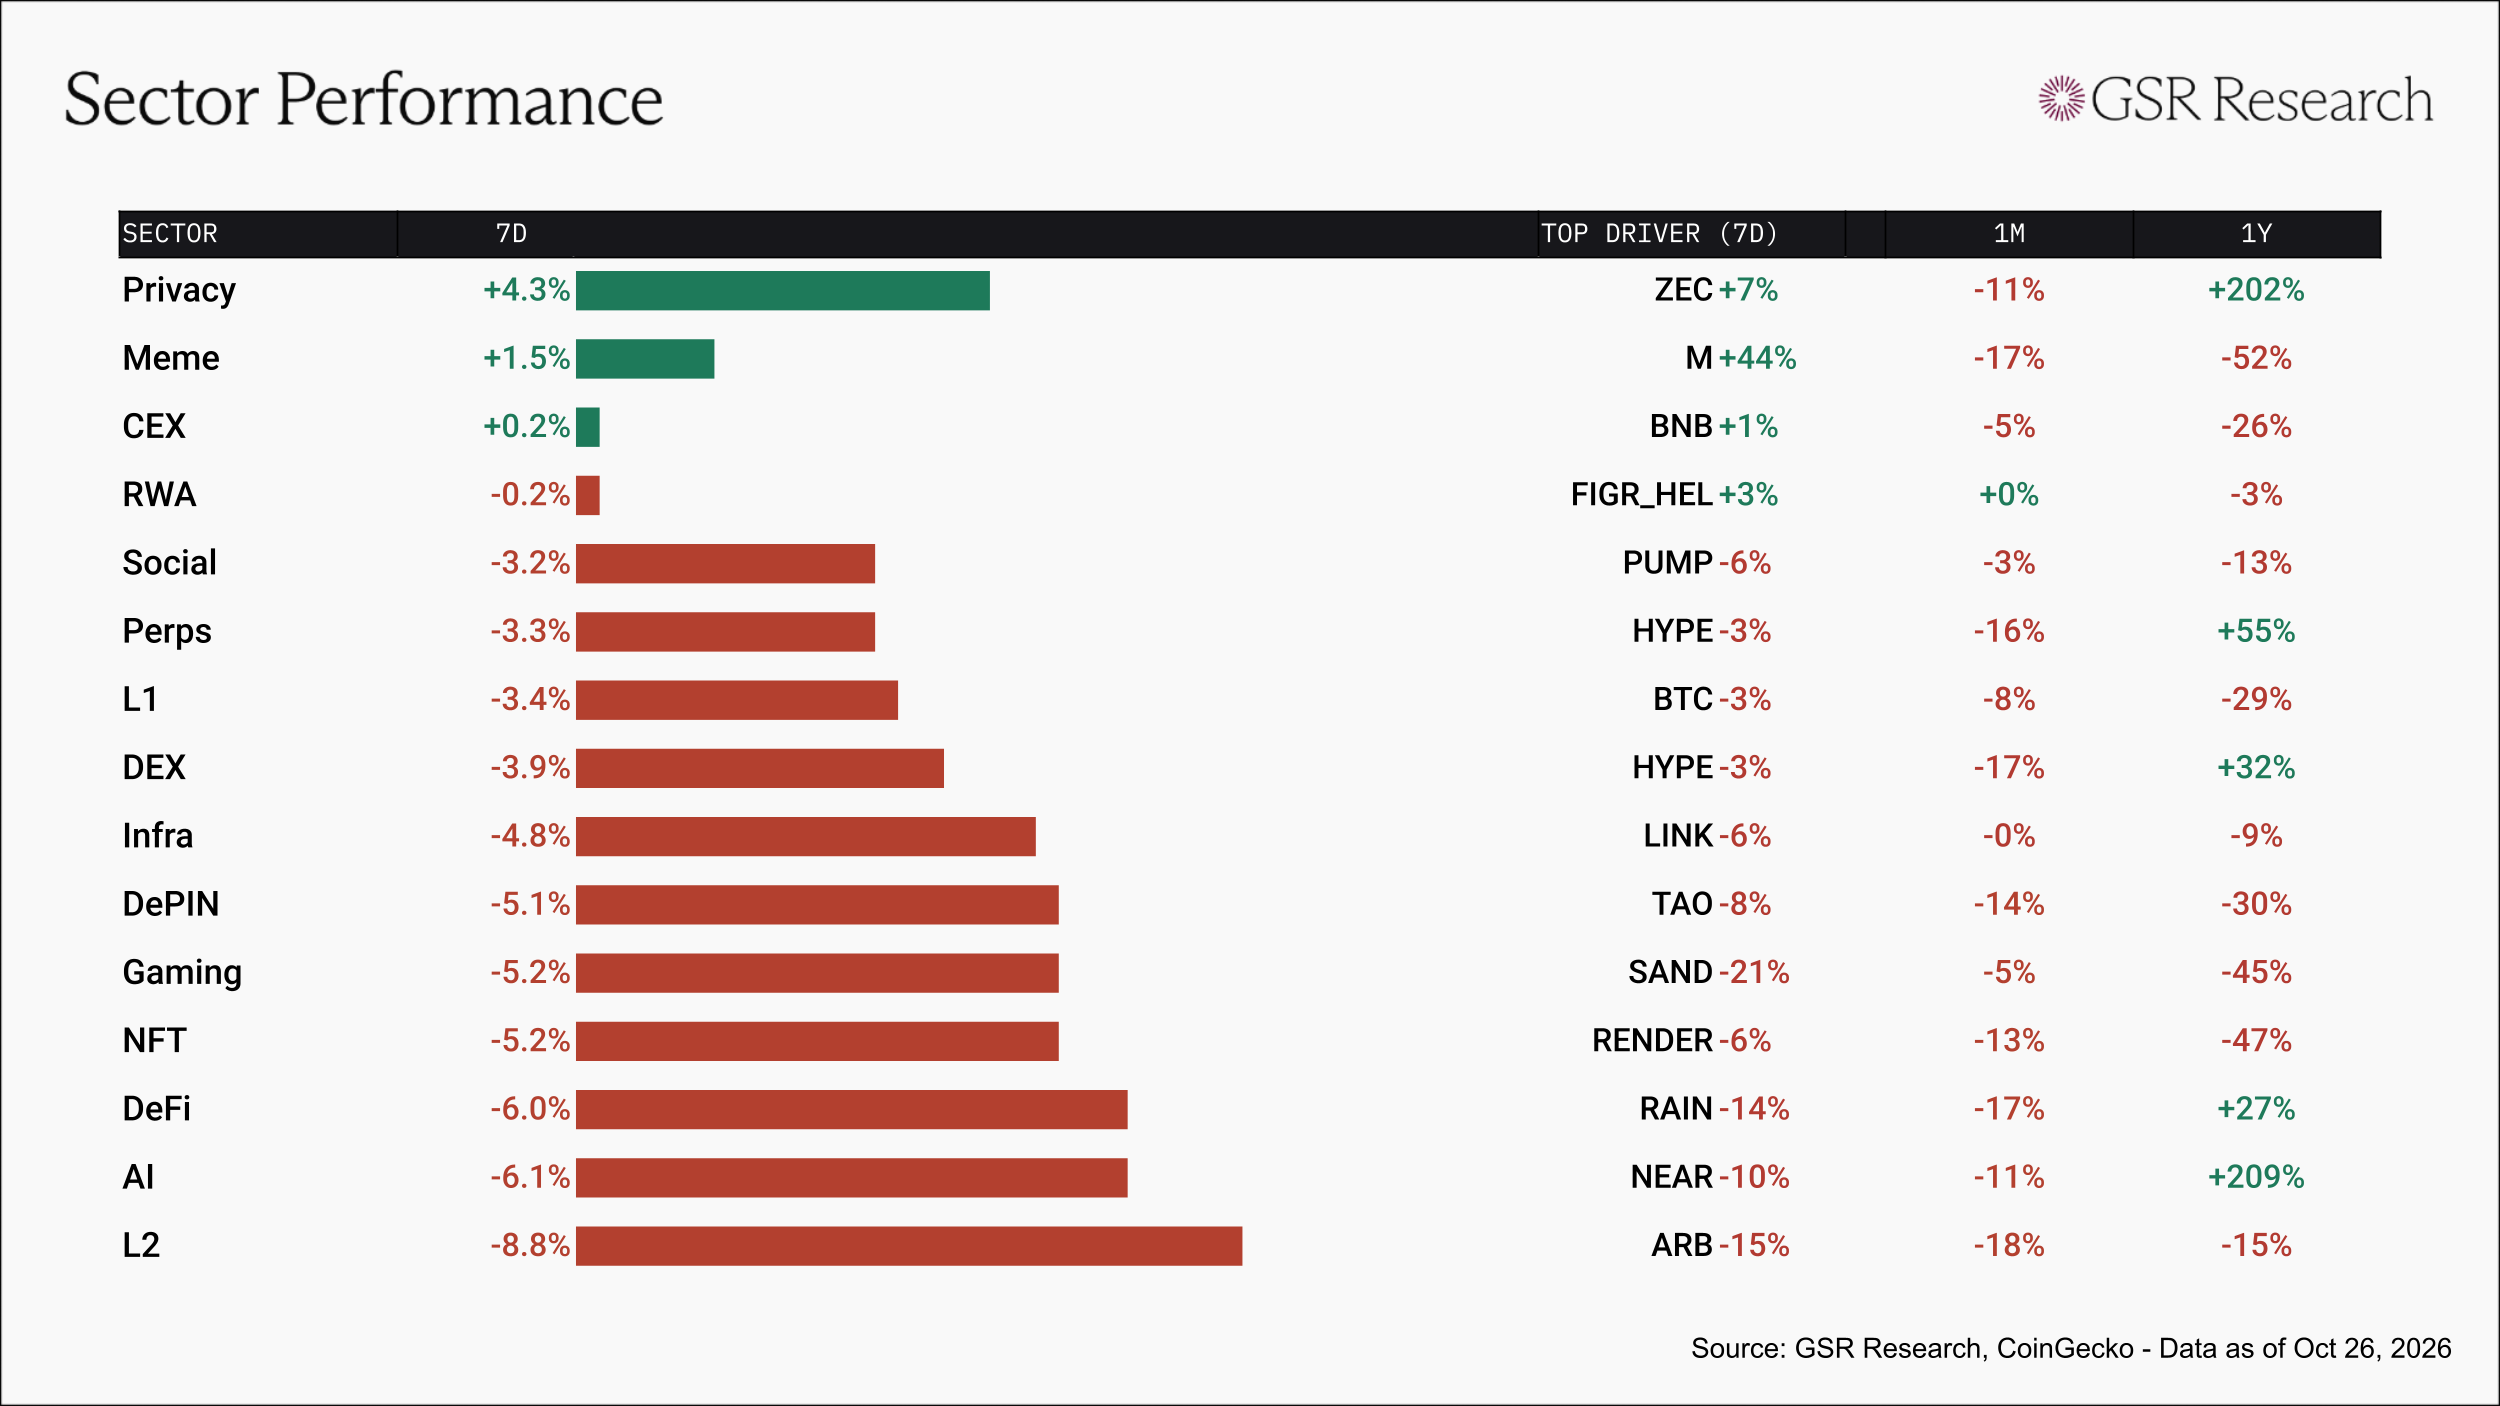
12 of 15 sectors closed red this week, as Privacy led at +4.3% on ZEC (+7%). The Privacy sector is still down -11% on the month. Meme (+1.5%) followed on M (+44%), CEX (+0.2%) edged higher on BNB (+1%), and RWA (-0.2%) held near flat.
L2 fell furthest at -8.8% on ARB (-15%), while AI (-6.1%) followed NEAR (-10%) in a week of renewed pressure on AI-linked equities. DeFi (-6.0%) tracked RAIN (-14%), which is releasing roughly $10.6M of tokens a day through linear emissions. Gaming (-5.2%) carried SAND (-21%), NFT (-5.2%) followed RENDER (-6%), and DePIN (-5.1%) and Infra (-4.8%) fell with TAO (-8%) and LINK (-6%). The rest of the board fell 3.2% to 3.9%, with L1 (-3.4%) on BTC (-4%), Social (-3.2%) on PUMP (-6%), and the HYPE-driven Perps (-3.3%) and DEX (-3.9%) both falling with HYPE (-3%).
Data appendix. Each Market Pulse tile shows where a gauge sits in its own trailing one-year range: the bar runs from the year's low to its high, the dark marker is this week's reading, and the colored span behind it is the week's move, green when the gauge climbed its range and red when it fell. Tags mark position in that range: HIGH above the 65th percentile, LOW below the 35th, NEUTRAL between, with the tag's color carrying the read. Funding is BTC perpetual funding, OI-weighted across major venues and annualized; onchain yield is Aave v3's USDC market on Ethereum; stablecoin flows is the 7-day net change in supply of all USD-pegged stablecoins across all chains per DeFiLlama; open interest sums futures in the twelve largest futures assets (roughly 95% of all crypto futures OI) against total crypto market cap; ETF flows combines US spot Bitcoin and Ethereum funds on a rolling 7 days; and altcoins is the share of the top 100, excluding stablecoins and wrappers, beating BTC over 7 days. Sector returns are cap-weighted CoinGecko categories, top ten constituents each. Sources: GSR Research, Glassnode, Deribit, CoinGecko, DeFiLlama, FRED, Tokenomist.
This material is provided by GSR (the “Firm”) solely for informational purposes. It is not intended to be advice or a recommendation to buy, sell or hold any investment mentioned. Investors should form their own views in relation to any proposed investment.
It is intended only for sophisticated, institutional investors and does not constitute an offer or commitment, a solicitation of an offer or commitment, or any advice or recommendation, to enter into or conclude any transaction (whether on the terms shown or otherwise), or to provide investment services in any state or country where such an offer or solicitation or provision would be illegal. The Firm is not and does not act as an advisor or fiduciary in providing this material.
This material is not an independent research report, and has not been prepared in accordance with any legal requirements by any regulator (including the FCA, FINRA or CFTC) designed to promote the independence of investment research.
This material is not independent of the Firm’s proprietary interests, which may conflict with the interests of any counterparty of the Firm. The Firm may trade investments discussed in this material for its own account, may trade contrary to the views expressed in this material, and may have positions in other related instruments. The Firm is not subject to any prohibition on dealing ahead of the dissemination of this material.
Information contained herein is based on sources considered to be reliable, but is not guaranteed to be accurate or complete. Any opinions or estimates expressed herein reflect a judgment made by the author(s) as of the date of publication, and are subject to change without notice. The Firm does not plan to update this information.
Trading and investing in digital assets involves significant risks including price volatility and illiquidity and may not be suitable for all investors. The Firm is not liable whatsoever for any direct or consequential loss arising from the use of this material. Copyright of this material belongs to GSR. Neither this material nor any copy thereof may be taken, reproduced or redistributed, directly or indirectly, without prior written permission of GSR.
Please see here for additional Regulatory Legal Notices relevant to US, UK and Singapore.