GSR Weekly - Oct 5, 2026
Carlos Guzman
Research Analyst
Slater Santer
Research Analyst

Carlos Guzman
Research Analyst
Slater Santer
Research Analyst
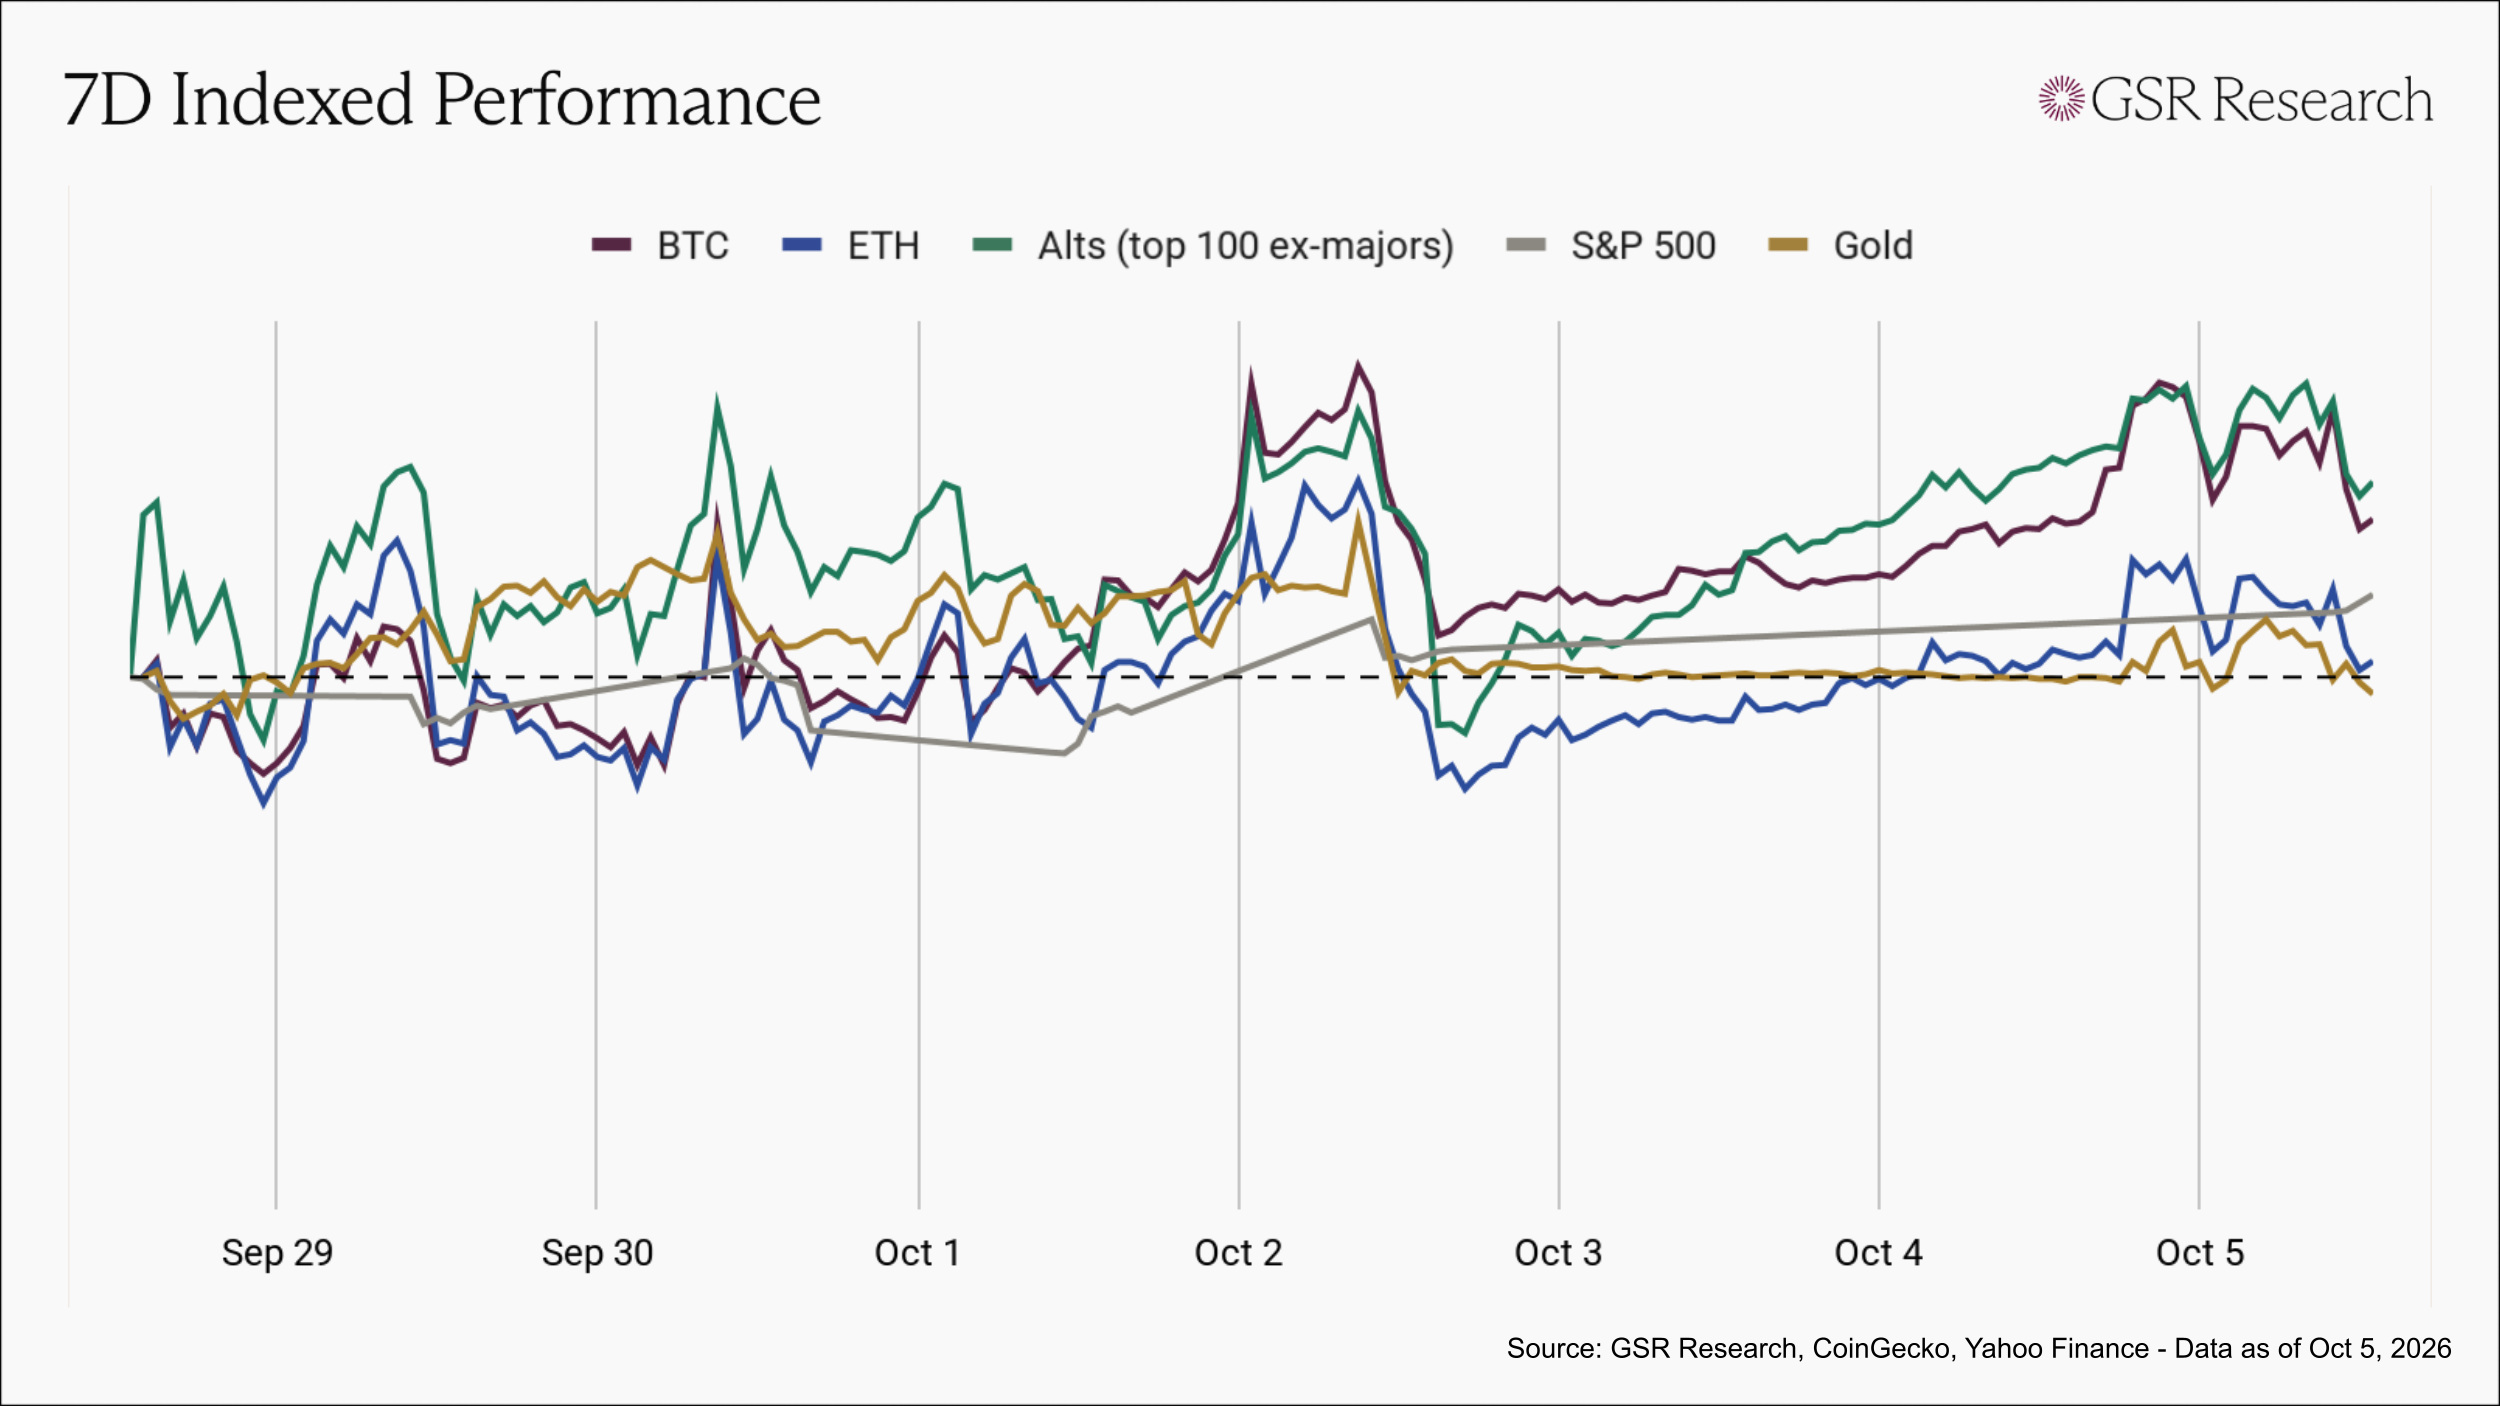
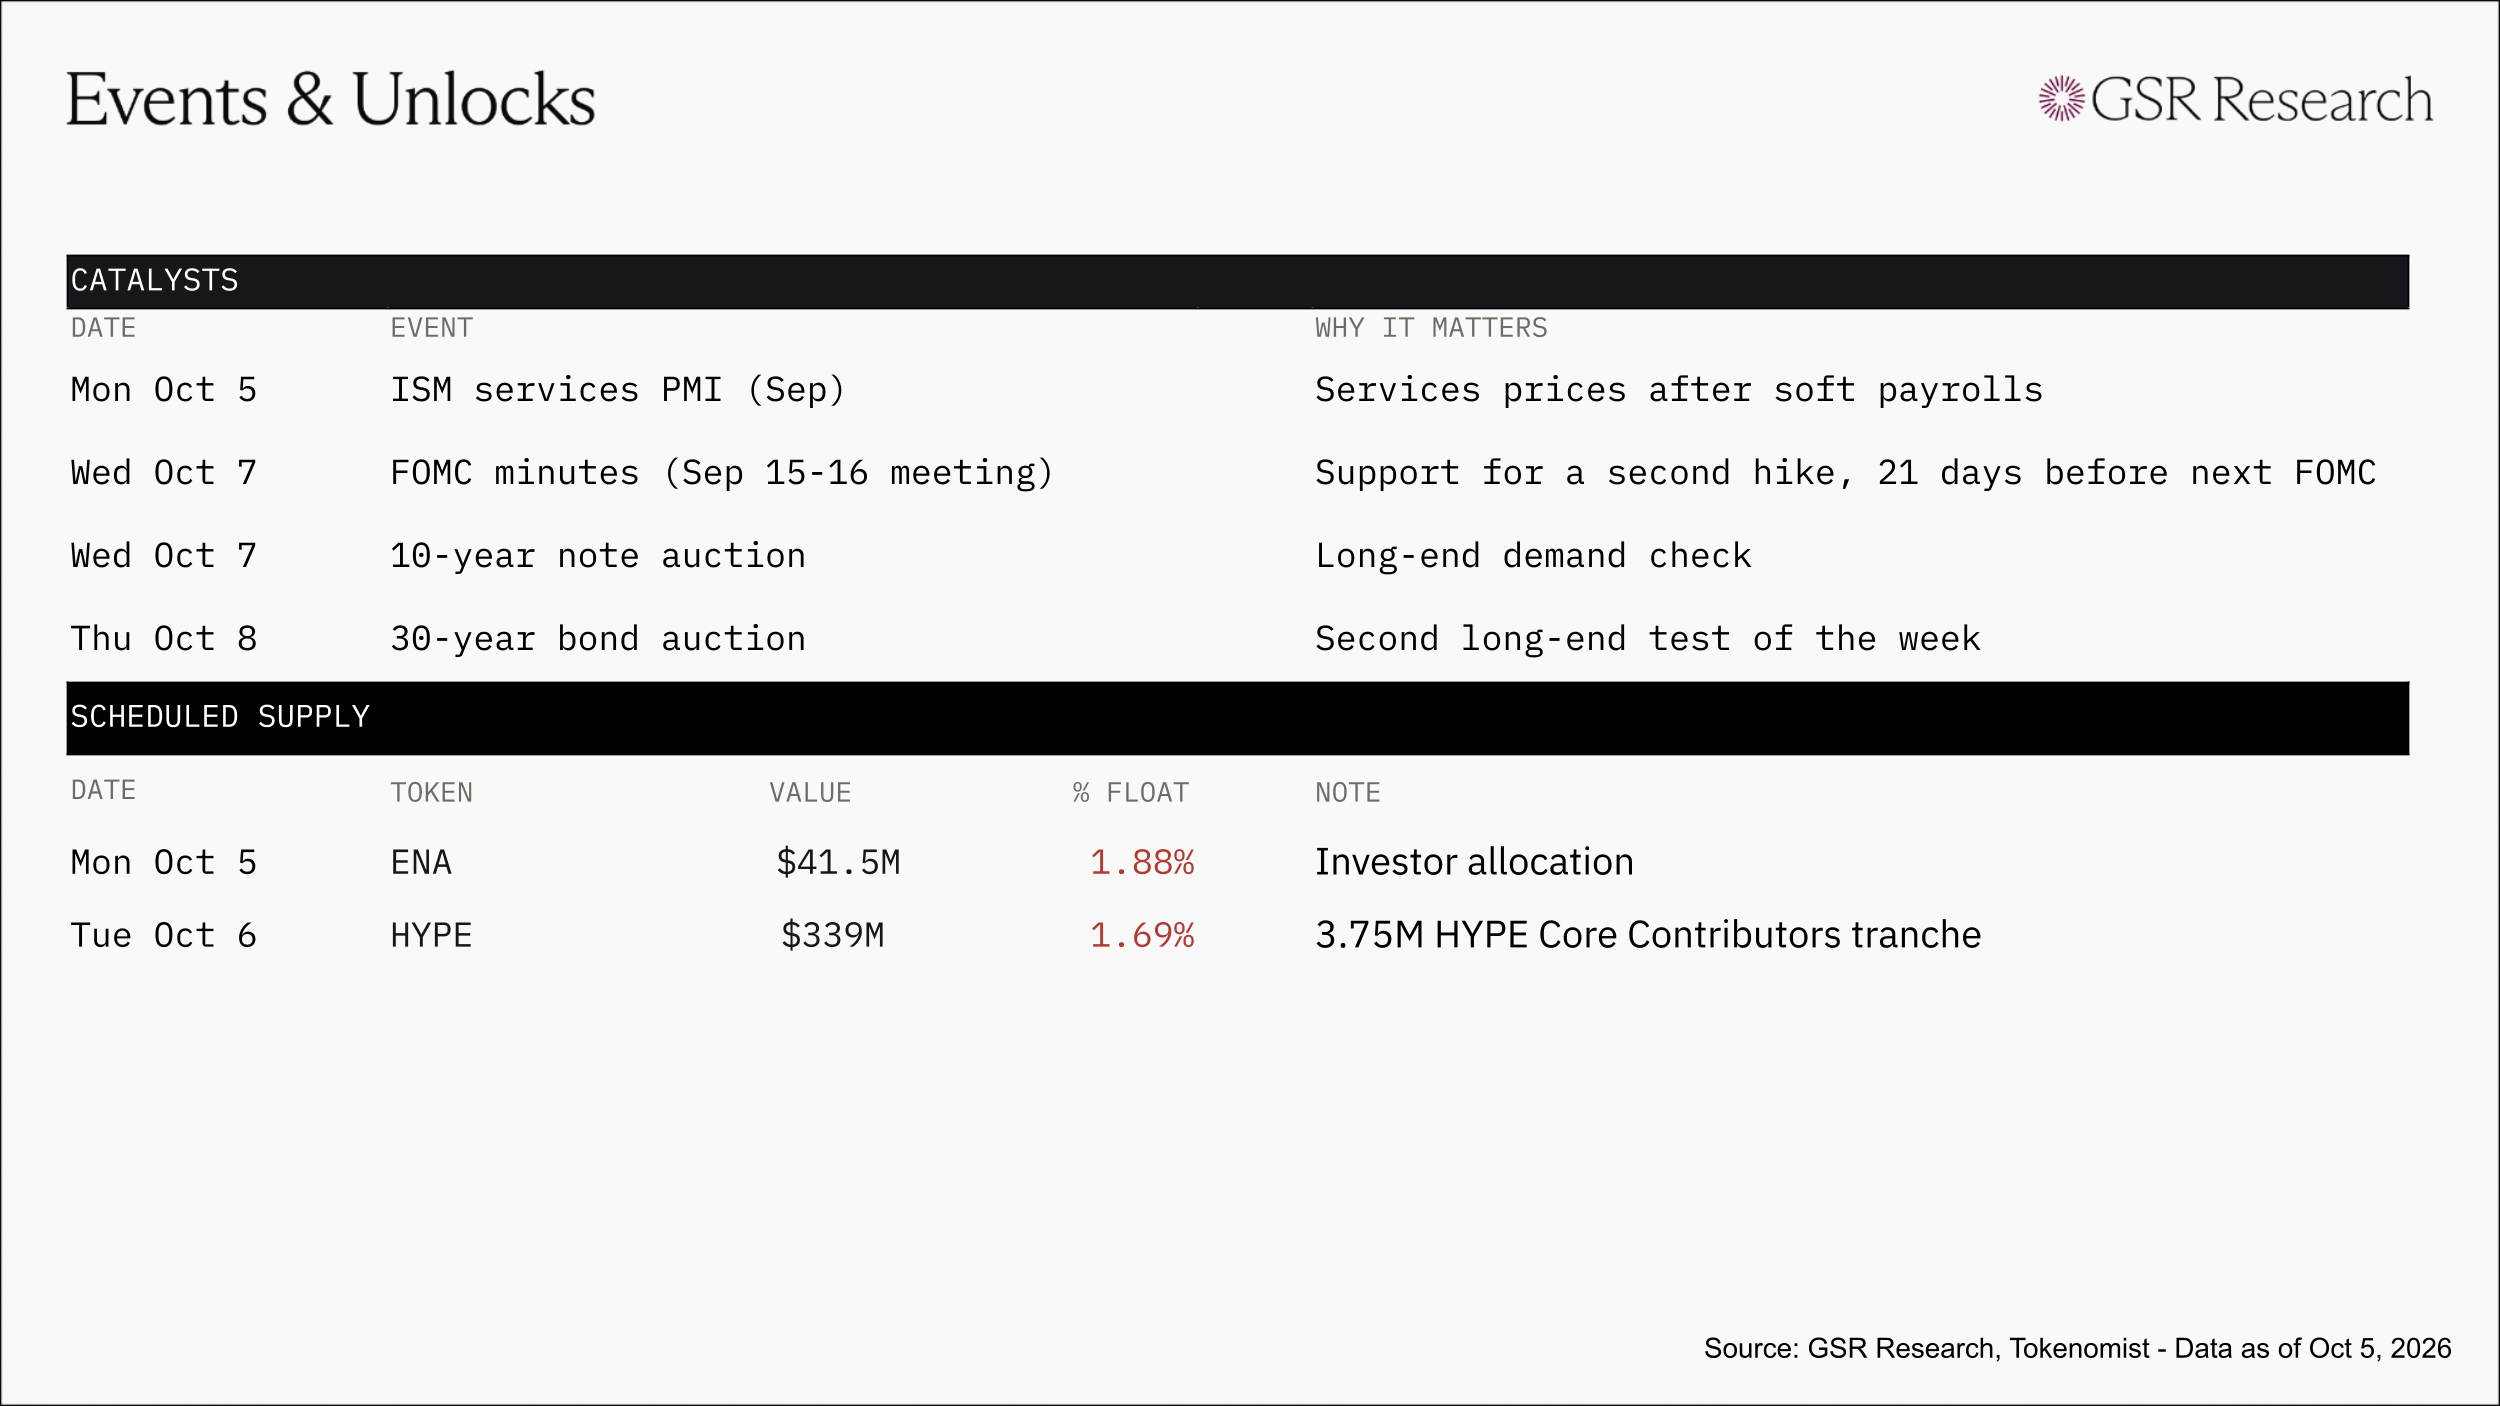
The week opened with CME FedWatch pricing a ~70% chance of a hike at the October 27-28 meeting, and odds began falling on Tuesday when New York Fed President Williams said the September hike left "no need for urgency," while still calling one more increase appropriate "late this year," with odds dropping to about 50% within the session. Wednesday's August PCE print took them to 35%, as core PCE rose 3.0% year-over-year against a 3.3% consensus and headline came in at 3.4% against 3.7% expected, although most of the change was due to a change in the BEA’s methodology for calculating prices for software, legal fees, and investment advice. Friday's September jobs report then showed payrolls rising 29,000 against an 84,000 consensus, with prior months revised down a combined 60,000 and wage growth slowing to 3.0% year-over-year, the weakest since 2021, and hike odds fell as Treasury yields and the dollar declined. BTC jumped from $86,000 to $87,229 immediately after the release before reversing below $84,000 that afternoon, with more than $570M liquidated market-wide in 24 hours and longs accounting for nearly all of the final leg. BTC finished up ~3% at $86k, ETH and the alt basket each ~1% higher, gold roughly flat, and the S&P modestly higher.
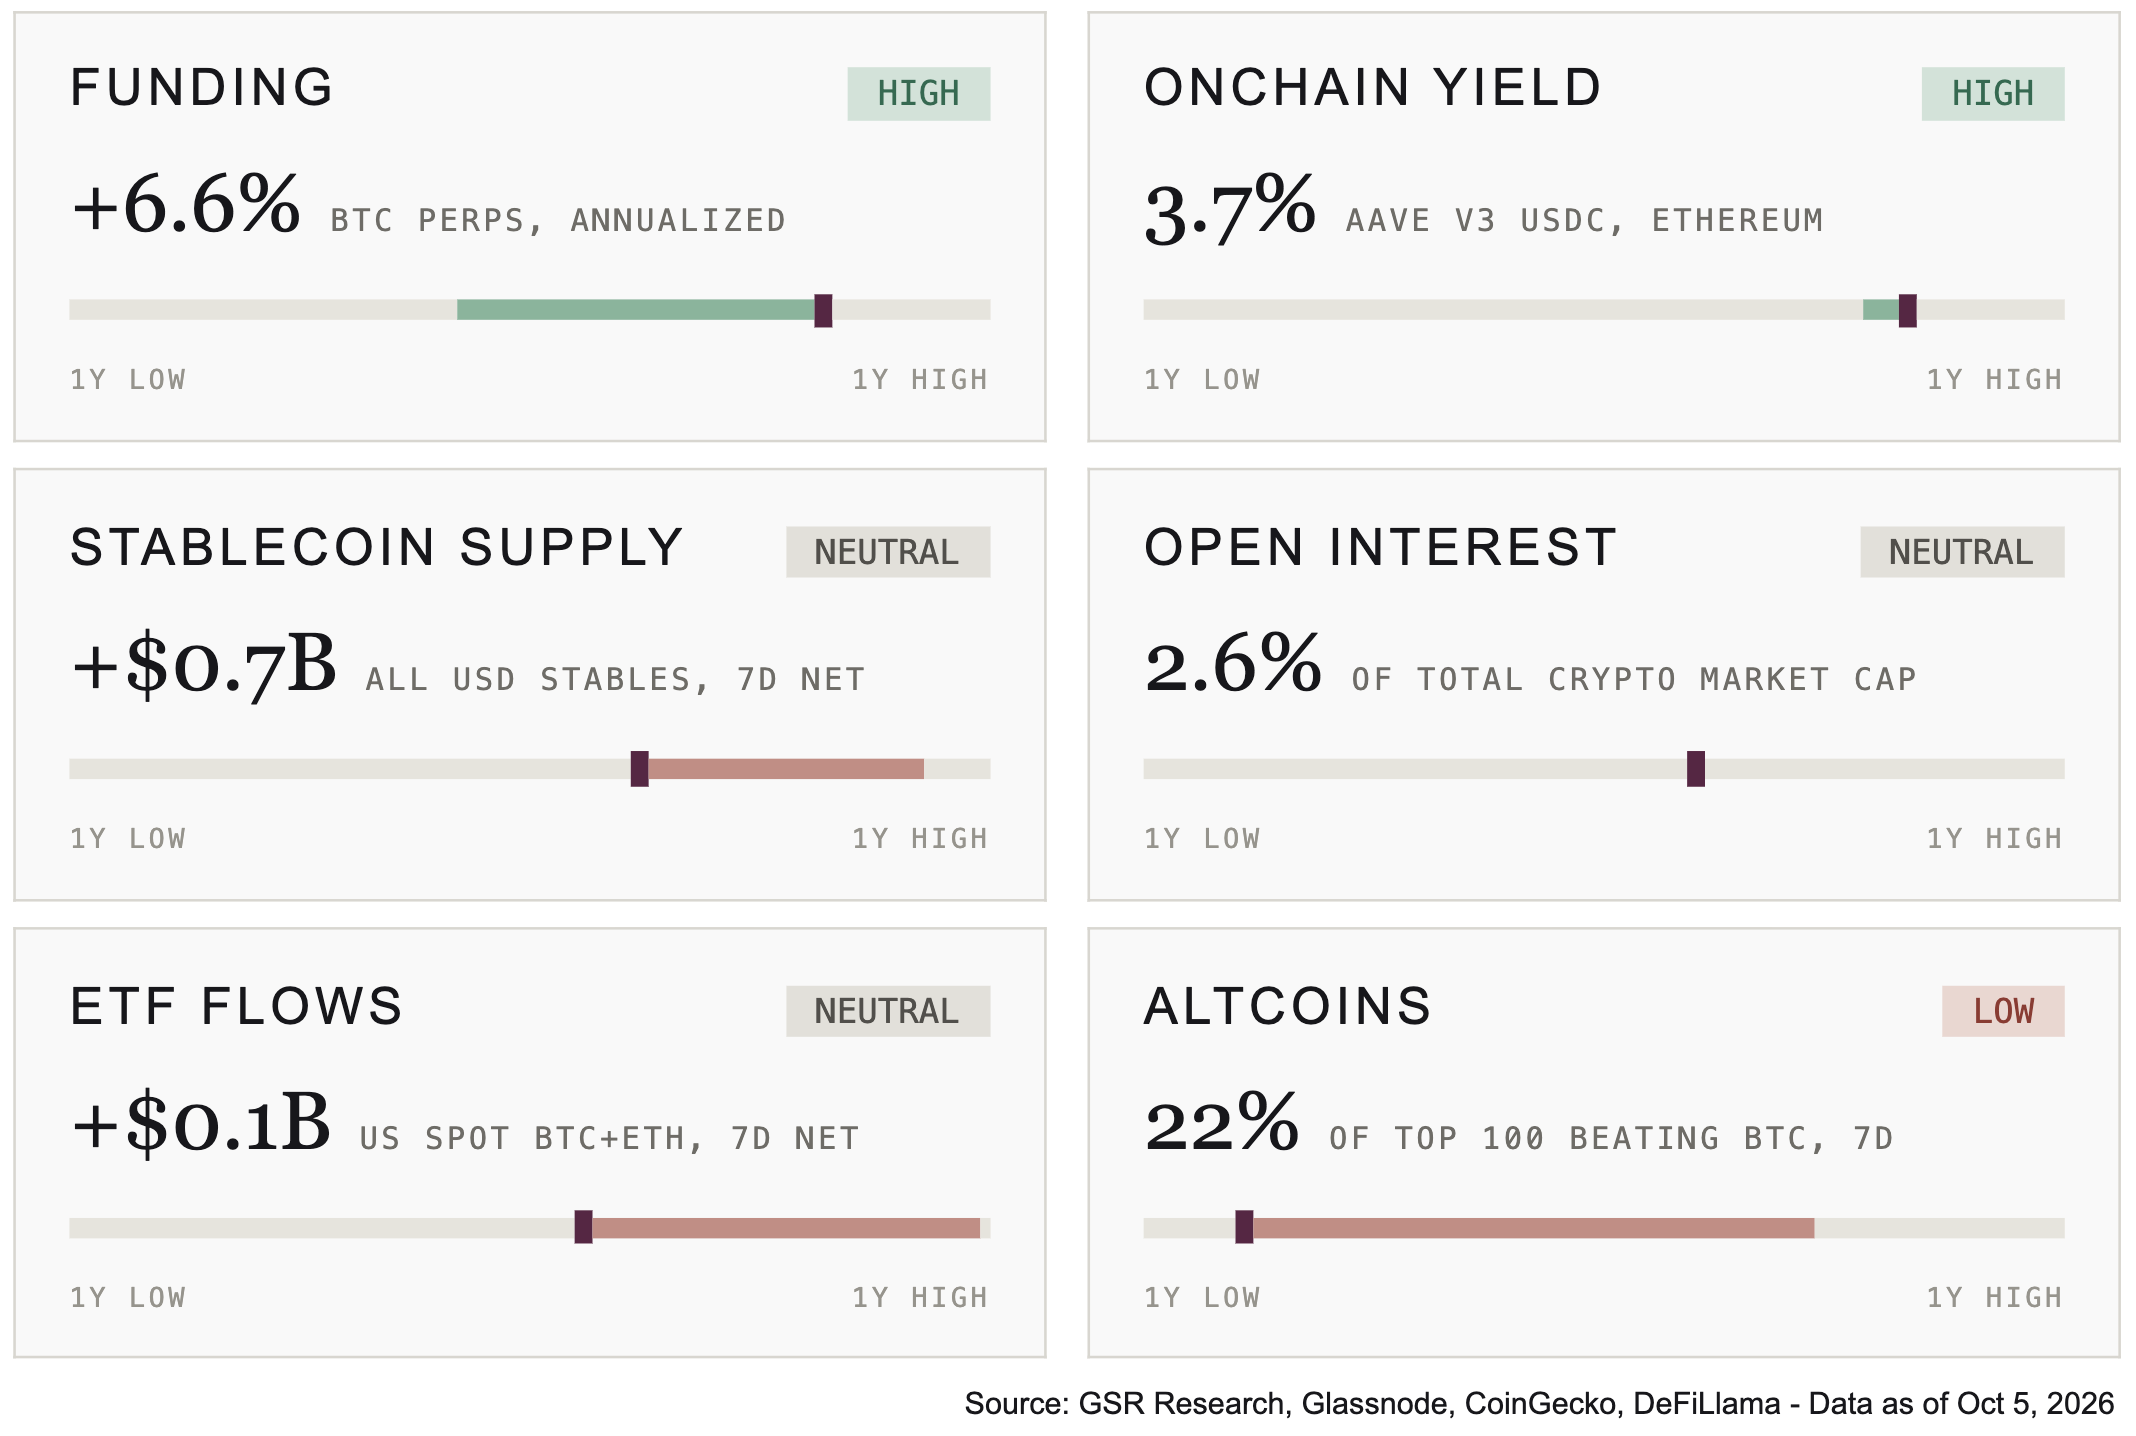
The market pulse gauge cooled this week, with most indicators returning to the neutral range. Funding was an exception, rising from +2.4% to +6.6% annualized, back into the high range, while open interest held at 2.6% of total market cap. Both flow gauges slowed, as ETF flows fell from +$3.4B to +$0.1B while Stablecoin Supply dropped from +$2.8B to +$0.7B. Onchain yield edged up from 3.6% to 3.7%. Altcoins struggled this week, with performance dropping from 54 to only 22 of the top 100 beating Bitcoin, near the bottom of its one-year range.
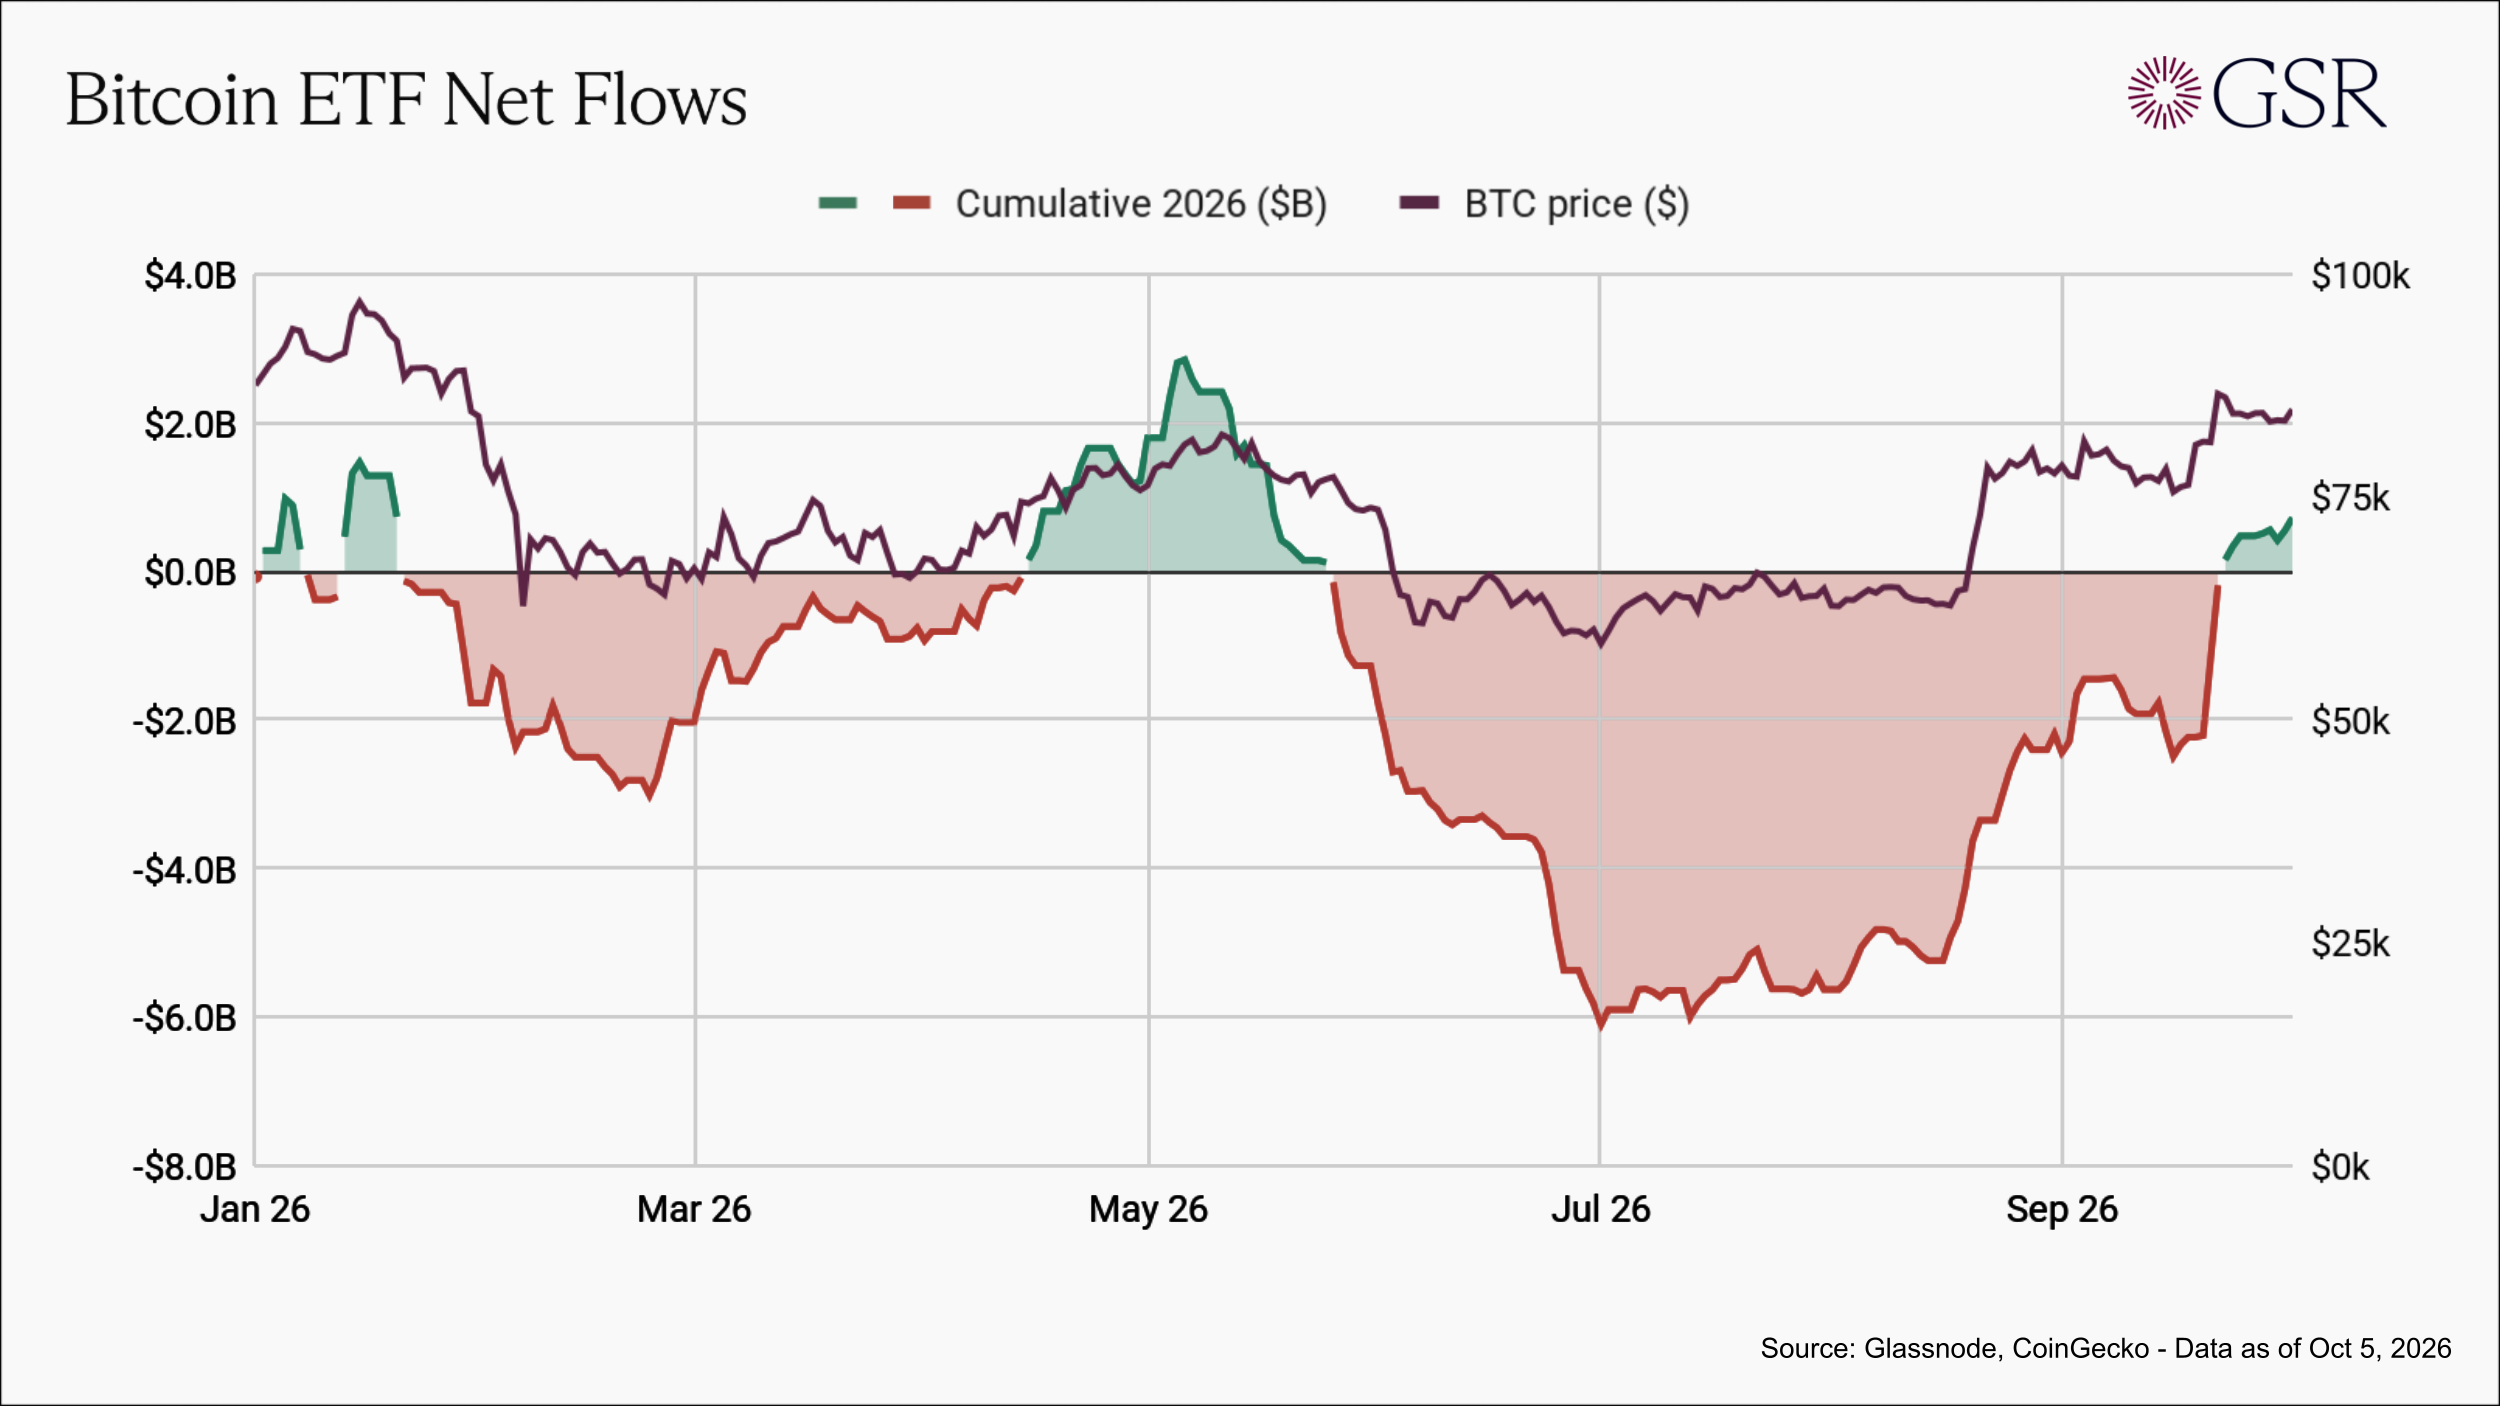
Cumulative 2026 net flows into U.S. spot Bitcoin ETFs turned positive again on Tuesday, September 22, and now sit near +$0.7B YTD, up from a low near -$6.1B on July 1, the same day BTC closed at its 2026 low of $58,566. The recovery came largely in two bursts, with +$1.92B in inflows during the mid-August BTC rally from $63k to above $79k, and +$2.39B in the week ending September 25, the largest since the week ending October 10, 2025, with Monday's $999M inflow representing the largest single day of 2026. The line last turned positive in mid-April, when net inflows ran for roughly three weeks to a peak near +$2.9B in early May before turning negative in late May. At that point, a $9B swing took net inflows for the calendar year to the July low of around -$6.0B. Price has recovered faster than flows since then, with BTC now ~5% above its May high while the year-to-date ETF flow total sits roughly $2.2B below its May peak. Momentum has faded since the cross back to positive cumulative flows, as daily inflows slowed from $999M on September 21 to $134M by that Friday, a $149M outflow on September 30 snapped a nine-session inflow streak, and the week closed at +$241M. The $6B of net redemptions through early July has now been fully absorbed in just three months.
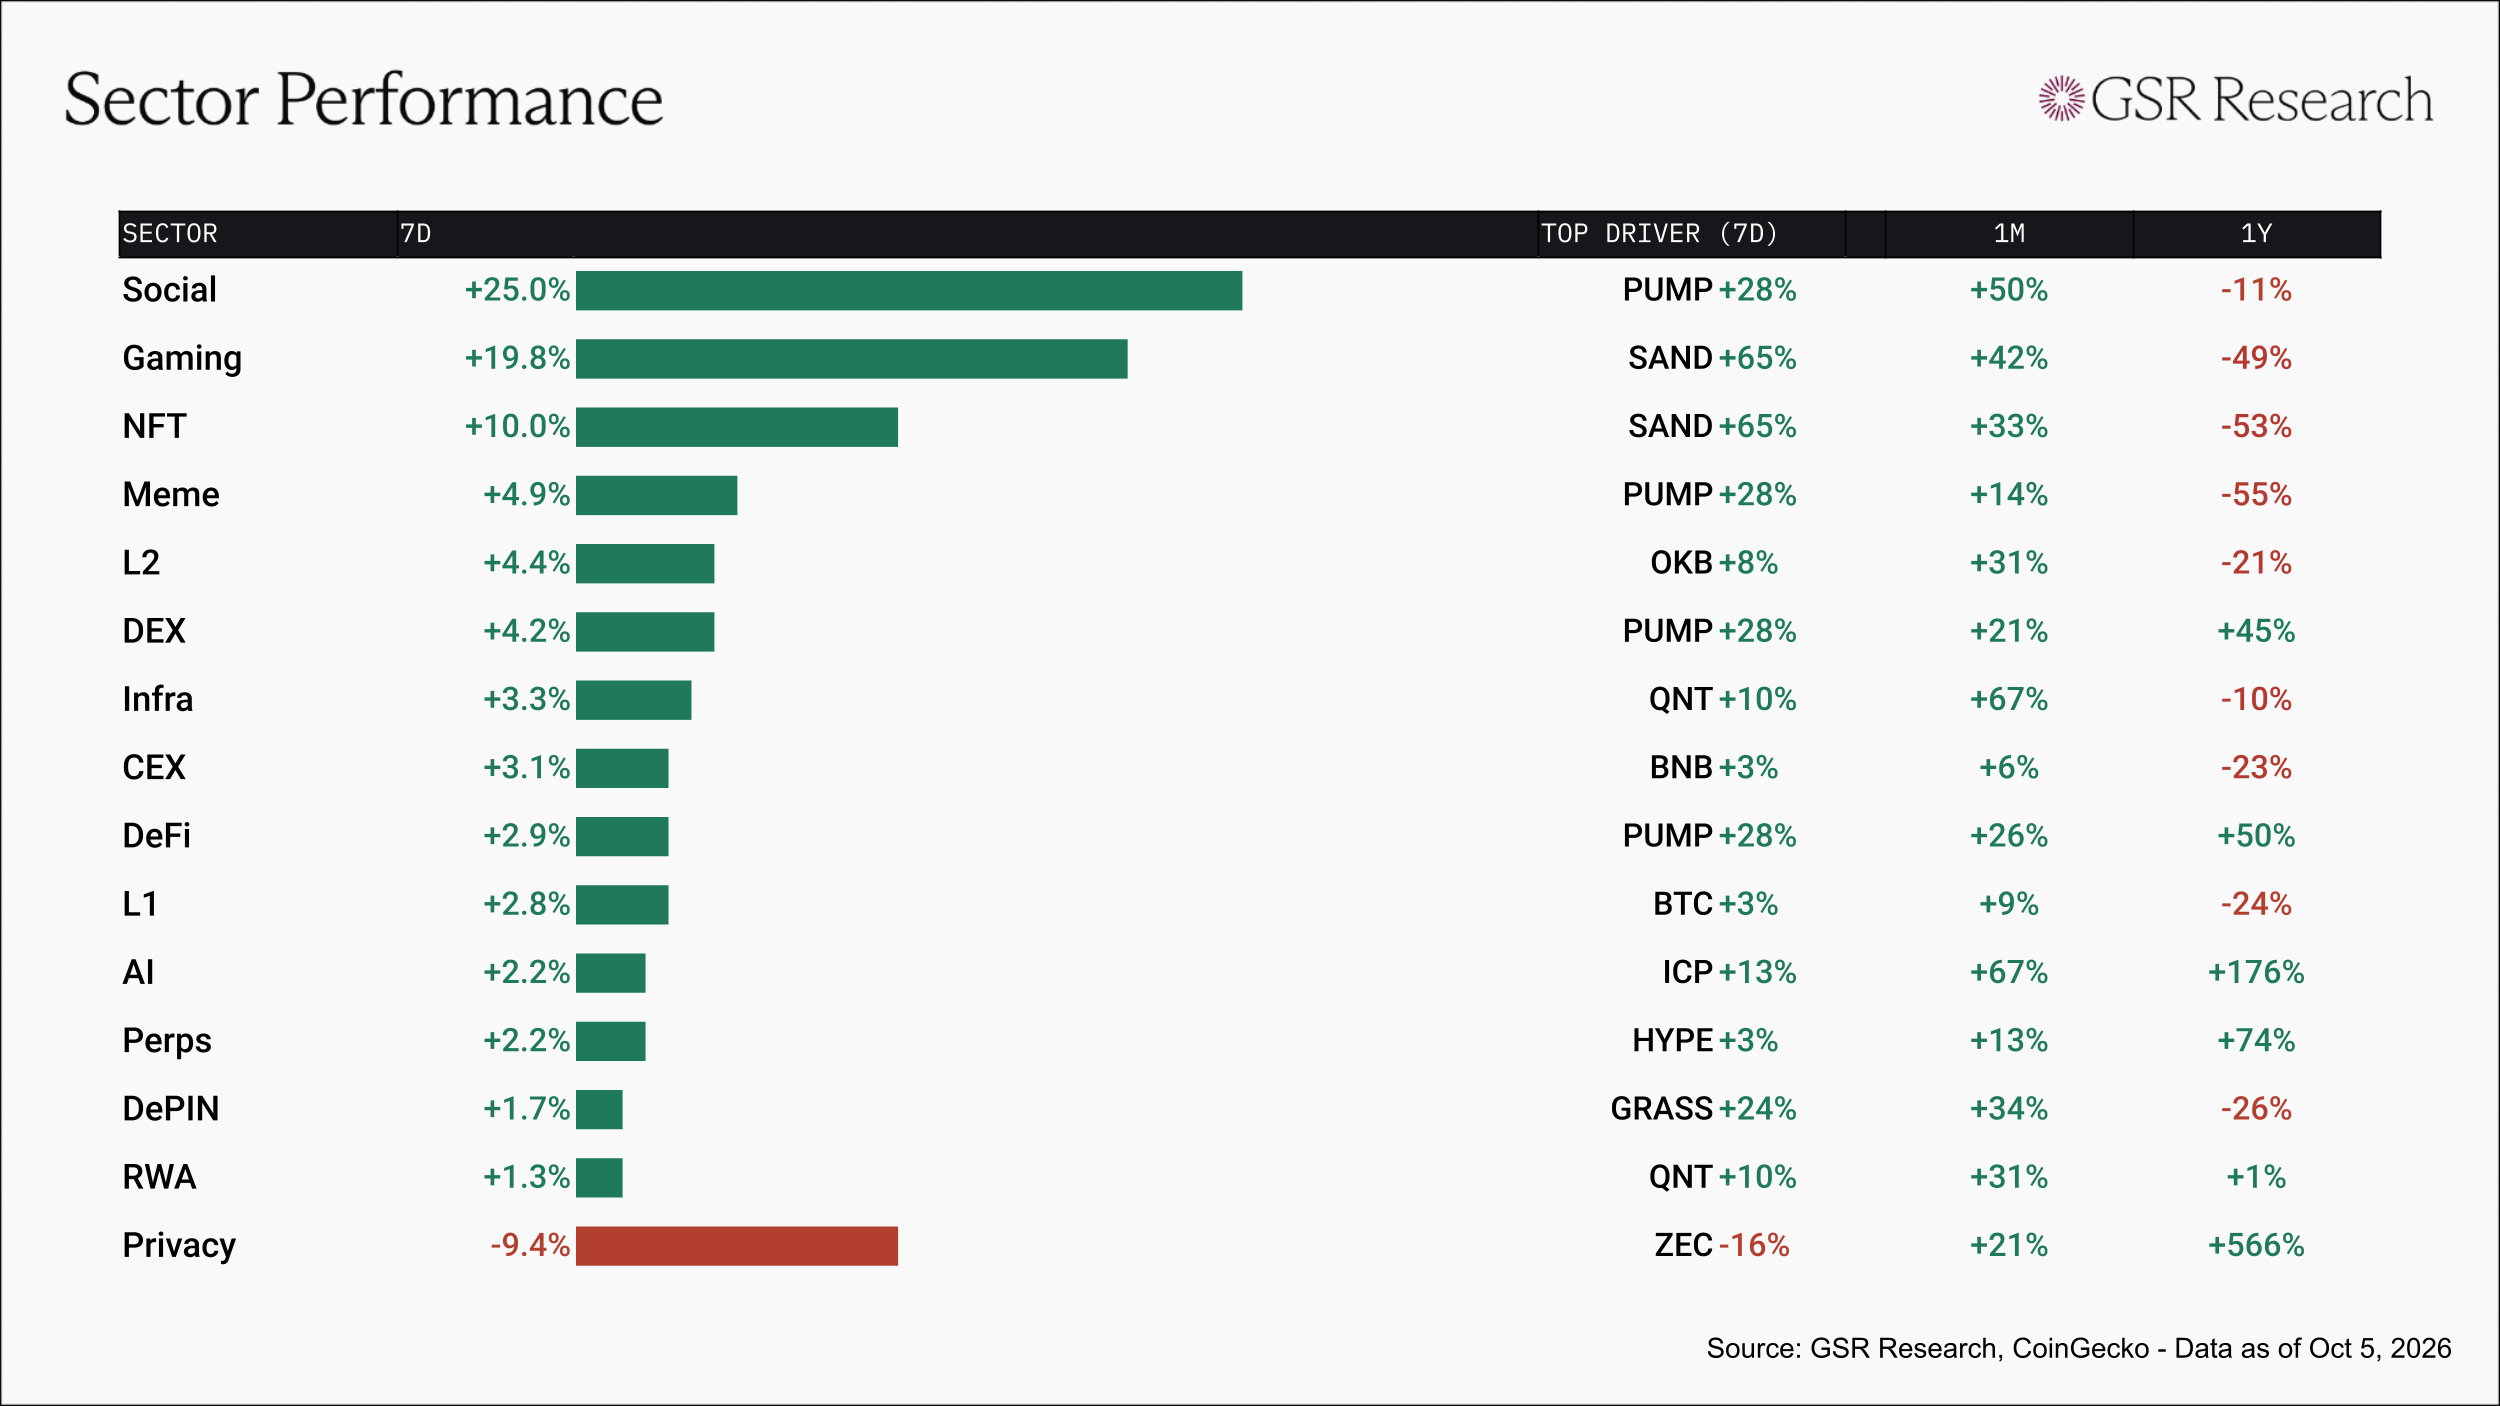
14 of 15 sectors closed green this week, as Social led at +25.0% on PUMP (+28%), which nearly doubled from its mid-September low as Pump.fun moved back ahead of Hyperliquid in 30-day revenue on DefiLlama ($55.5M against $54.3M), roughly 45% of which goes to buybacks. Gaming (+19.8%) and NFT (+10.0%) both rode SAND (+65%), which rallied after Upbit, Bithumb, and Coinone lifted the trading caution designations they had placed on the token following the August 22 exploit of its cross-chain bridge, restoring deposits and withdrawals for Korean holders. PUMP also carried Meme (+4.9%), DEX (+4.2%), and DeFi (+2.9%), and L2 (+4.4%) rose on OKB (+8%).
Privacy (-9.4%) was the only sector to decline, as ZEC (-16%) fell back toward $1,340 with Grayscale's ZCSH posting $93.6M of net outflows, its first negative week since launching on August 25, with the sector still up +21% on the month. Infra (+3.3%) and RWA (+1.3%) held on QNT (+10%), which extended last week's +240% move, while CEX (+3.1%) followed BNB (+3%) and L1 (+2.8%) tracked BTC (+3%). AI (+2.2%) rose on ICP (+13%), Perps (+2.2%) moved with HYPE (+3%) ahead of Tuesday's unlock, and DePIN (+1.7%) lagged despite GRASS (+24%). DoubleZero's 2Z fell 31% through Friday's unlock, which increased circulating supply by 48%.
Data appendix. Each Market Pulse tile shows where a gauge sits in its own trailing one-year range: the bar runs from the year's low to its high, the dark marker is this week's reading, and the colored span behind it is the week's move, green when the gauge climbed its range and red when it fell. Tags mark position in that range: HIGH above the 65th percentile, LOW below the 35th, NEUTRAL between, with the tag's color carrying the read. Funding is BTC perpetual funding, OI-weighted across major venues and annualized; onchain yield is Aave v3's USDC market on Ethereum; stablecoin flows is the 7-day net change in supply of all USD-pegged stablecoins across all chains per DeFiLlama; open interest sums futures in the twelve largest futures assets (roughly 95% of all crypto futures OI) against total crypto market cap; ETF flows combines US spot Bitcoin and Ethereum funds on a rolling 7 days; and altcoins is the share of the top 100, excluding stablecoins and wrappers, beating BTC over 7 days. Sector returns are cap-weighted CoinGecko categories, top ten constituents each. Sources: GSR Research, Glassnode, Deribit, CoinGecko, DeFiLlama, FRED, Tokenomist.
This material is provided by GSR (the “Firm”) solely for informational purposes. It is not intended to be advice or a recommendation to buy, sell or hold any investment mentioned. Investors should form their own views in relation to any proposed investment.
It is intended only for sophisticated, institutional investors and does not constitute an offer or commitment, a solicitation of an offer or commitment, or any advice or recommendation, to enter into or conclude any transaction (whether on the terms shown or otherwise), or to provide investment services in any state or country where such an offer or solicitation or provision would be illegal. The Firm is not and does not act as an advisor or fiduciary in providing this material.
This material is not an independent research report, and has not been prepared in accordance with any legal requirements by any regulator (including the FCA, FINRA or CFTC) designed to promote the independence of investment research.
This material is not independent of the Firm’s proprietary interests, which may conflict with the interests of any counterparty of the Firm. The Firm may trade investments discussed in this material for its own account, may trade contrary to the views expressed in this material, and may have positions in other related instruments. The Firm is not subject to any prohibition on dealing ahead of the dissemination of this material.
Information contained herein is based on sources considered to be reliable, but is not guaranteed to be accurate or complete. Any opinions or estimates expressed herein reflect a judgment made by the author(s) as of the date of publication, and are subject to change without notice. The Firm does not plan to update this information.
Trading and investing in digital assets involves significant risks including price volatility and illiquidity and may not be suitable for all investors. The Firm is not liable whatsoever for any direct or consequential loss arising from the use of this material. Copyright of this material belongs to GSR. Neither this material nor any copy thereof may be taken, reproduced or redistributed, directly or indirectly, without prior written permission of GSR.
Please see here for additional Regulatory Legal Notices relevant to US, UK and Singapore.