GSR Weekly - September 8, 2026
Carlos Guzman
Research Analyst
Slater Santer
Research Analyst

Carlos Guzman
Research Analyst
Slater Santer
Research Analyst
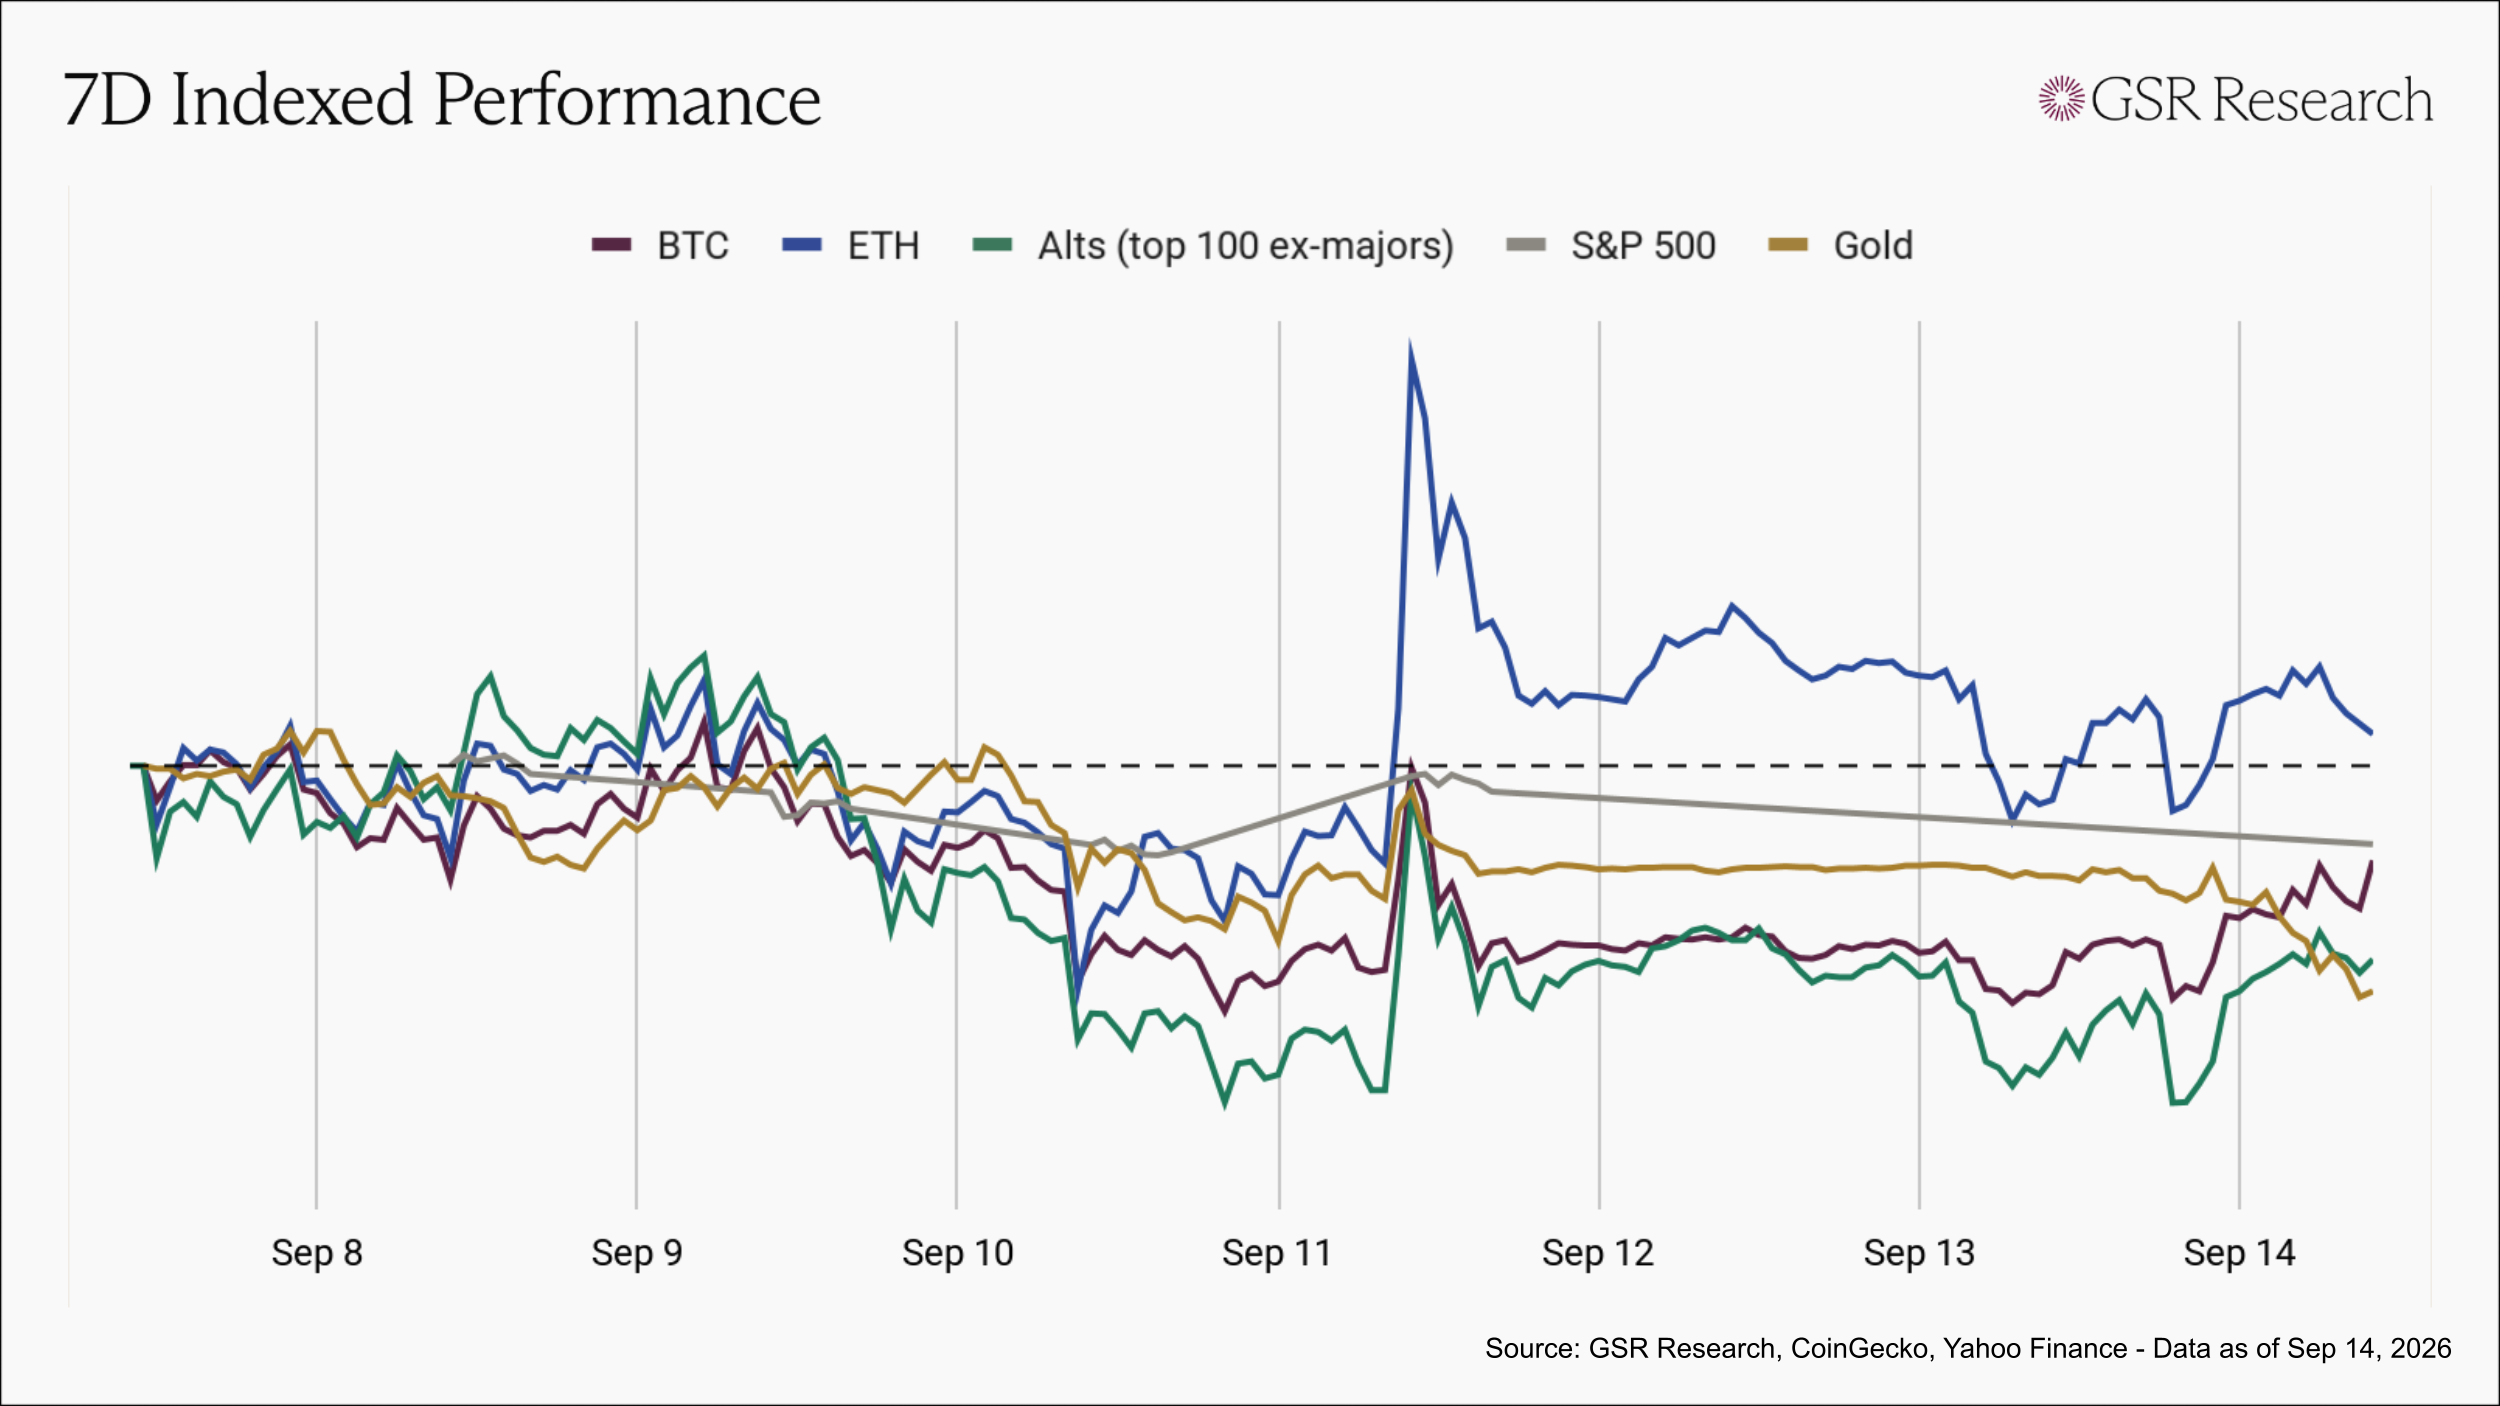
On Wednesday the Treasury said it would buy back up to $6B of 10 to 20-year bonds in Thursday's operation, triple its usual size but short of the $10B or more some in the market had expected after Secretary Bessent's comments, and long-end yields rose on the announcement, with the 10-year climbing above 4.85%. Thursday's operation itself took in $5.19B, below the maximum, and the 10-year extended to 4.95%, its highest since 2023, a notable reversal from August, when the program's expansion sent yields lower and kicked off the rally. Risk assets slid as hike odds for the September meeting climbed toward 70%, leaving BTC down ~5% and alts ~8% below Tuesday's highs by Thursday's close. Friday's CPI print brought a brief reprieve, despite headline inflation rising 0.4% on the month and 3.4% year-over-year, with gasoline up more than 25% from a year ago. BTC gained 4.5% within an hour to nearly $79k and ETH spiked more than 8% to $2,640, a seven-month high, before both faded through the afternoon as markets concluded the print did little to change Wednesday's decision. Hike odds on Kalshi sit at 78% as of writing. Alts gave back another 2-3% over the weekend and gold extended its slide, leaving BTC down ~2% on the week at $78k, ETH roughly flat, alts down ~4%, gold down ~4%, and the S&P ~1.5% lower.
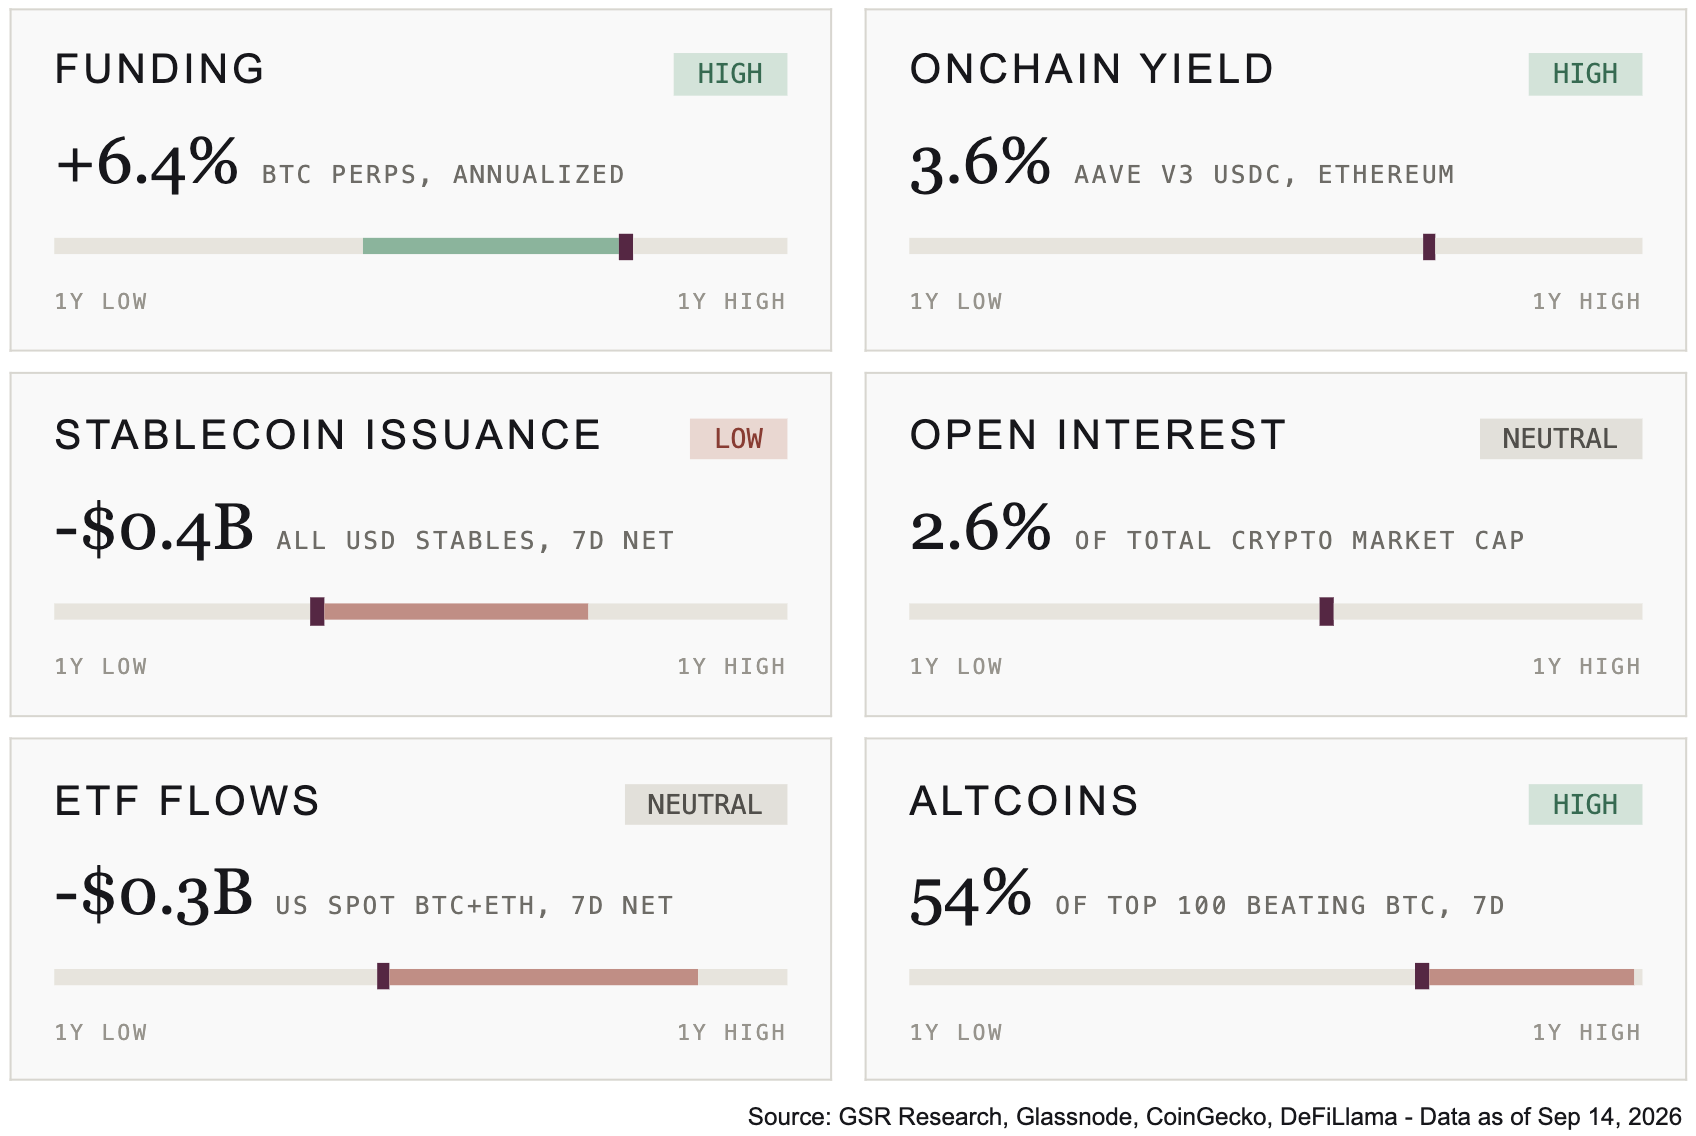
Funding rose from +2.3% to +6.4% annualized, back into the high range, even as prices fell, while open interest held at 2.6% of total market cap. Both flow gauges turned negative, with ETF flows at -$0.3B after three consecutive positive weeks, and stablecoin issuance swinging from +$1.4B to -$0.4B, the first net redemption since early August. Altcoin performance cooled from 83 to 54 of the top 100 altcoins beating Bitcoin, still significantly above the midpoint of its one-year range.
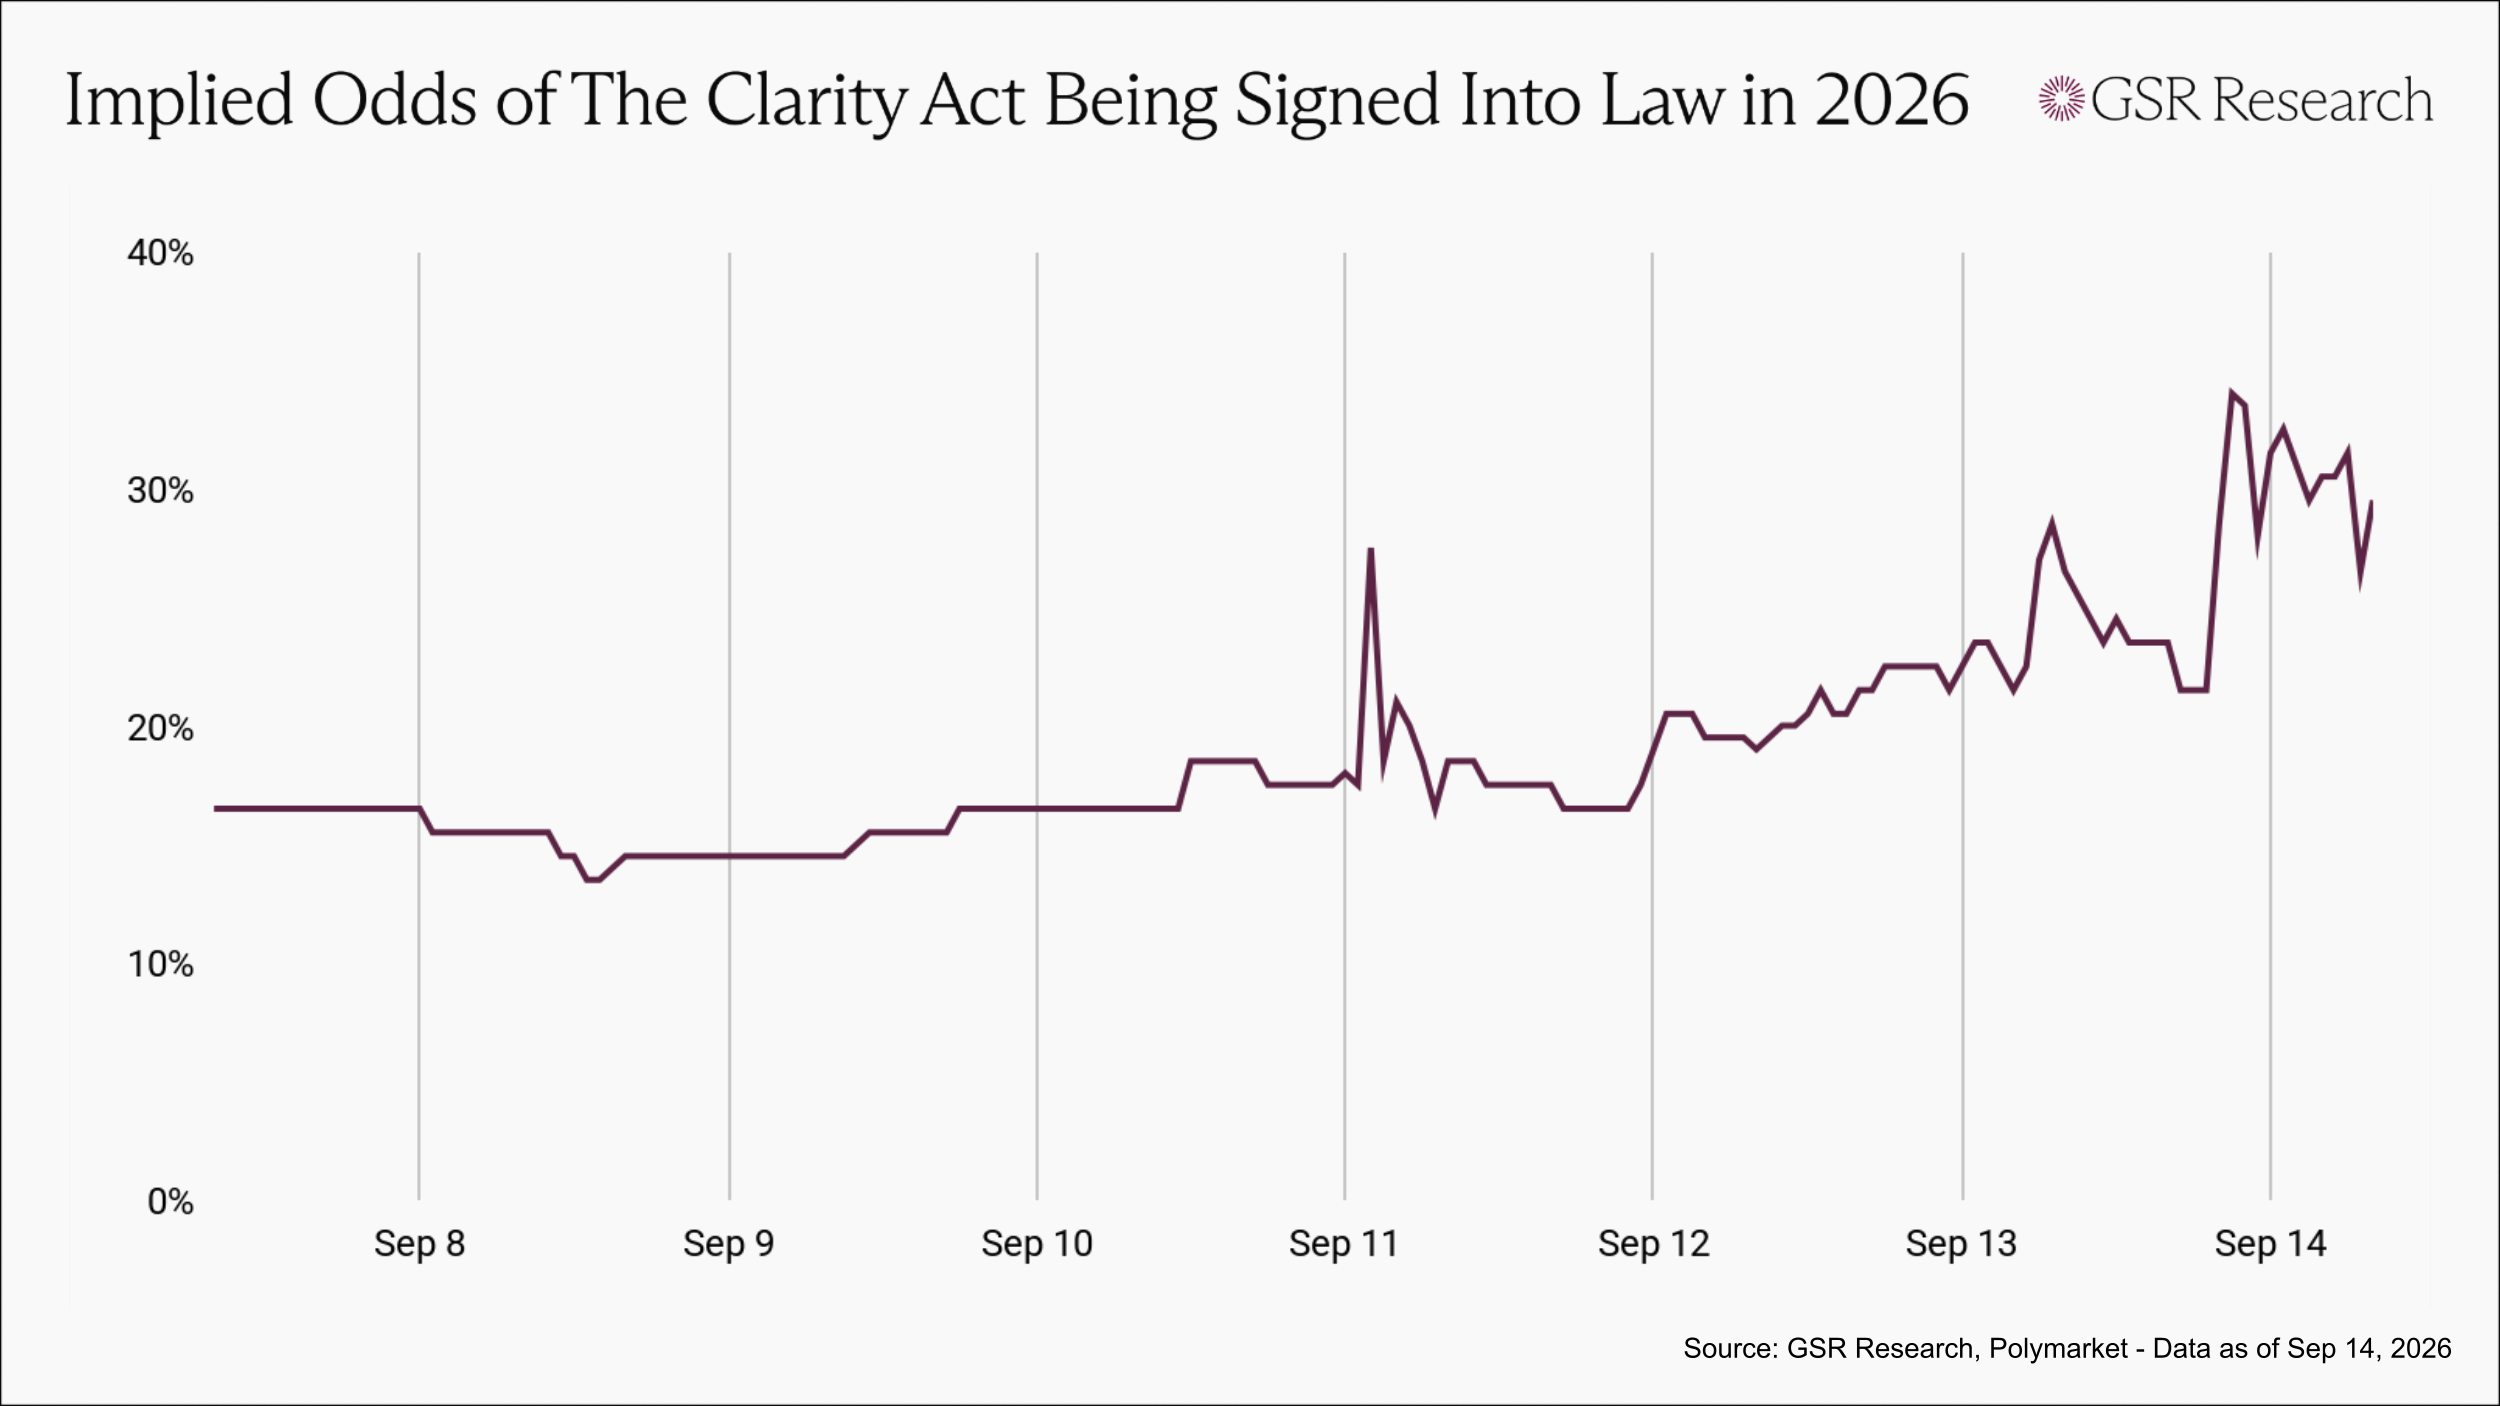
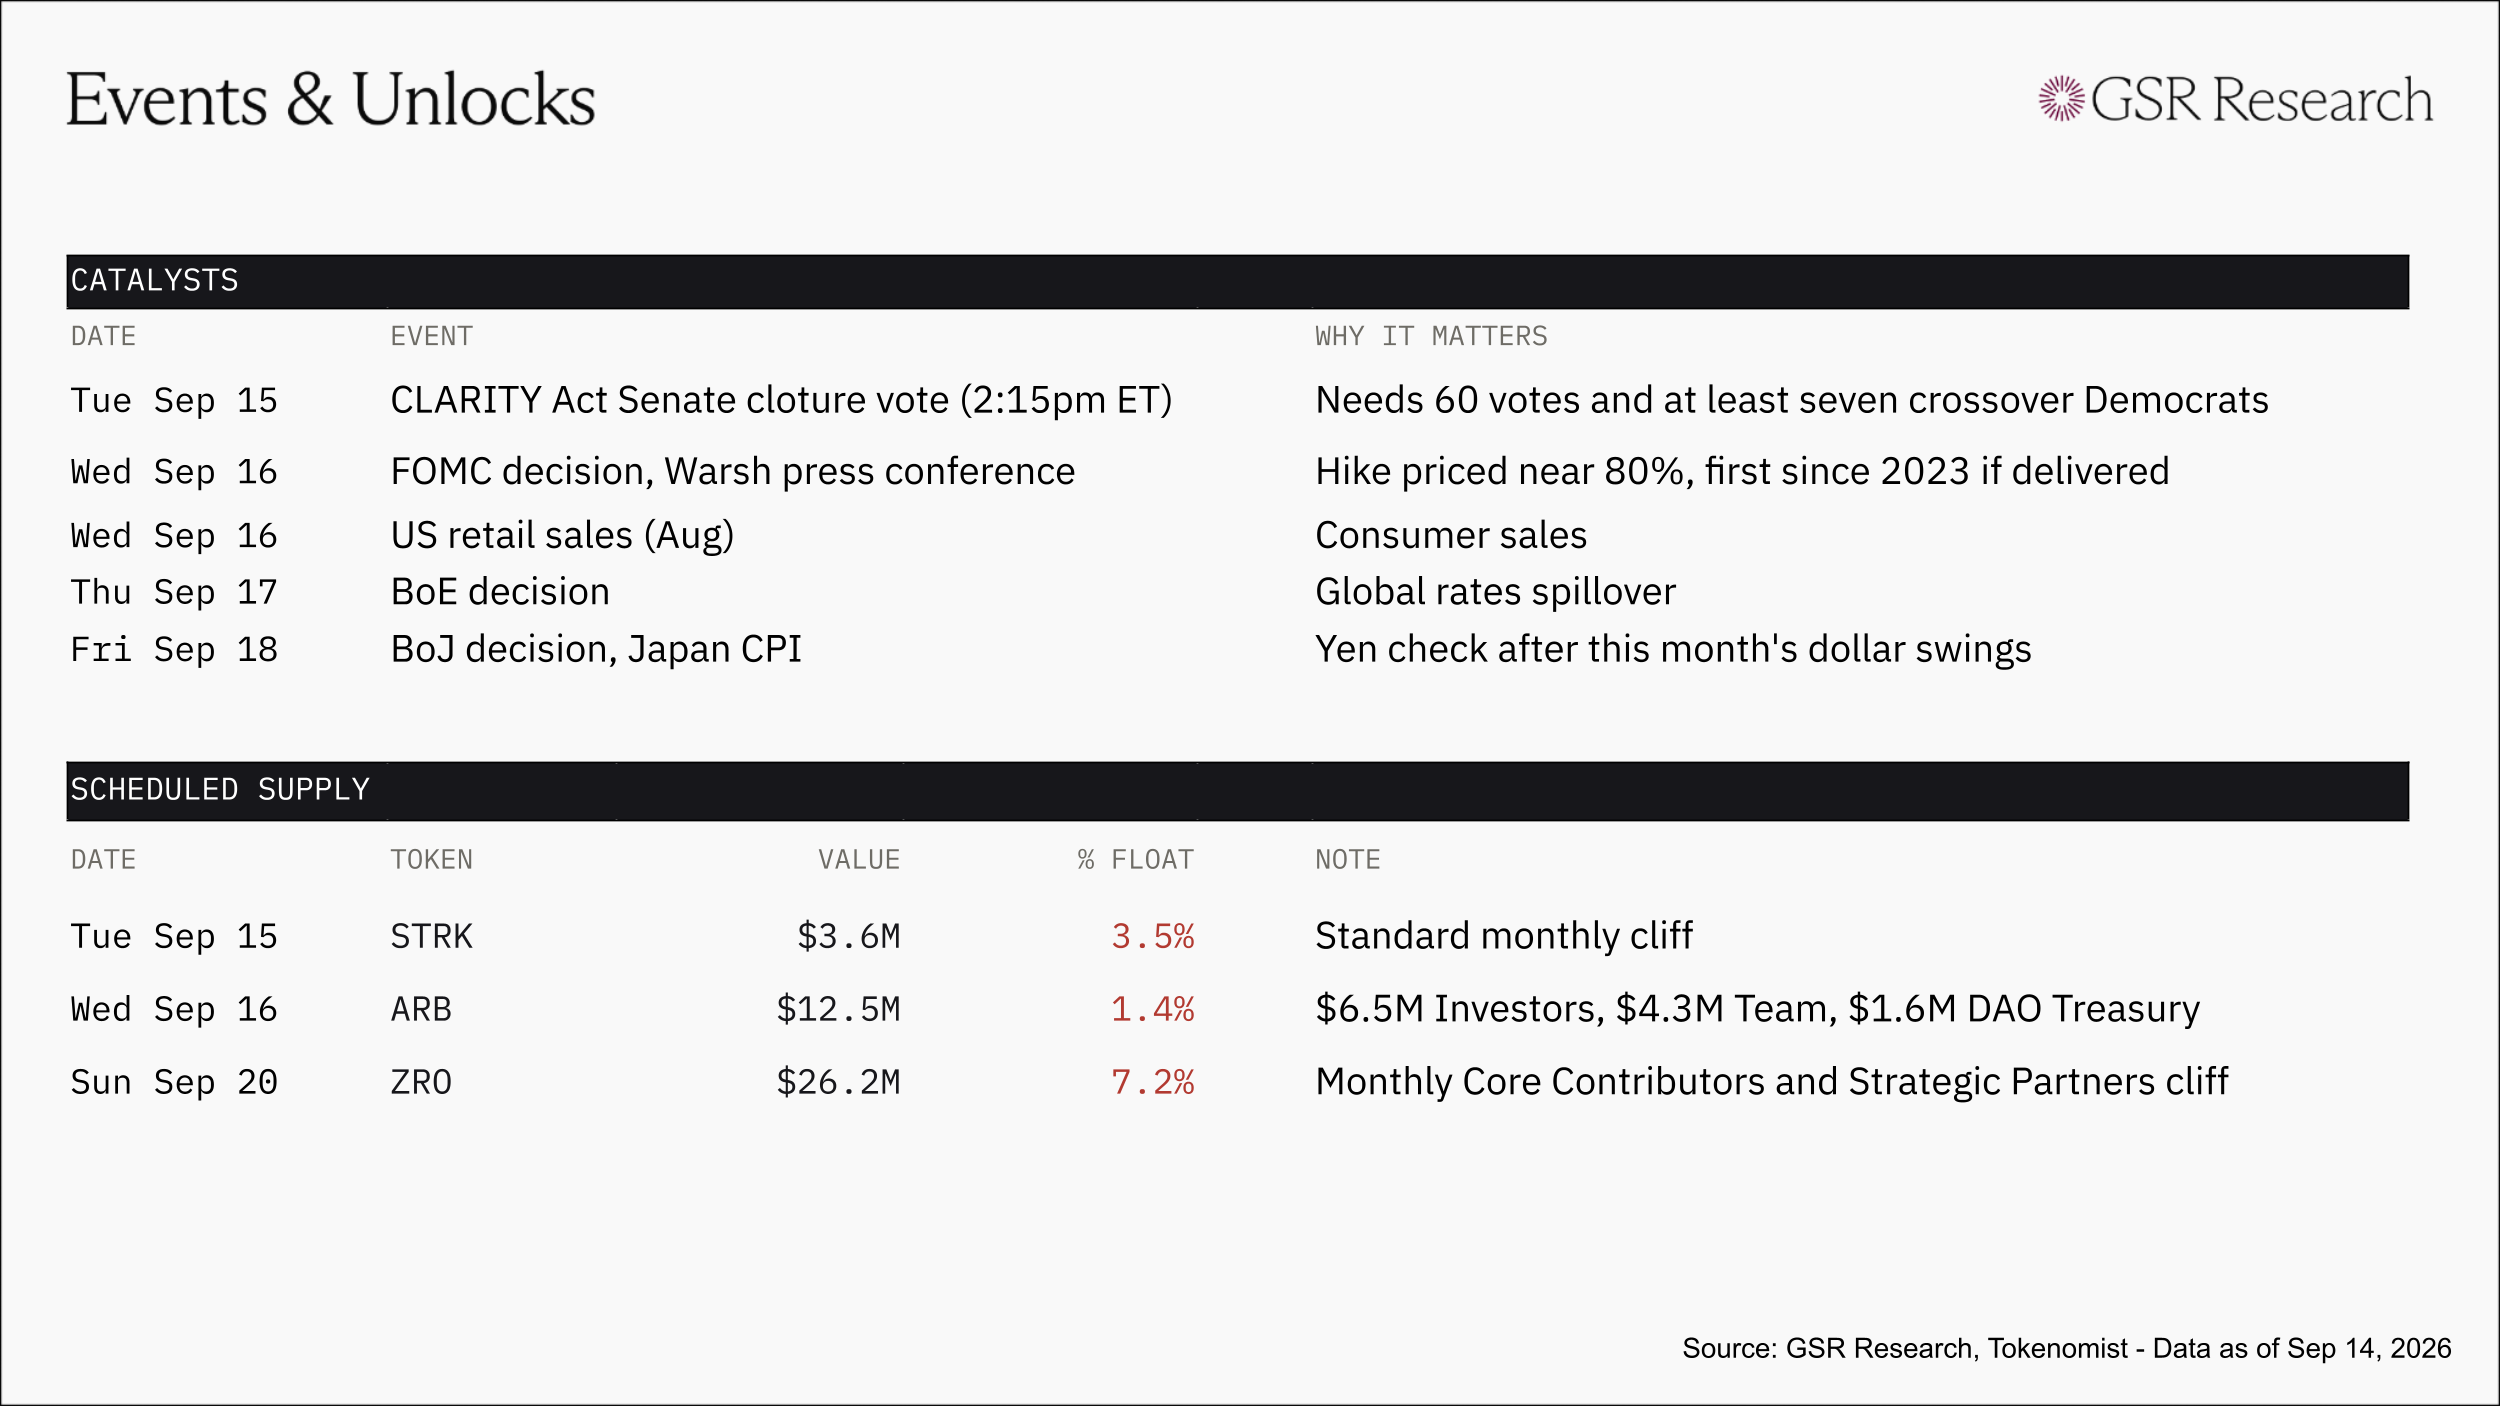
Late Sunday night, Senators Lummis, Boozman, and Scott released what they called the final text of the CLARITY Act, a 635-page substitute that combines several committees' drafts and incorporates 126 changes requested by Democrats. The main concession is on ethics, with the text adopting most of the Tillis-Gallego proposal, extending conflict-of-interest restrictions on crypto dealings to the President, Vice President, members of Congress, federal judges, and their spouses, with state attorneys general given an enforcement role, while the AP reported that President Trump has agreed to the language. Banks also got something, in the form of an 18-month circuit breaker that lets the Treasury Secretary pause stablecoin rewards if payment stablecoins drive substantial deposit outflows from community banks. Polymarket's market on the bill being signed into law this year moved from 17% at the start of the week to a high of 34% overnight, settling at 29% as of writing on $16M of volume. The odds remain well below even while timing remains a key constraint. Tuesday's 2:15pm cloture vote needs 60 votes, meaning at least seven Democrats need to cross over even if all 53 Republicans vote yes, with cloture only opening the debate. Amendments, final passage, and House action on the Senate substitute would all have to fit in before the Senate's state work period begins on October 5, with the House having already canceled the weeks of September 21 and 28.
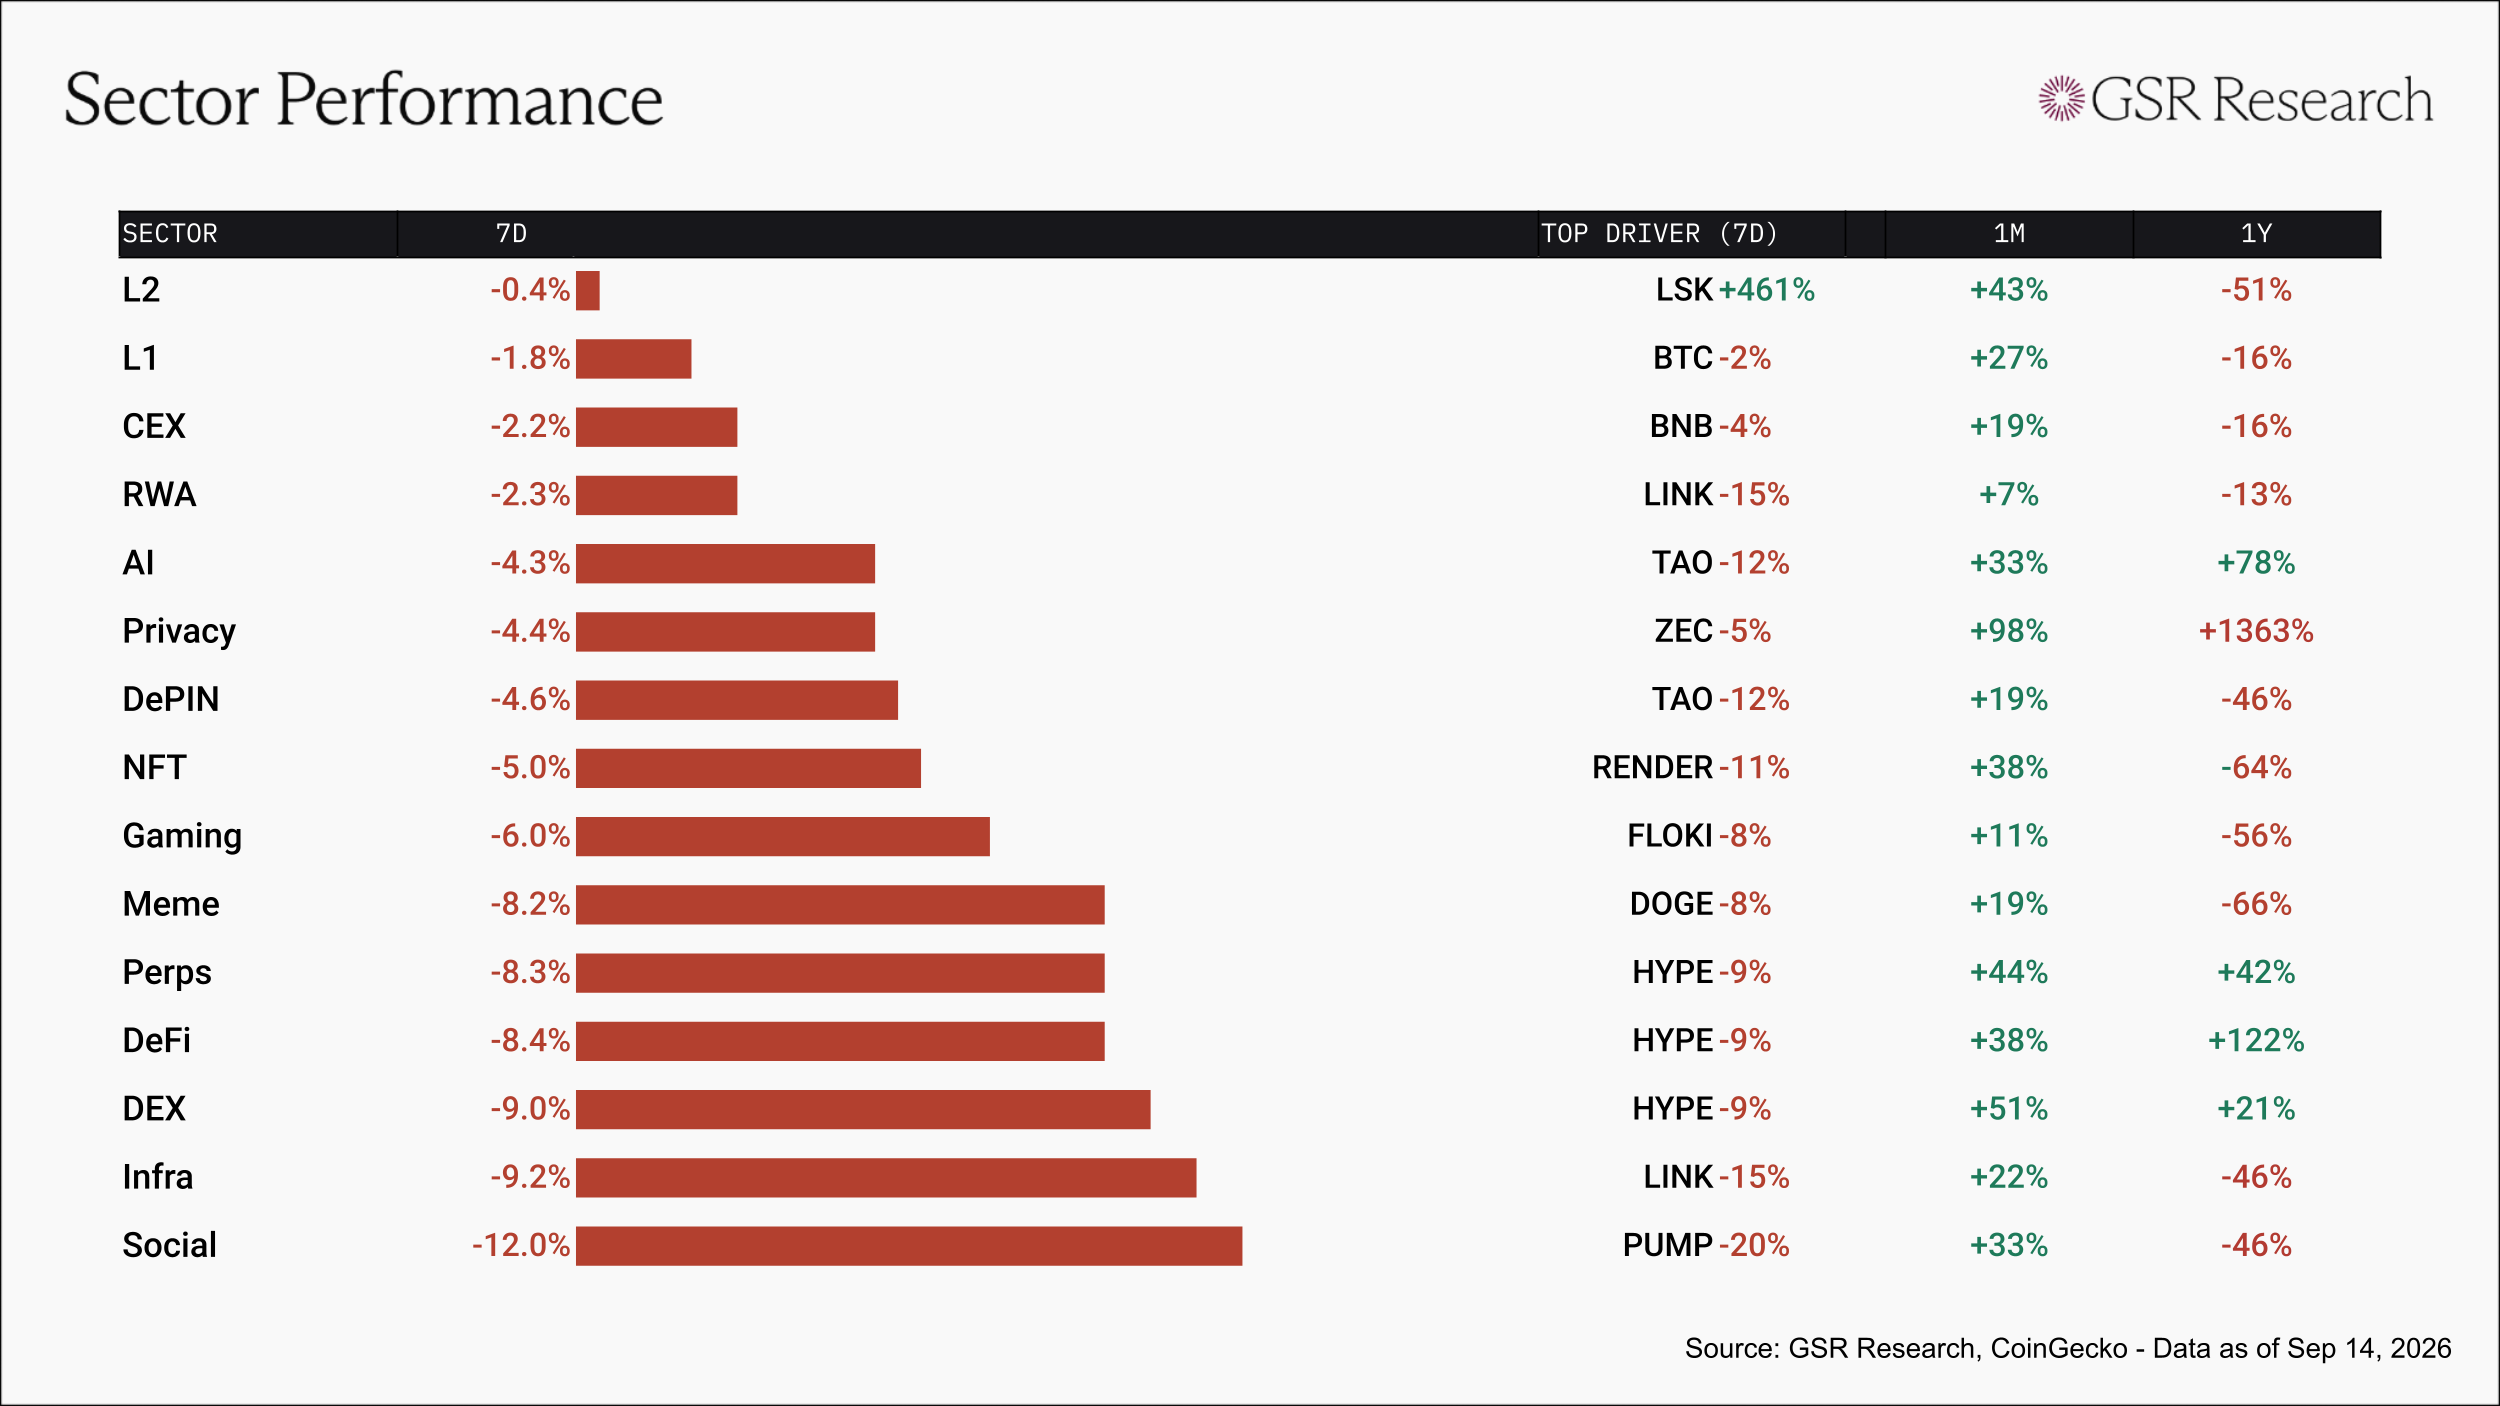
All 15 sectors closed red this week, just as all 15 closed green the week before. L2 (-0.4%) held flat only because of a short squeeze in LSK (+461%), which spiked more than 500% on Sunday after Lisk proposed burning 100M tokens, roughly 25% of max supply, as part of a plan to shut its standalone chain on October 31, while ARB (-20%) round-tripped its Robinhood Chain rally ahead of Wednesday's unlock. L1 (-1.8%) tracked BTC (-2%), CEX (-2.2%) followed BNB (-4%), and RWA (-2.3%) held up despite LINK (-15%), which gave back part of a rally from $8.30 to nearly $13.70 that followed Schwab saying it will add the token to its platform.
Social fell furthest at -12.0% as PUMP (-20%) continued to lose ground to Pons on Robinhood Chain, with its weekly burn down 15% to $3.9M. The three HYPE-driven sectors, DEX (-9.0%), DeFi (-8.4%), and Perps (-8.3%), fell together as HYPE (-9%) sold off in the week following its roughly $800M Core Contributors unlock, and Infra (-9.2%) carried LINK's decline. In the middle, TAO (-12%) dragged AI (-4.3%) and DePIN (-4.6%), and Privacy (-4.4%) gave back a portion of its run as ZEC (-5%) consolidated above $1,100, with the sector still up +98% on the month.
Data appendix. Each Market Pulse tile shows where a gauge sits in its own trailing one-year range: the bar runs from the year's low to its high, the dark marker is this week's reading, and the colored span behind it is the week's move, green when the gauge climbed its range and red when it fell. Tags mark position in that range: HIGH above the 65th percentile, LOW below the 35th, NEUTRAL between, with the tag's color carrying the read. Funding is BTC perpetual funding, OI-weighted across major venues and annualized; onchain yield is Aave v3's USDC market on Ethereum; stablecoin flows is the 7-day net change in supply of all USD-pegged stablecoins across all chains per DeFiLlama; open interest sums futures in the twelve largest futures assets (roughly 95% of all crypto futures OI) against total crypto market cap; ETF flows combines US spot Bitcoin and Ethereum funds on a rolling 7 days; and altcoins is the share of the top 100, excluding stablecoins and wrappers, beating BTC over 7 days. Sector returns are cap-weighted CoinGecko categories, top ten constituents each. Sources: GSR Research, Glassnode, Deribit, CoinGecko, DeFiLlama, FRED, Tokenomist.
This material is provided by GSR (the “Firm”) solely for informational purposes. It is not intended to be advice or a recommendation to buy, sell or hold any investment mentioned. Investors should form their own views in relation to any proposed investment.
It is intended only for sophisticated, institutional investors and does not constitute an offer or commitment, a solicitation of an offer or commitment, or any advice or recommendation, to enter into or conclude any transaction (whether on the terms shown or otherwise), or to provide investment services in any state or country where such an offer or solicitation or provision would be illegal. The Firm is not and does not act as an advisor or fiduciary in providing this material.
This material is not an independent research report, and has not been prepared in accordance with any legal requirements by any regulator (including the FCA, FINRA or CFTC) designed to promote the independence of investment research.
This material is not independent of the Firm’s proprietary interests, which may conflict with the interests of any counterparty of the Firm. The Firm may trade investments discussed in this material for its own account, may trade contrary to the views expressed in this material, and may have positions in other related instruments. The Firm is not subject to any prohibition on dealing ahead of the dissemination of this material.
Information contained herein is based on sources considered to be reliable, but is not guaranteed to be accurate or complete. Any opinions or estimates expressed herein reflect a judgment made by the author(s) as of the date of publication, and are subject to change without notice. The Firm does not plan to update this information.
Trading and investing in digital assets involves significant risks including price volatility and illiquidity and may not be suitable for all investors. The Firm is not liable whatsoever for any direct or consequential loss arising from the use of this material. Copyright of this material belongs to GSR. Neither this material nor any copy thereof may be taken, reproduced or redistributed, directly or indirectly, without prior written permission of GSR.
Please see here for additional Regulatory Legal Notices relevant to US, UK and Singapore.