Share:

Overview
- BTC rose ~10% to $86k, its highest level since January, after bottoming near $75k on Wednesday's Fed decision, with ETH up a similar amount and the alt basket ~15% higher as all 15 sectors closed green.
- CLARITY's cloture vote failed 49-50 on Tuesday with all seven negotiating Democrats voting no, and the Fed hiked 25bp from 3.75-4.00% on Wednesday, its first increase since July 2023.
- On Thursday the SEC issued a five-year Innovation Exemption allowing tokenized U.S. stocks to trade on permissioned AMMs, and the CFTC sent its crypto market-structure rulemaking to the White House for review.
- Funding (+7.5%) and open interest (2.7%) returned to one-year highs while ETF flows (-$0.4B) were negative for a second week despite Friday's $433M inflow, the largest single day since August 2025.
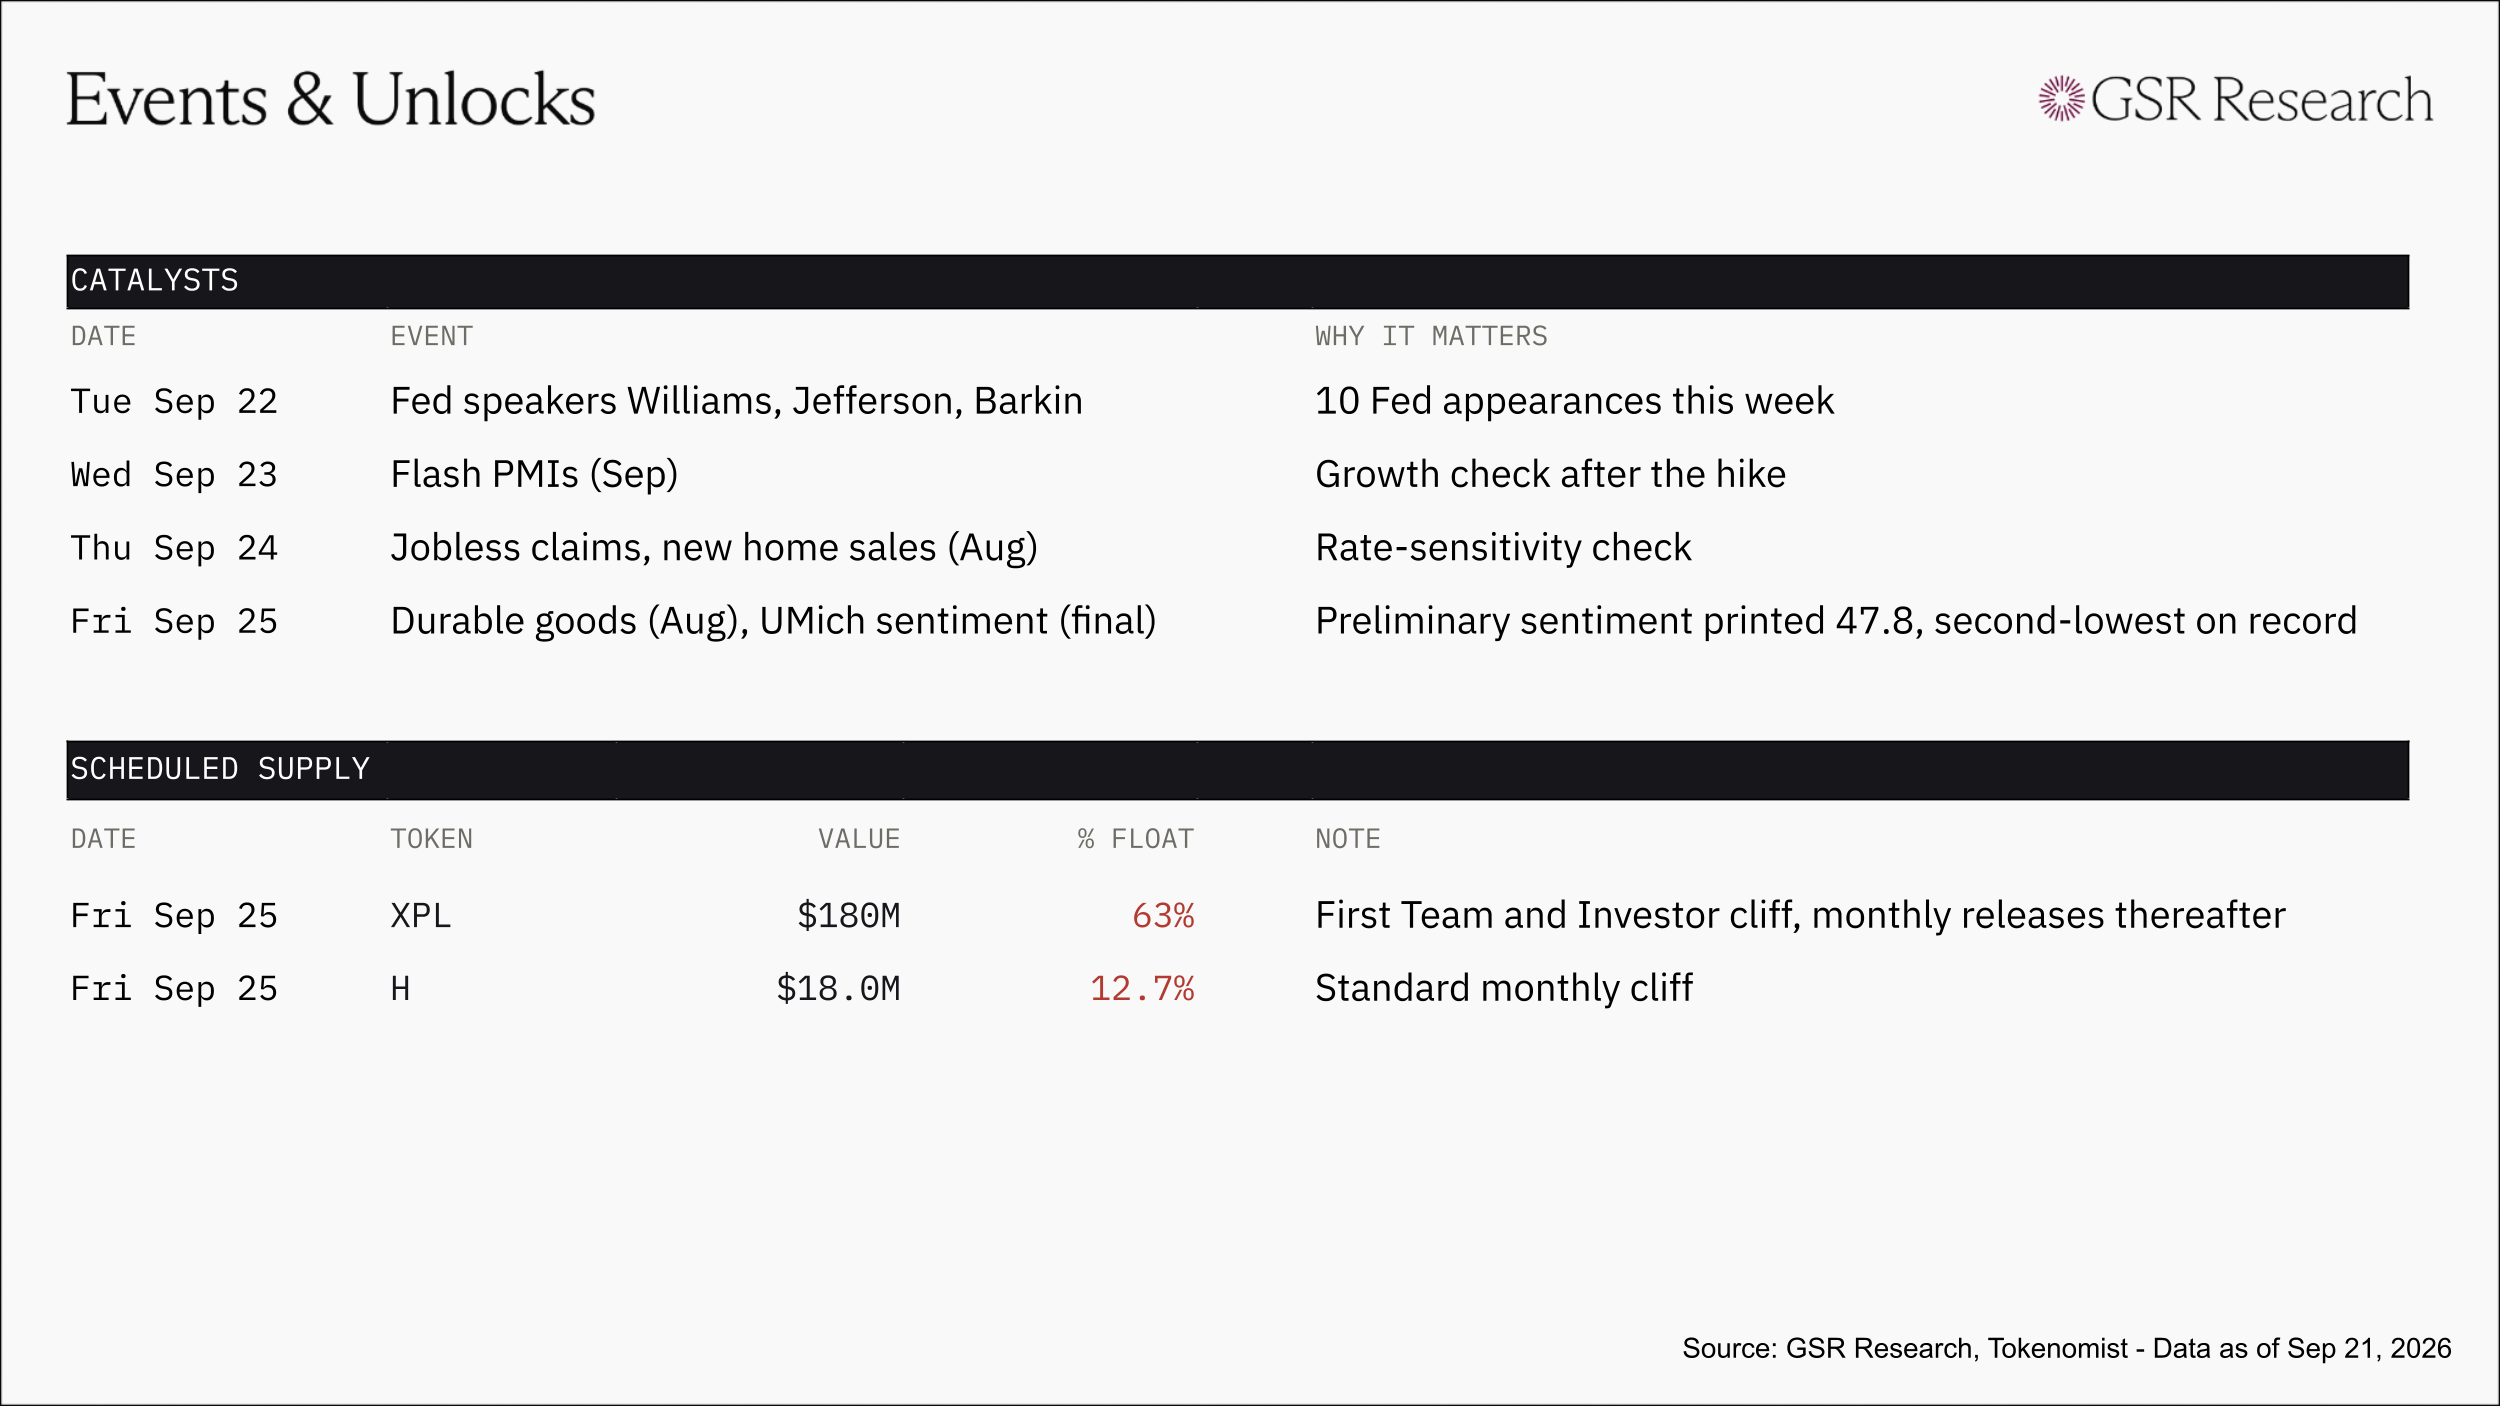
- All eyes are on a light data week with 10 Fed appearances, Friday's durable goods and final consumer sentiment prints, and XPL's $180M unlock on Friday.
The Week in Review
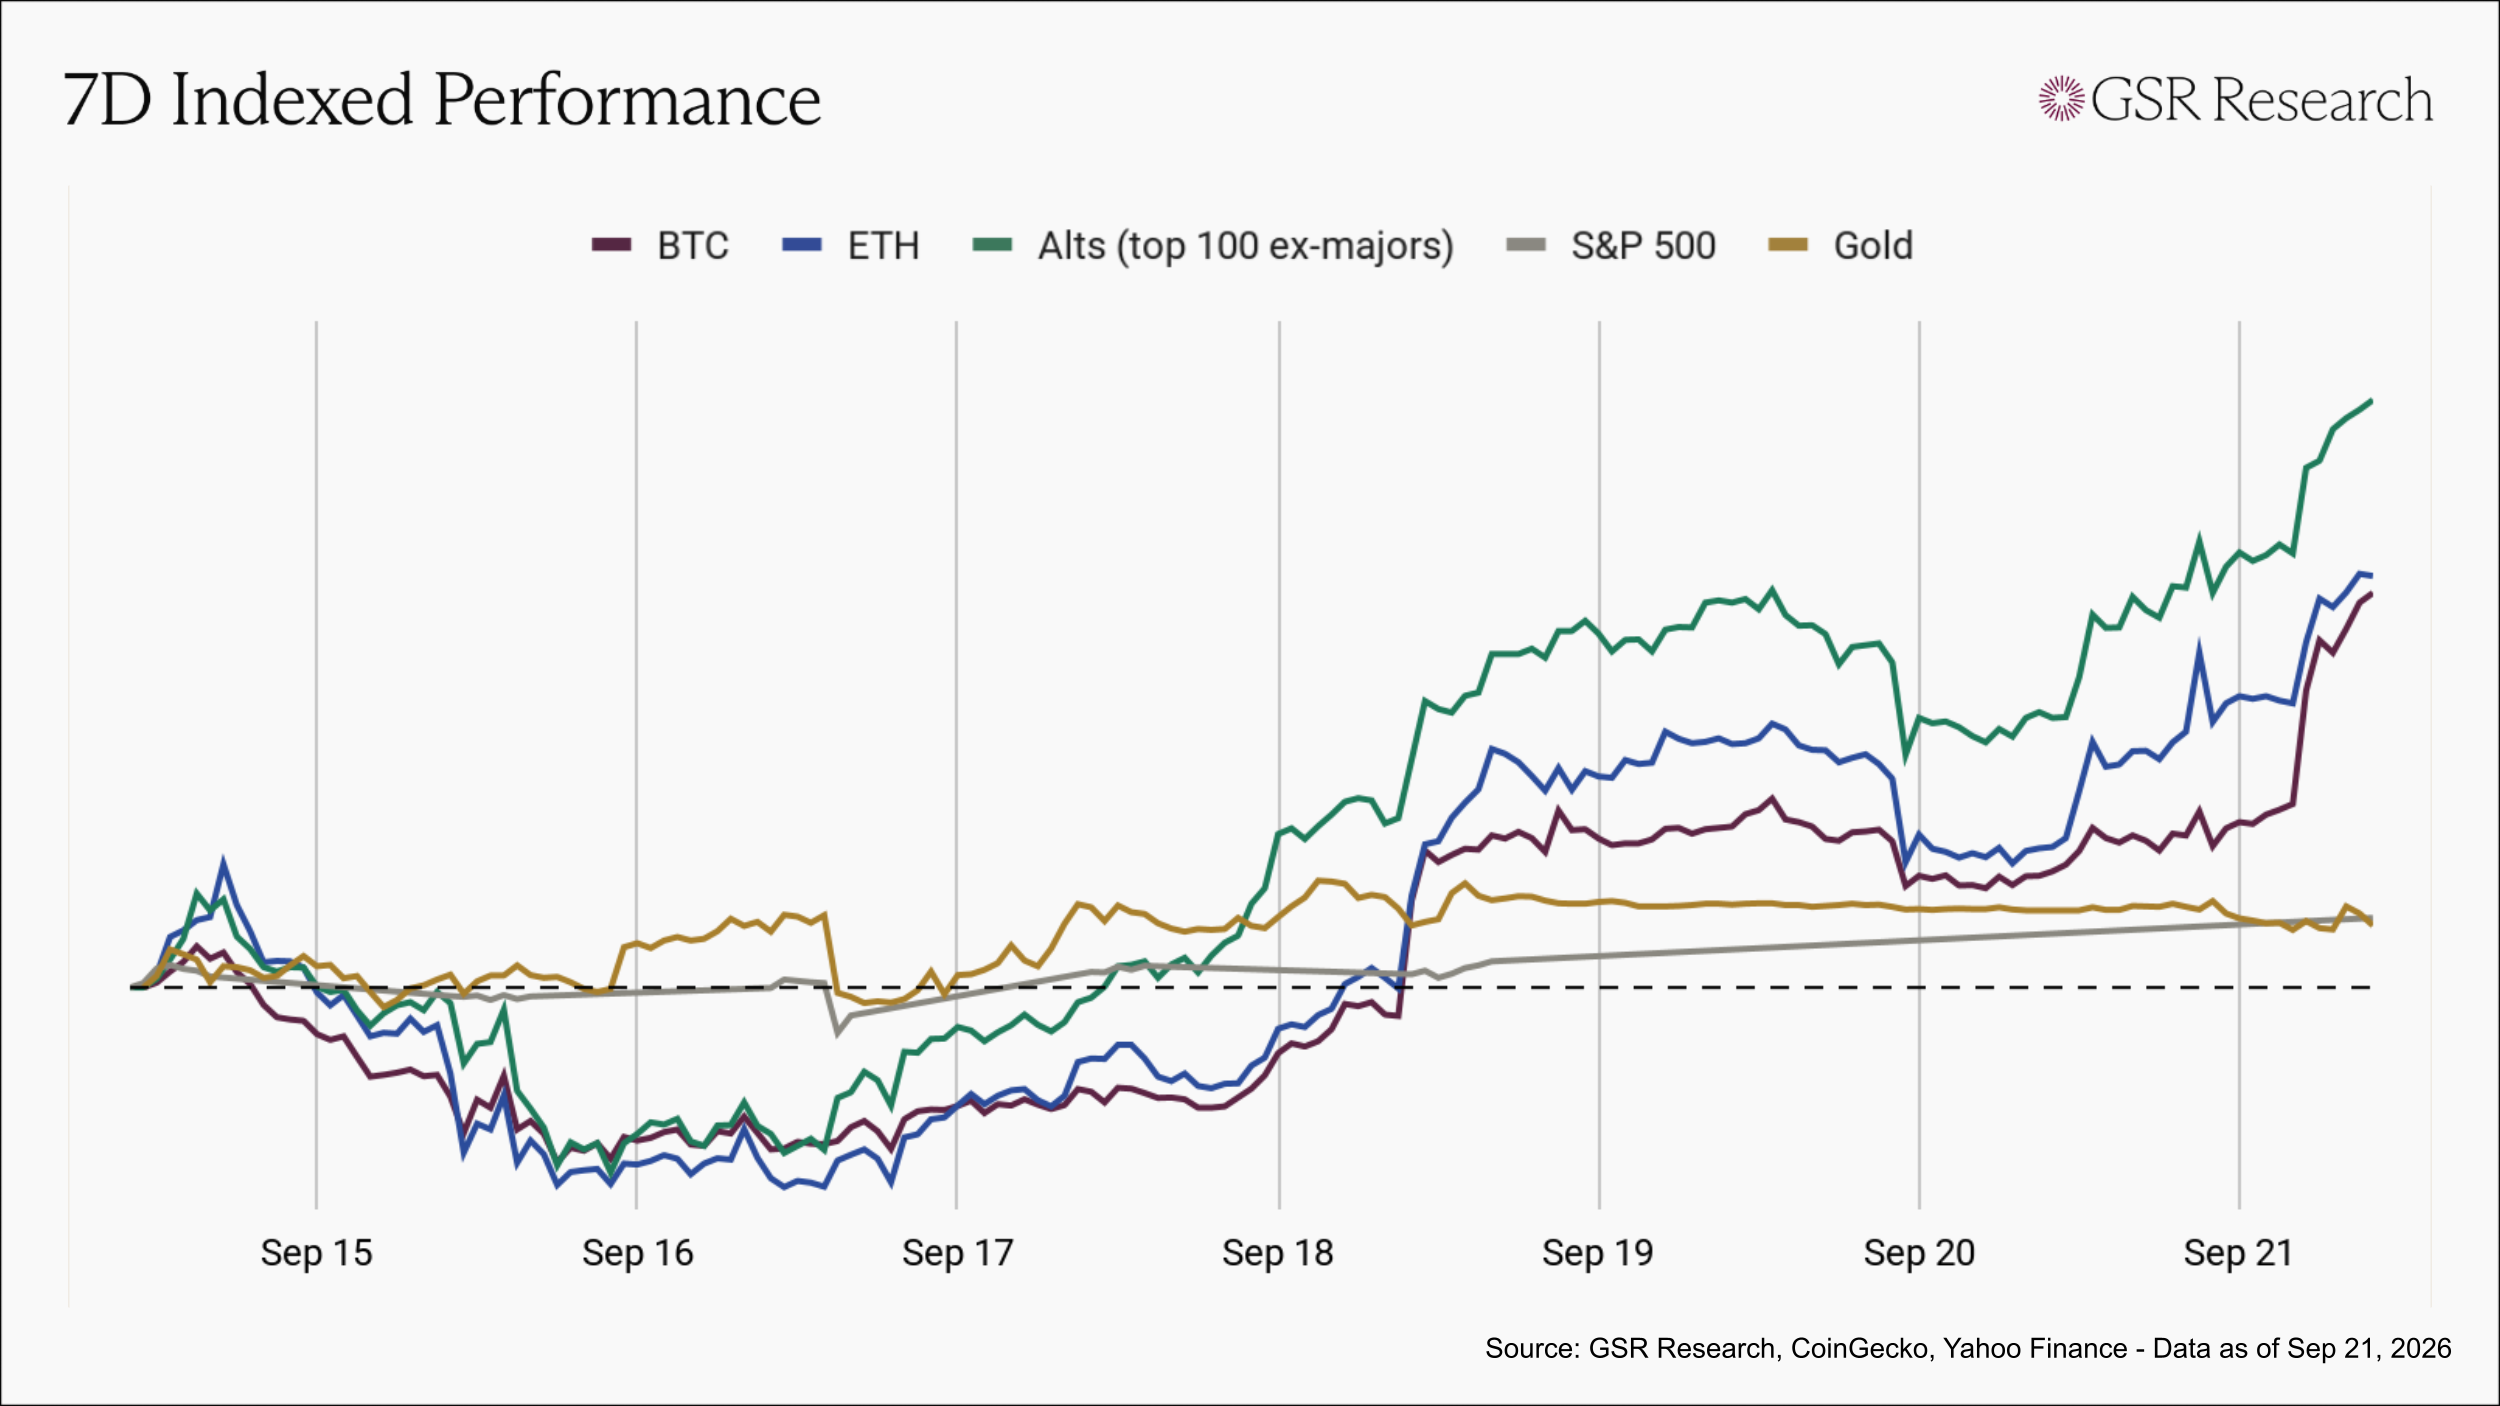
Tuesday's CLARITY cloture vote failed 49-50, short of the 60 needed, with Polymarket odds of the bill being signed this year fell from 29% to 7% within a day. The Fed followed on Wednesday with a unanimous 25bp hike to 3.75-4.00%, its first since July 2023, with 16 of 18 officials projecting at least one more hike this year and Warsh saying he would be "hard-pressed to describe broad financial conditions as restrictive". With CME FedWatch pricing a 92% chance of the move going in, BTC traded in a $75,000 to $76,500 range through the decision and press conference while the Dow fell 1.2% and the 10-year moved back above 5%. The turn came Thursday, when the SEC issued its five-year Innovation Exemption for tokenized stock venues and the CFTC sent its crypto market-structure rulemaking to the White House, followed on Friday by $433M of inflows into spot Bitcoin ETFs. BTC finished up ~10% at $86k, ETH ~10% higher, the alt basket up ~15%, and gold and the S&P each ~1.5% higher.
Market Pulse
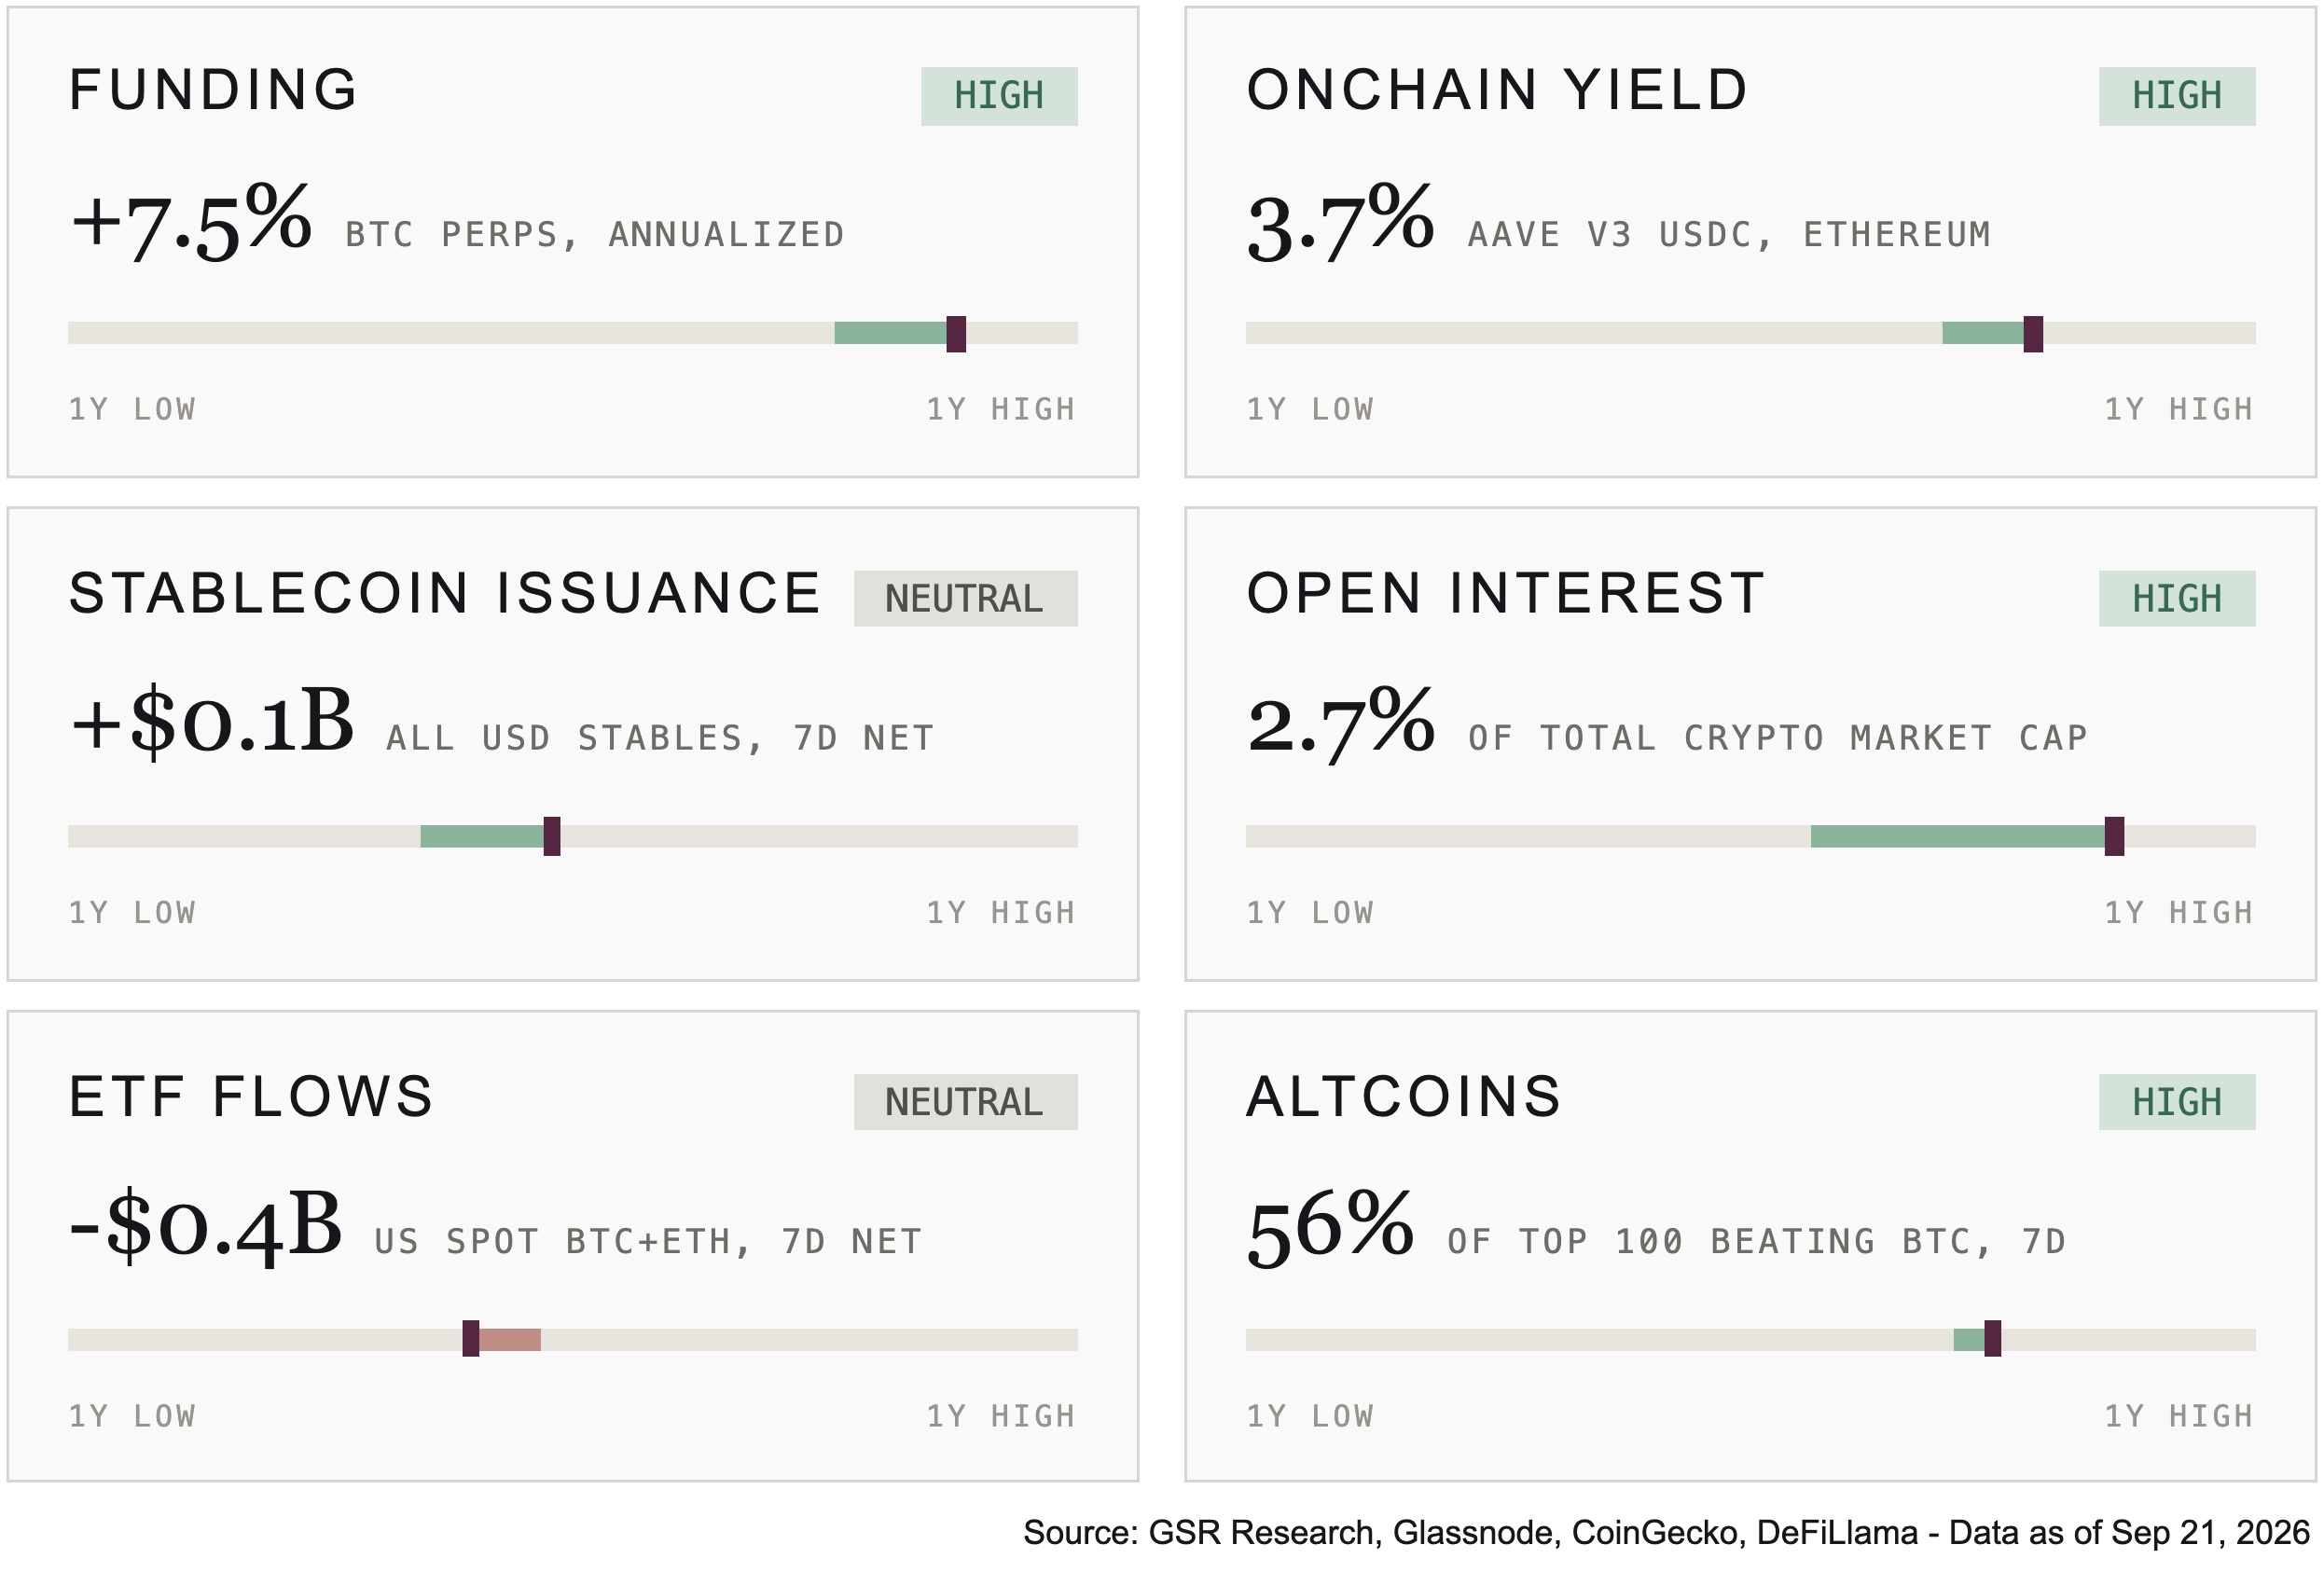
Funding rose from +6.4% to +7.5% annualized and open interest ticked up from 2.6% to 2.7% of total market cap, both back near one-year highs. ETF flows were negative for a second week at -$0.4B despite Friday's $433M inflow into Bitcoin funds, as ETH funds snapped a four-week inflow streak, and stablecoin issuance recovered from -$0.4B to +$0.1B. Onchain yield edged up from 3.6% to 3.7%. Altcoin performance held at 56 of the top 100 beating Bitcoin, up only 1 from the week prior. The rally ran on leverage and short covering, with ETF and stablecoin flows roughly flat on the week.
Chart of the Week: Market Shrugs Off CLARITY Stall and Fed Hike
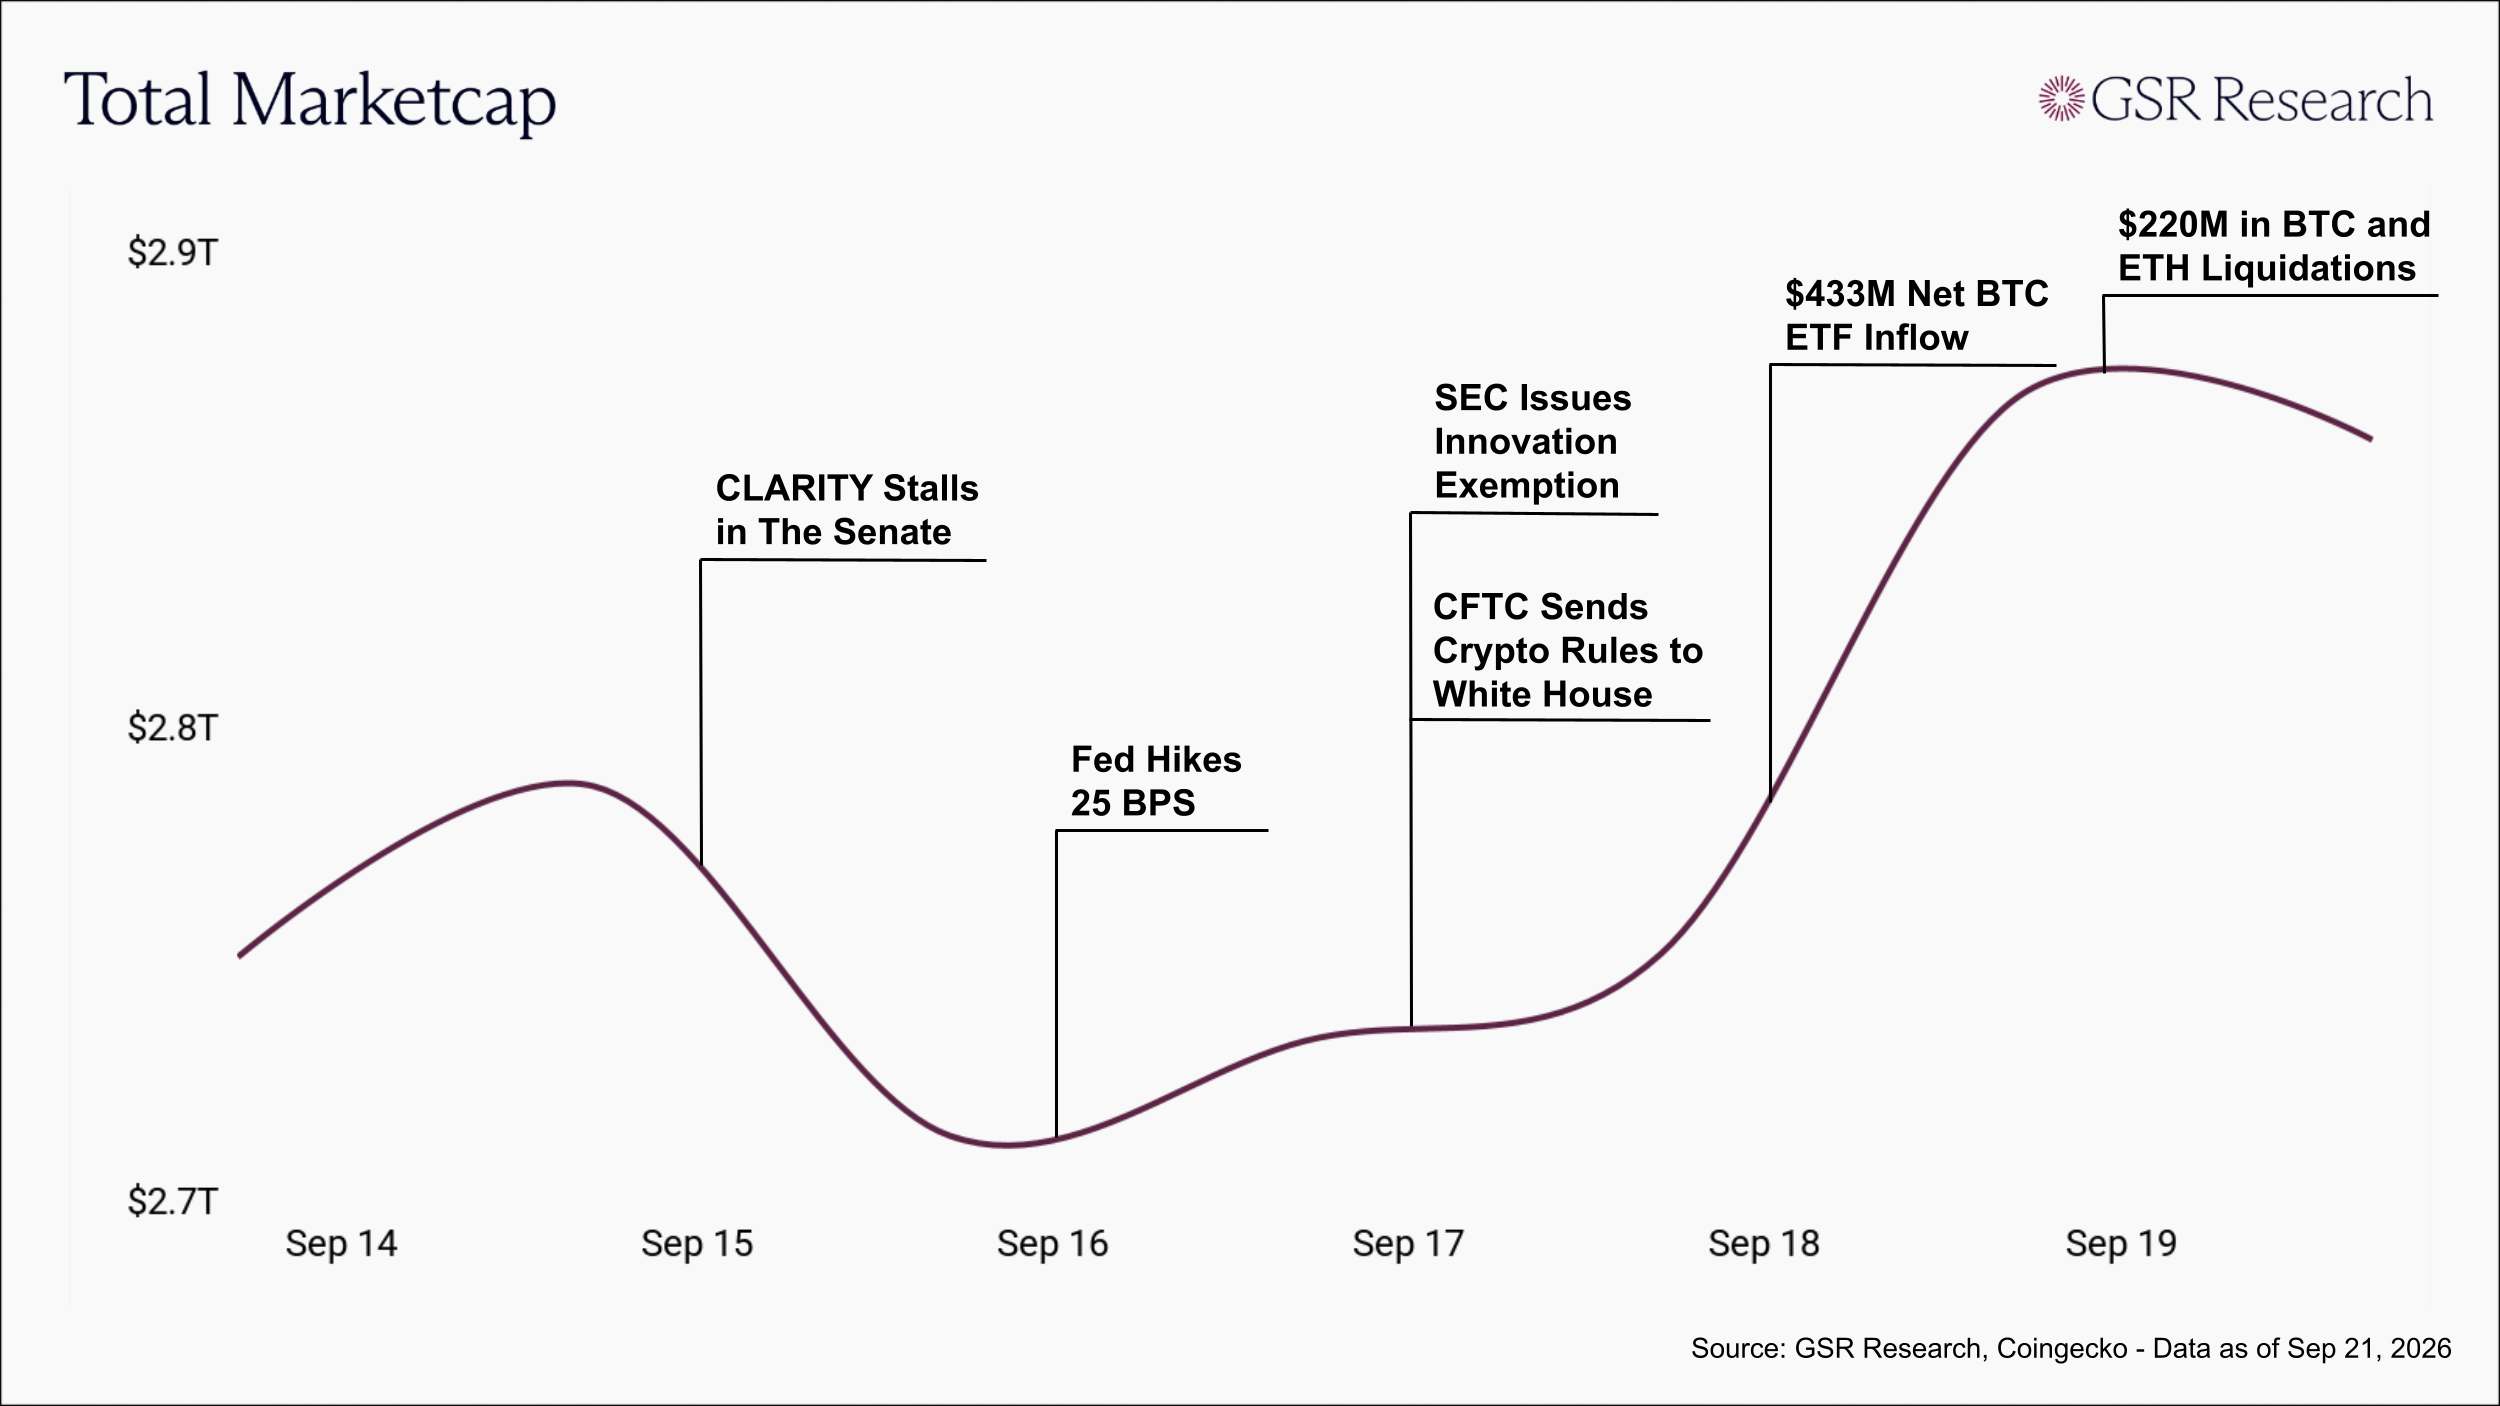
Total crypto market cap ended the week roughly 6% higher at $2.9T after absorbing two headlines that would have read as clearly negative a month ago. However, neither event carried much surprise. Polymarket had the bill at 29% going into the vote and Lummis had said the week before that failing cloture would push passage out to 2030, so the 49-50 result largely confirmed what was already priced in. Similarly, the hike had sat above 90% on CME FedWatch since the CPI print, with the only real risk going into the meeting arguably being a larger move or a dot plot signaling a longer sequence. What arrived was one hike, a projection of one more, and a median projected rate path sitting at 4.1% through 2027, which the market read as relief. Additionally, the negative headlines were offset by positive news, as two days after Congress stalled, both market regulators moved to build the framework by rule. The SEC's five-year Innovation Exemption created a Tokenized Securities Venue category permitted to trade tokenized NMS stocks through permissioned AMMs, while the CFTC sent its Regulation of Crypto Asset Transactions and Crypto Asset Markets rulemaking to the White House for review, and issued no-action relief for passive software developers the same day. With the Fed hike and the CLARITY stall already priced in, the market rallied on the unexpected positive news, with $220M in combined BTC and ETH liquidations driving a short squeeze up to $2.9T.
Sector Breakdown
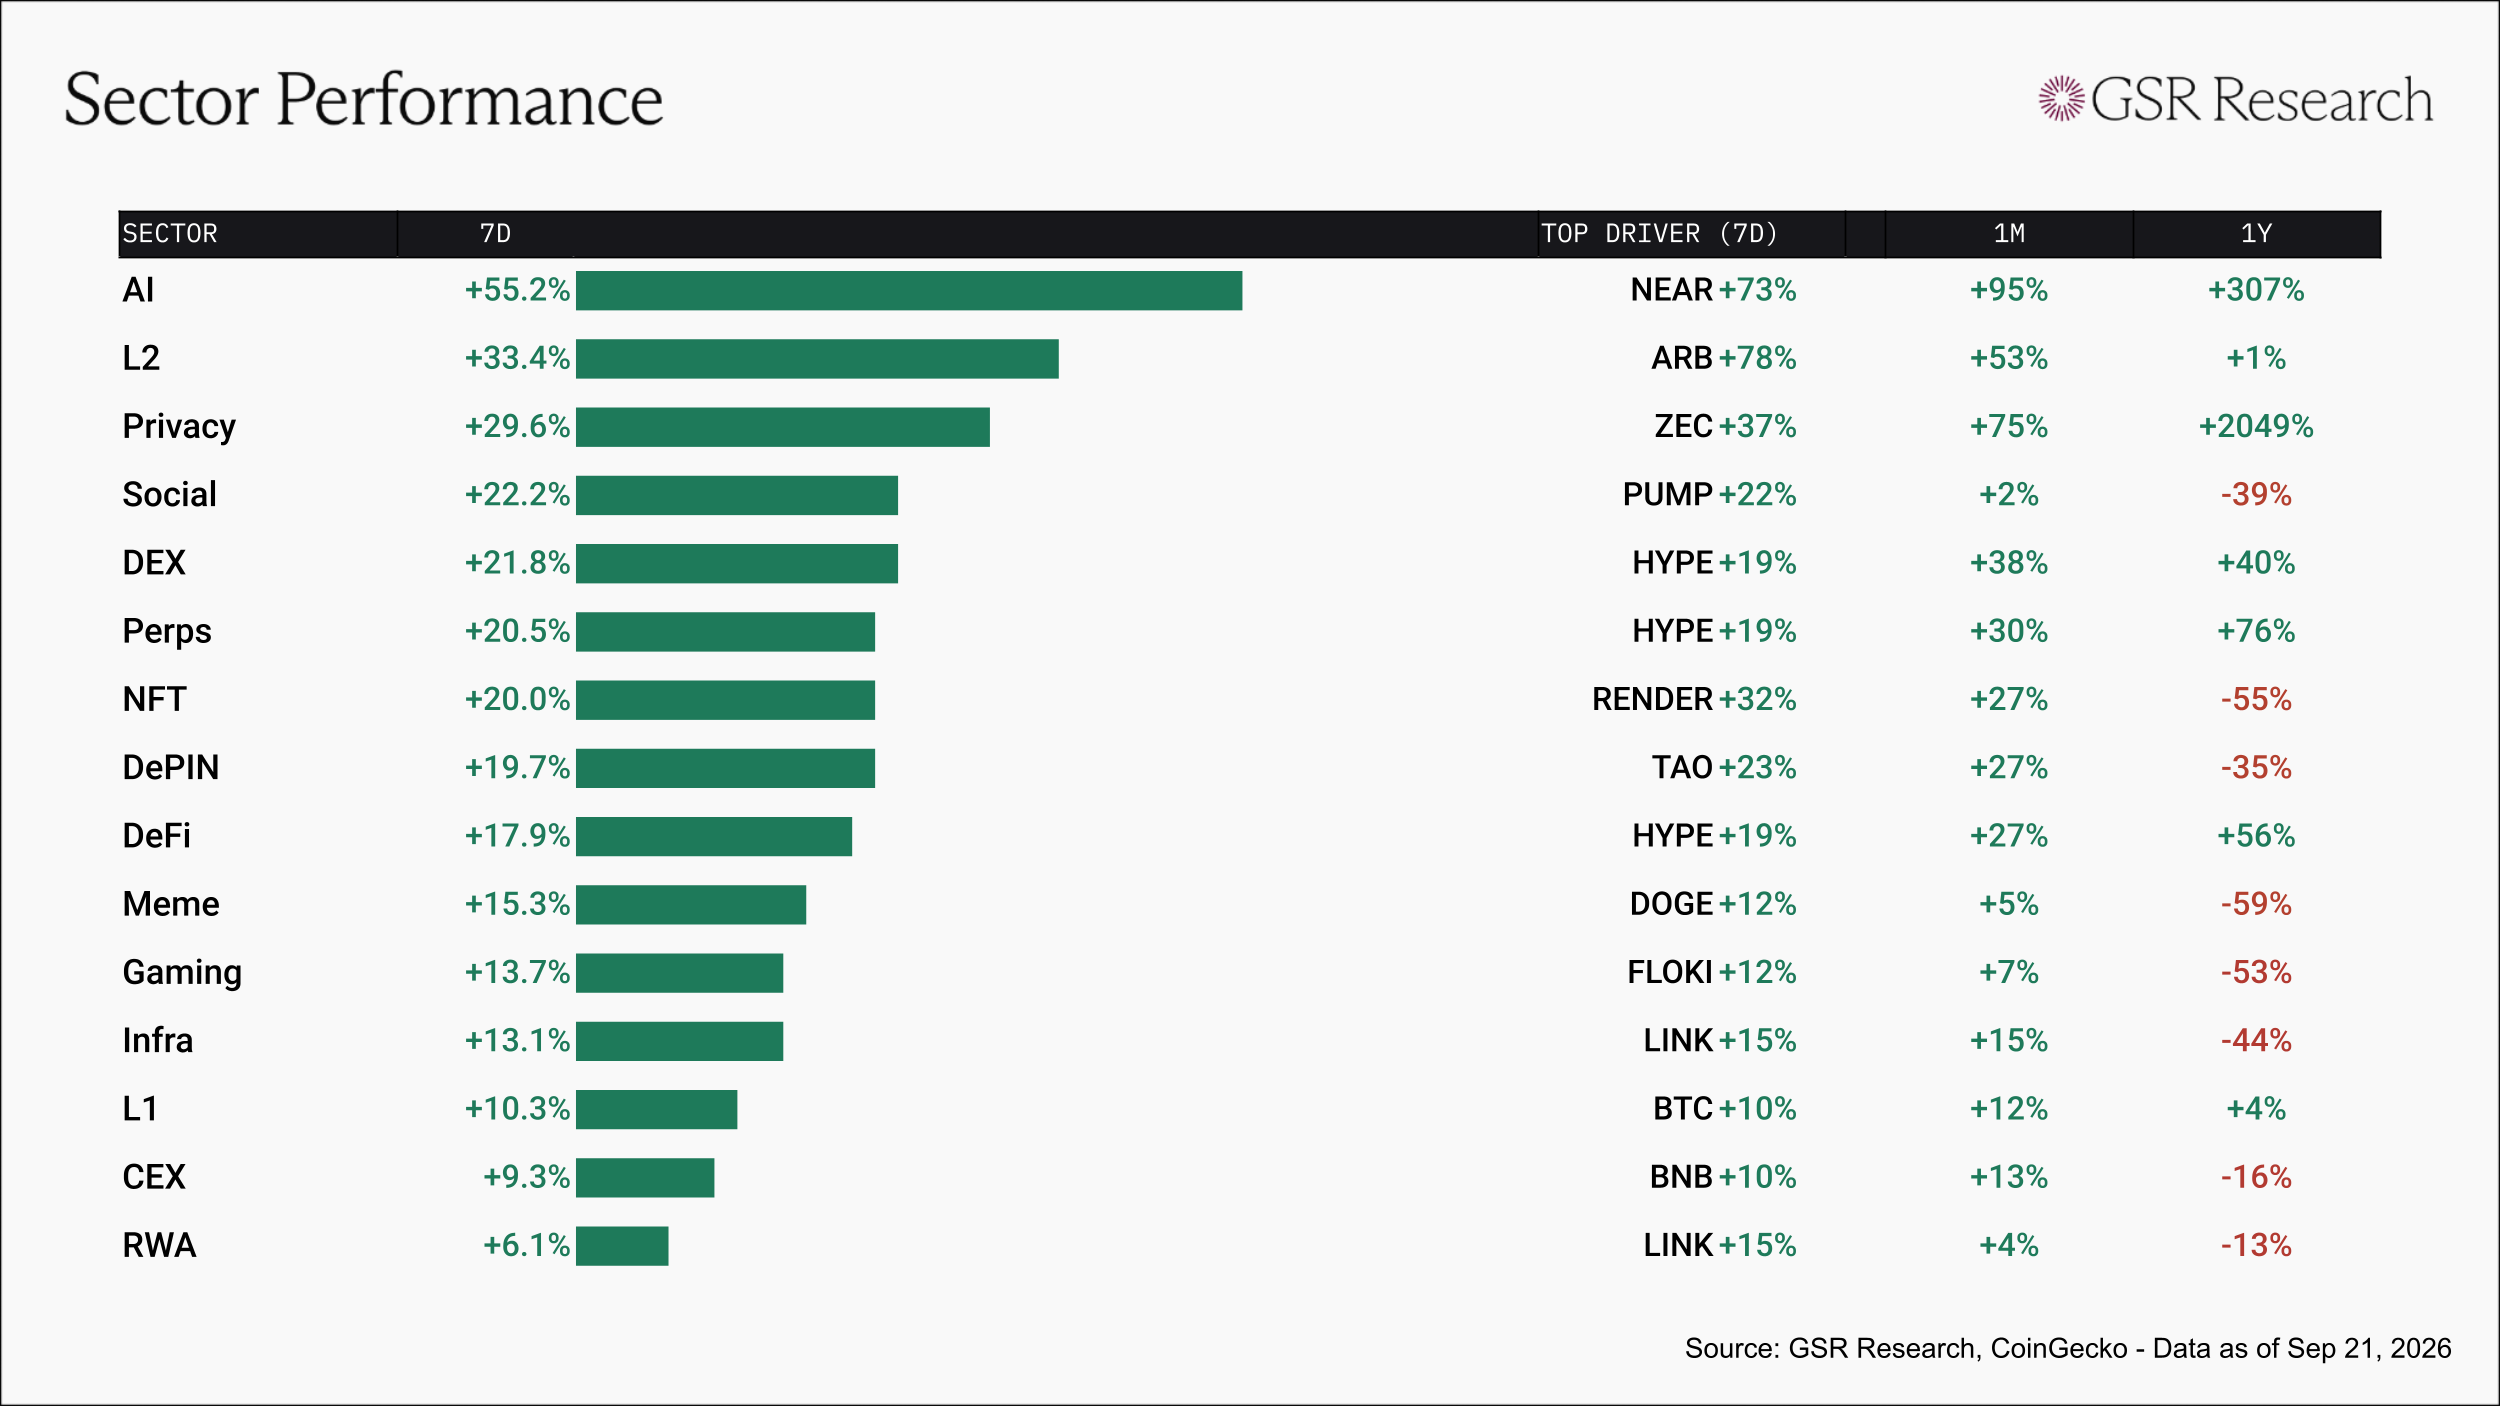
All 15 sectors closed green this week, and 13 of them by double digits. AI led at +55.2% on NEAR (+73%), which climbed above $4.00 as Near Intents set a record above $300M in daily volume on Friday and the network launched confidential perpetuals built on Hyperliquid, leaving the sector up +95% on the month and +307% on the year. L2 rose +33.4% on ARB (+78%), which rallied straight through Wednesday's 92.6M token unlock on Robinhood Chain's revenue share and a Standard Chartered initiation with a $10 target for 2030. Privacy added +29.6% as ZEC (+37%) pushed to $1,500, taking the sector to +2,049% over twelve months, and Social (+22.2%) rebounded on PUMP (+22%) after three weeks of declines.
DEX (+21.8%), Perps (+20.5%), and DeFi (+17.9%) moved together on HYPE (+19%), which recovered its post-unlock losses, while UNI (+39%) jumped roughly 30% after the SEC's exemption specifically permitted tokenized stock trading through permissioned AMMs, a structure Uniswap v4 already supports. RENDER (+32%) and TAO (+23%) carried NFT (+20.0%) and DePIN (+19.7%). Most of the rest of the board rose 9-15%, with Meme (+15.3%), Gaming (+13.7%), and Infra (+13.1%) in the middle, L1 (+10.3%) tracking BTC (+10%), and RWA (+6.1%) at the bottom despite LINK (+15%).
Data appendix. Each Market Pulse tile shows where a gauge sits in its own trailing one-year range: the bar runs from the year's low to its high, the dark marker is this week's reading, and the colored span behind it is the week's move, green when the gauge climbed its range and red when it fell. Tags mark position in that range: HIGH above the 65th percentile, LOW below the 35th, NEUTRAL between, with the tag's color carrying the read. Funding is BTC perpetual funding, OI-weighted across major venues and annualized; onchain yield is Aave v3's USDC market on Ethereum; stablecoin flows is the 7-day net change in supply of all USD-pegged stablecoins across all chains per DeFiLlama; open interest sums futures in the twelve largest futures assets (roughly 95% of all crypto futures OI) against total crypto market cap; ETF flows combines US spot Bitcoin and Ethereum funds on a rolling 7 days; and altcoins is the share of the top 100, excluding stablecoins and wrappers, beating BTC over 7 days. Sector returns are cap-weighted CoinGecko categories, top ten constituents each. Sources: GSR Research, Glassnode, Deribit, CoinGecko, DeFiLlama, FRED, Tokenomist.
This material is provided by GSR (the “Firm”) solely for informational purposes. It is not intended to be advice or a recommendation to buy, sell or hold any investment mentioned. Investors should form their own views in relation to any proposed investment.
It is intended only for sophisticated, institutional investors and does not constitute an offer or commitment, a solicitation of an offer or commitment, or any advice or recommendation, to enter into or conclude any transaction (whether on the terms shown or otherwise), or to provide investment services in any state or country where such an offer or solicitation or provision would be illegal. The Firm is not and does not act as an advisor or fiduciary in providing this material.
This material is not an independent research report, and has not been prepared in accordance with any legal requirements by any regulator (including the FCA, FINRA or CFTC) designed to promote the independence of investment research.
This material is not independent of the Firm’s proprietary interests, which may conflict with the interests of any counterparty of the Firm. The Firm may trade investments discussed in this material for its own account, may trade contrary to the views expressed in this material, and may have positions in other related instruments. The Firm is not subject to any prohibition on dealing ahead of the dissemination of this material.
Information contained herein is based on sources considered to be reliable, but is not guaranteed to be accurate or complete. Any opinions or estimates expressed herein reflect a judgment made by the author(s) as of the date of publication, and are subject to change without notice. The Firm does not plan to update this information.
Trading and investing in digital assets involves significant risks including price volatility and illiquidity and may not be suitable for all investors. The Firm is not liable whatsoever for any direct or consequential loss arising from the use of this material. Copyright of this material belongs to GSR. Neither this material nor any copy thereof may be taken, reproduced or redistributed, directly or indirectly, without prior written permission of GSR.
Please see here for additional Regulatory Legal Notices relevant to US, UK and Singapore.