GSR Weekly - Oct 19, 2026
Carlos Guzman
Research Analyst
Slater Santer
Research Analyst

Carlos Guzman
Research Analyst
Slater Santer
Research Analyst
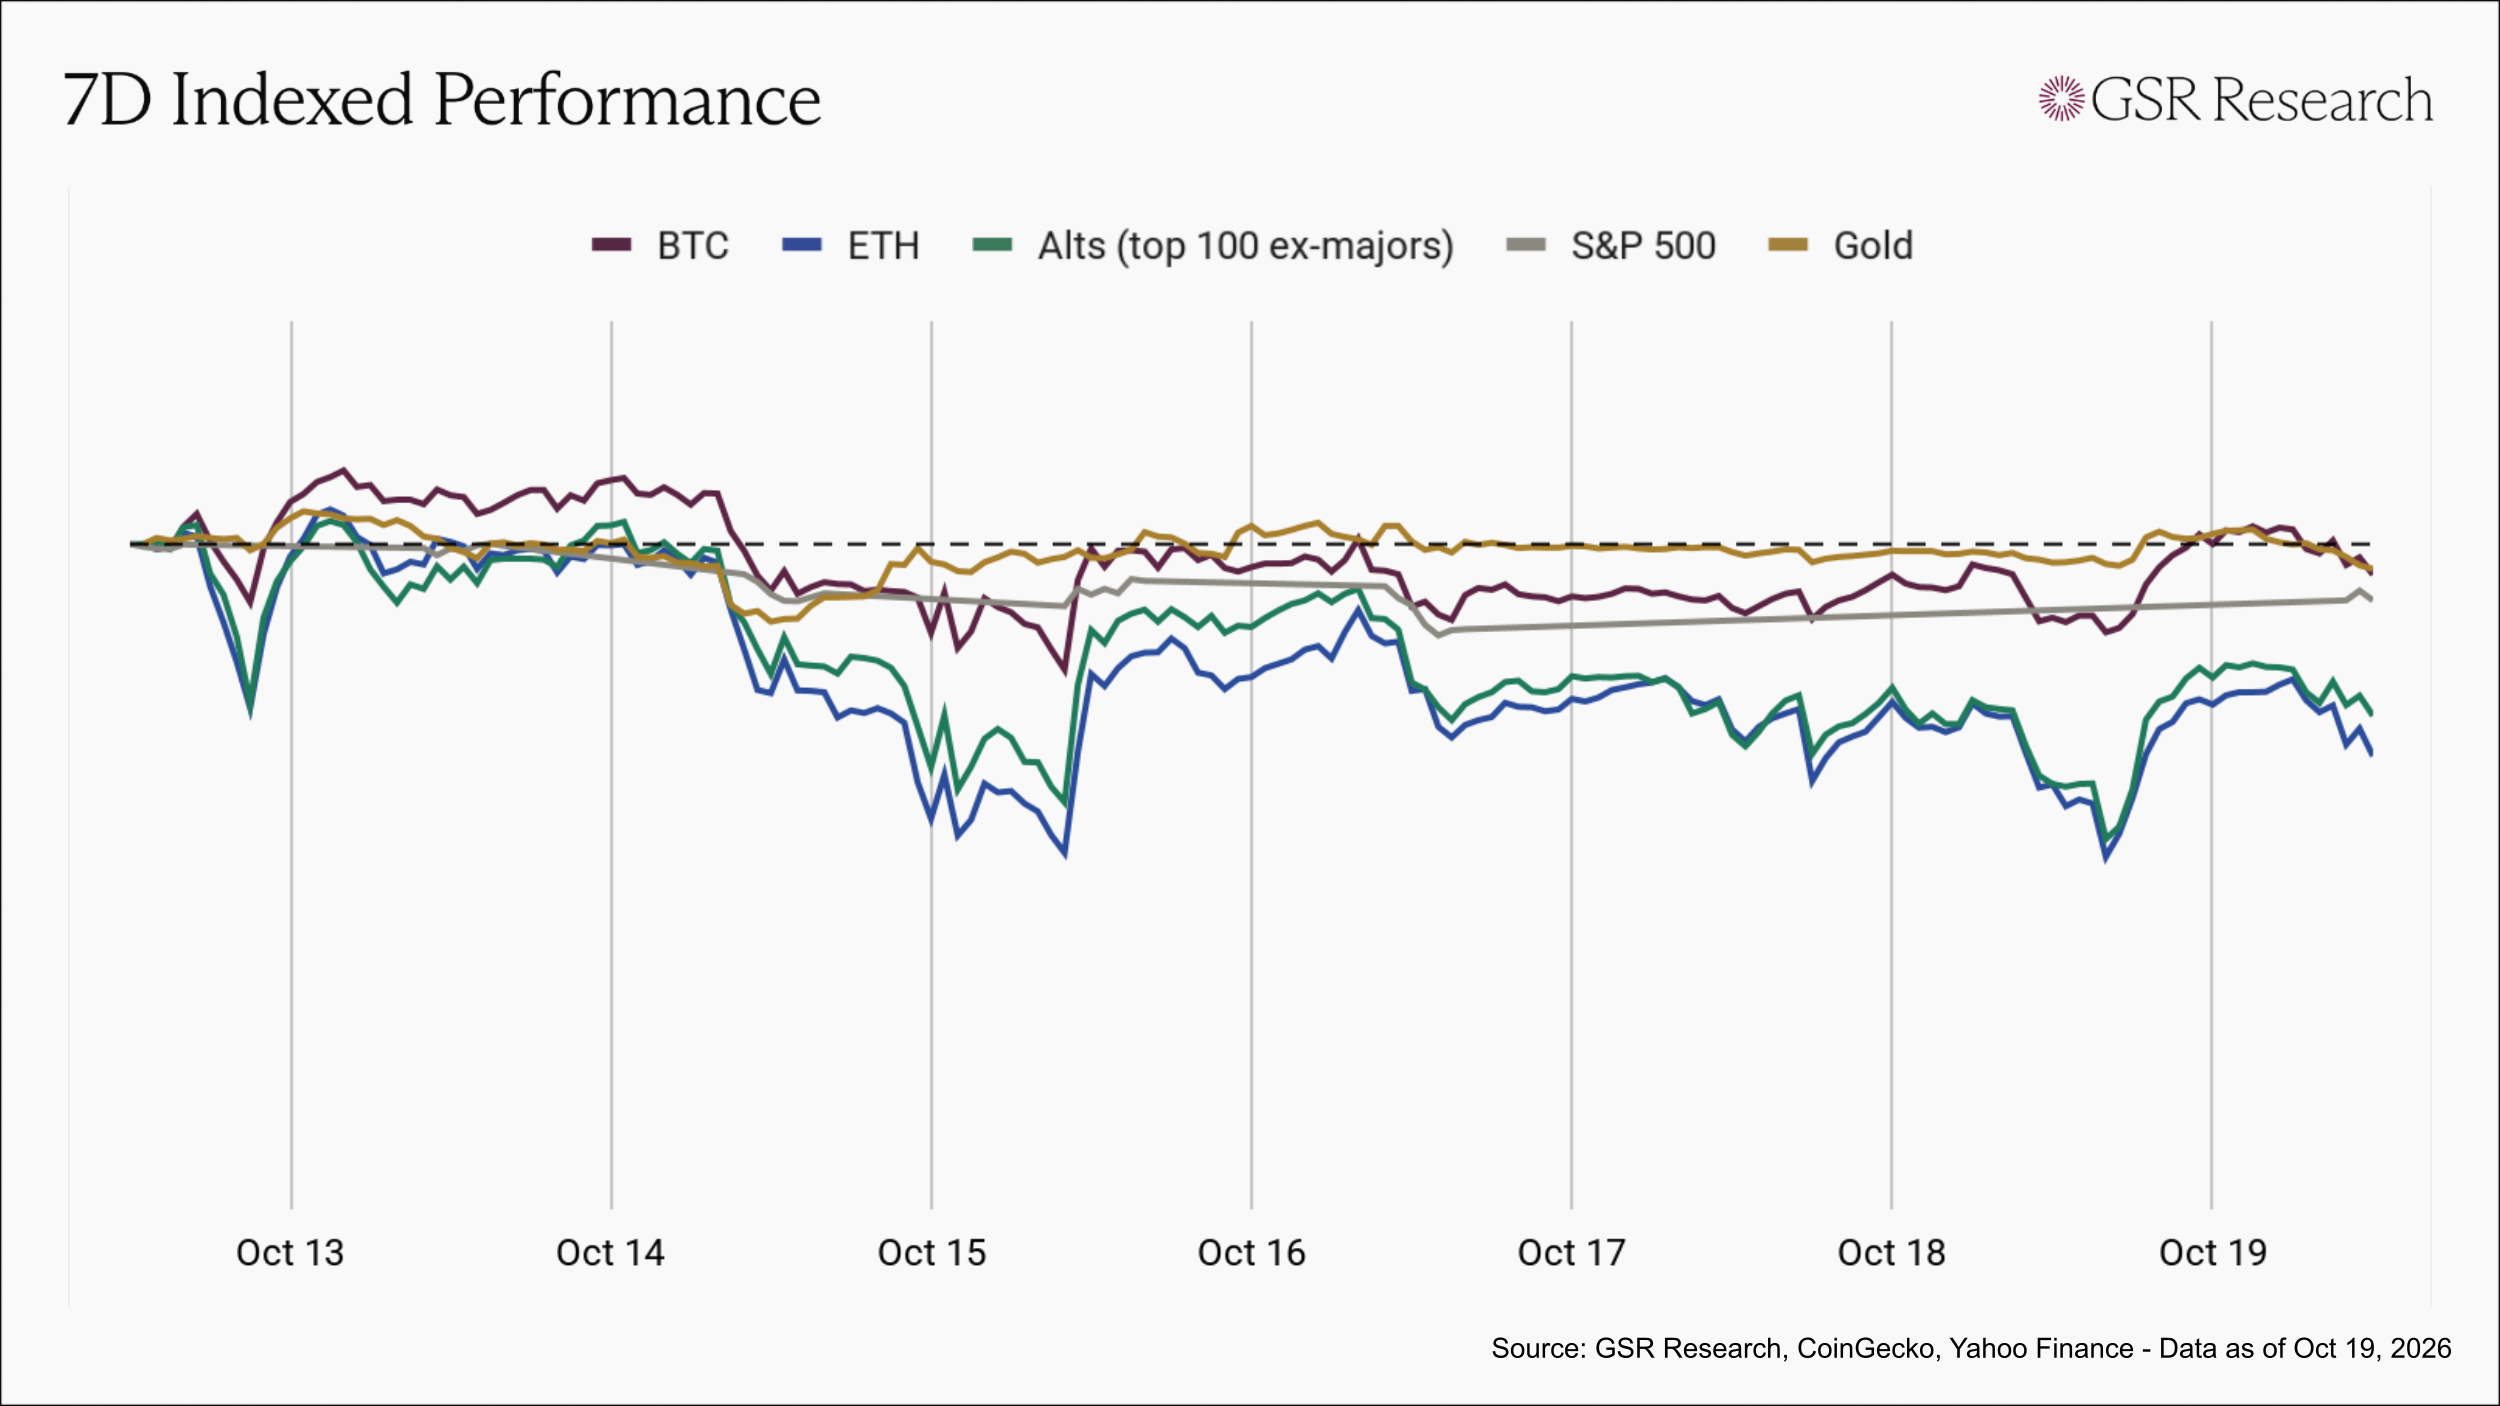
Wednesday's September CPI rose 0.6% on the month and 3.7% year-over-year, above the 3.6% consensus, with gasoline up 9.1% on the month and core rising to 2.6% from 2.4% against a 2.5% forecast. CME FedWatch odds of a hike at the October 27-28 meeting jumped from 22% before the release to roughly half that morning before settling near 32% by the evening, while spot Bitcoin ETFs posted a $261M outflow and BTC ended the day near $81,900. Thursday's data ran hotter still, as September PPI rose 1.3% on the month, more than double consensus, and 6.3% year-over-year, its highest since December 2022, with core PPI up 0.7% against 0.3% expected. Retail sales rose 0.8%, though only 0.2% excluding gas stations. BTC broke below the $80,400 low it had held twice the previous week, falling to about $79,800 and spending roughly two hours below $80,000 before recovering toward $82,500. Hike odds fell on Friday after Fed Chair Warsh, speaking at the IMF-World Bank meetings in Bangkok, declined to signal another rate increase and insisted he won’t 'prejudge meetings,' pushing October hike probabilities from roughly 27% to below 15%. BTC finished down ~1% at $82k, ETH ~5% lower, the alt basket down ~4%, and gold and the S&P each ~1% lower.
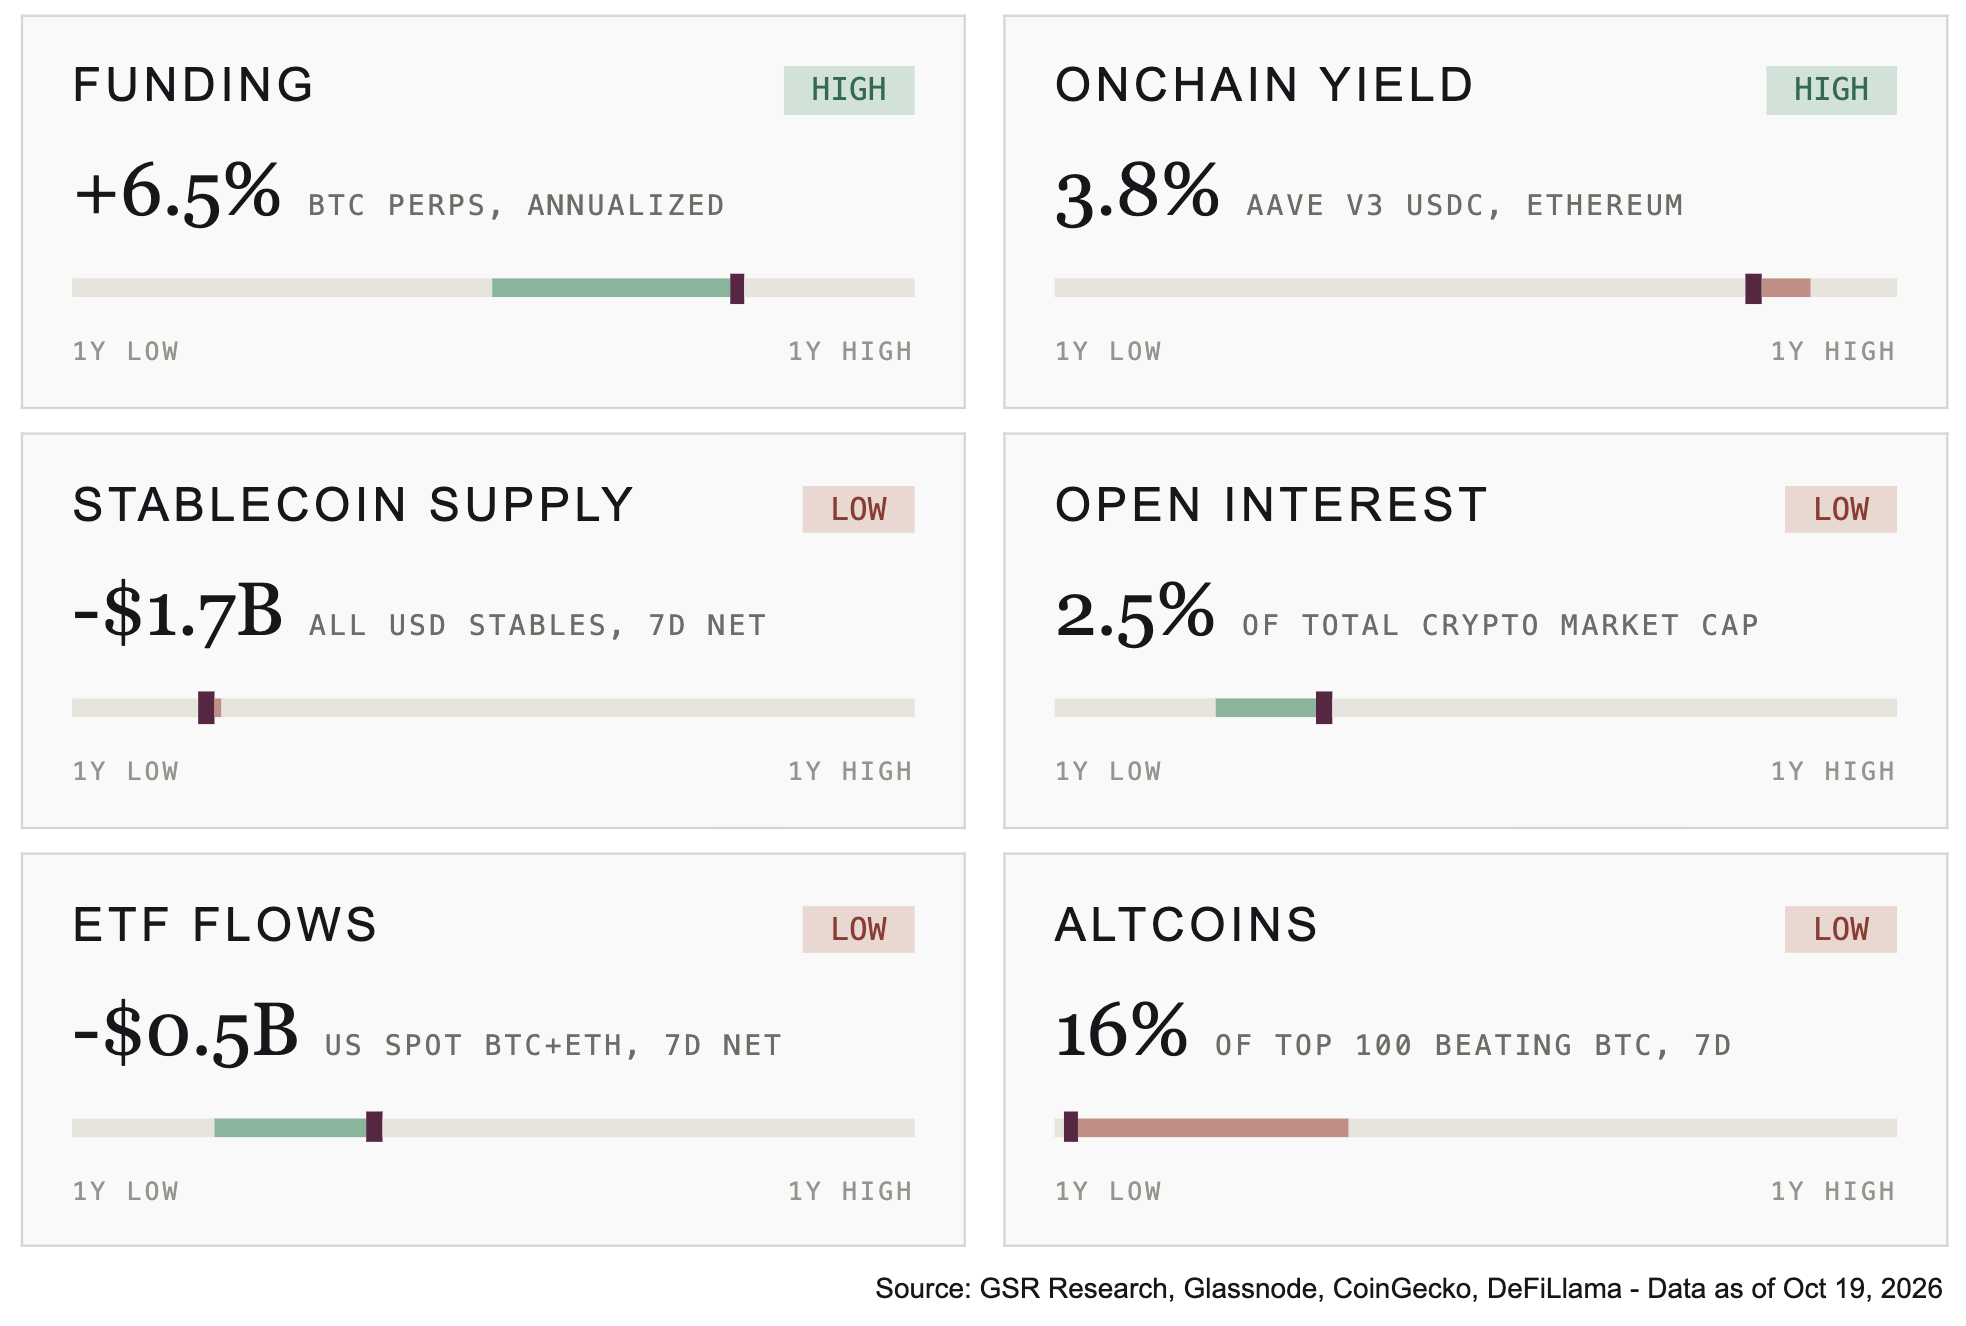
Four of six indicators held in the low range this week, with funding and onchain yield the two exceptions. Funding rose from +3.3% to +6.5% annualized, back into the high range, while open interest edged up from 2.4% to 2.5% of total market cap. ETF flows improved from -$1.2B to -$0.5B but were negative for a second week, and Stablecoin Supply change fell further from -$1.5B to -$1.7B. Onchain yield eased from 4% to 3.8%. Only 16 of the top 100 altcoins beat Bitcoin’s performance over the week, one of the worst displays of market breadth this year.
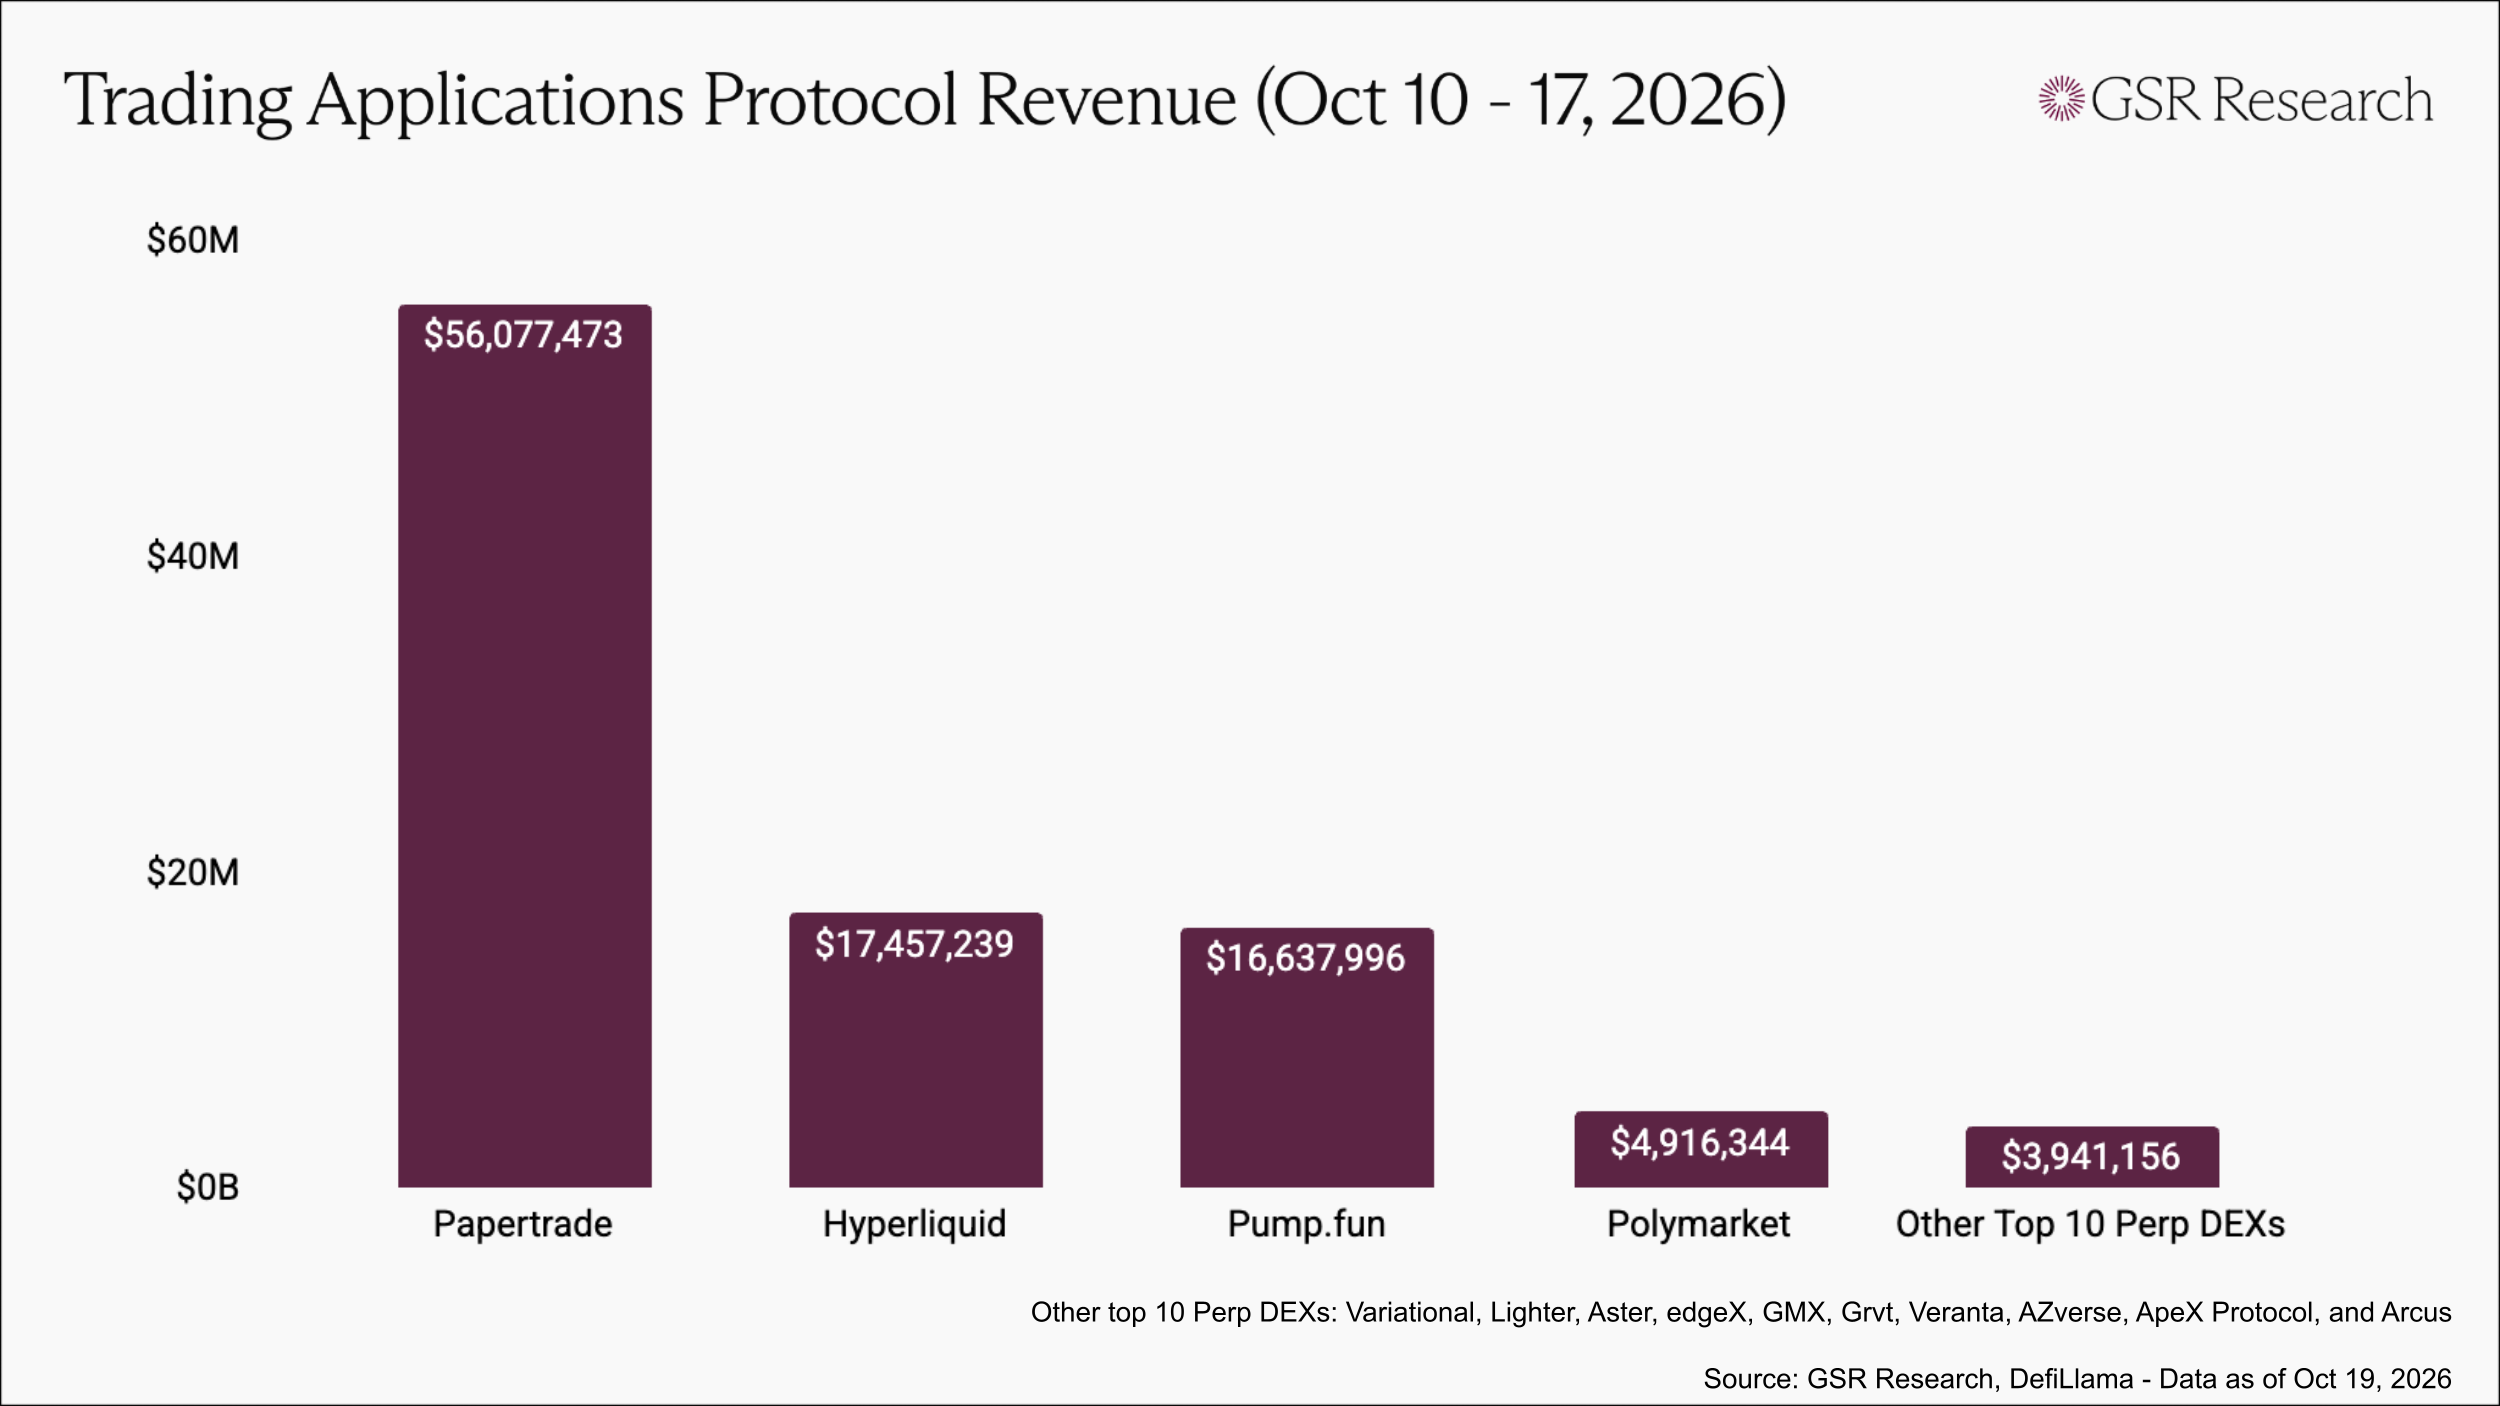
Papertrade, a synthetic perpetuals platform on HyperEVM offering up to 1000x leverage on BTC and ETH, generated $56M in revenue in the week following its launch from Oct 10-17, more than any other protocol and 3.2x Hyperliquid’s $17.5M. On the day of its launch and the 1-year anniversary of 10/10, Papertrade drove $25M in revenue, a figure even higher than the daily revenue for Tether and Circle.
However, almost all of this revenue was incentivised trader losses. The only way to mint the PAPER token has been by closing a losing trade. Initially each dollar lost minted 100 PAPER. However, this rate has intentionally decayed as the pool's cumulative earnings have risen, falling to 31 PAPER per dollar by October 12, and only 11 PAPER per dollar as of writing. Traders farmed PAPER either by intentionally speedrunning liquidations to accumulate PAPER as quickly as possible, or by running delta neutral strategies that maximized PAPER per dollar loss. The LP pool quickly grew from $0 to $56M, with the pool paying out PAPER stakers with any surplus funds over the $5M cap needed to pay winning trades. Net of close and liquidation fees, the LP pool paid out over $50M to PAPER stakers during the first week.
Additionally, the 1000x leverage multiplied the volume a given deposit could generate, as $100 of margin could control a $100,000 position that would have been liquidated after roughly a 0.05% adverse move. Launch-day notional volume exceeded $678B against roughly $137M of deposits, and collateral liquidated reached $63.4M through October 18, slightly above cumulative revenue.
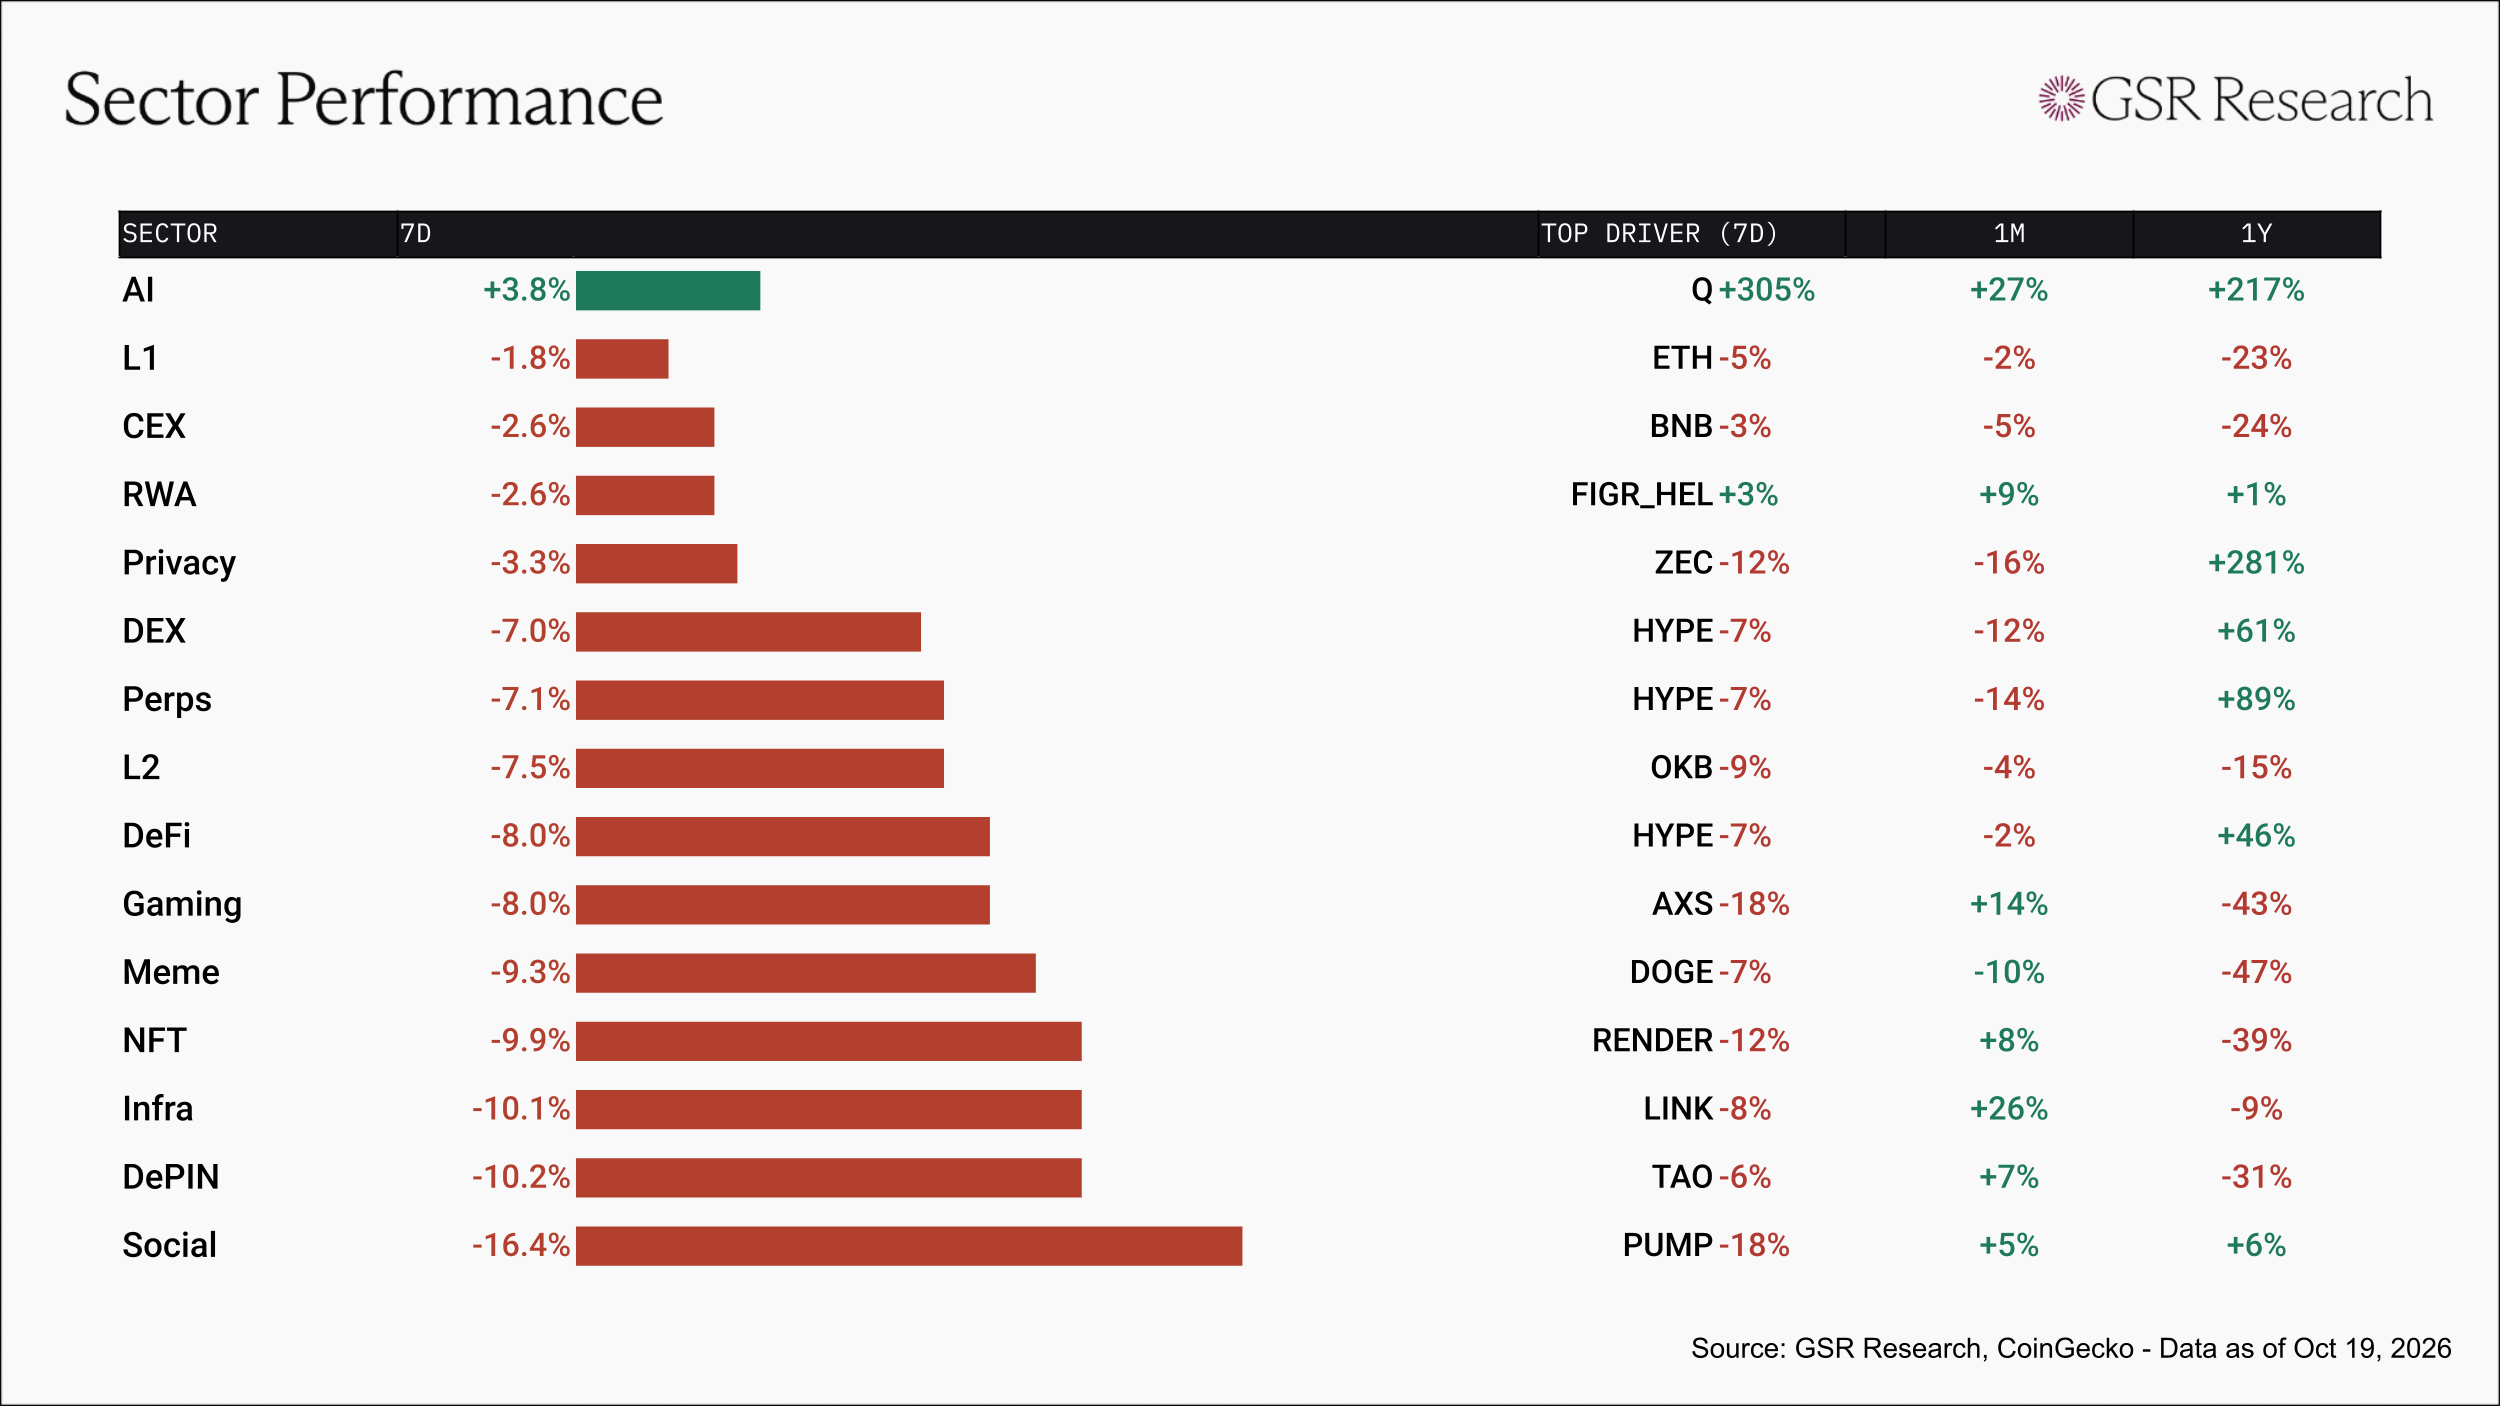
14 of 15 sectors closed red this week, with AI the only gainer at +3.8% on Q (+305%), with its futures volume reaching 25.7 times its spot volume on Sunday as the token rose 83% in a day. The AI sector is now up +27% on the month. L1 (-1.8%) held up on BTC (-1%) despite ETH (-5%), CEX (-2.6%) followed BNB (-3%), and RWA (-2.6%) held on FIGR_HELOC (+3%). Privacy (-3.3%) fell less than ZEC (-12%), leaving the sector down -16% on the month.
Social fell furthest at -16.4% as PUMP (-18%) extended last week's decline, driven in part by a team and investor unlock of about 6.9B PUMP, after which three wallets sold a combined 2.9B PUMP for $12.6M, per Lookonchain. DePIN (-10.2%) and Infra (-10.1%) followed TAO (-6%) and LINK (-8%), NFT (-9.9%) carried RENDER (-12%), and Meme (-9.3%) tracked DOGE (-7%). The rest of the board fell 7.0% to 8.0%, with Gaming (-8.0%) on AXS (-18%), the three HYPE-driven sectors, DeFi (-8.0%), Perps (-7.1%), and DEX (-7.0%), falling with HYPE (-7%), and L2 (-7.5%) following OKB (-9%).
Data appendix. Each Market Pulse tile shows where a gauge sits in its own trailing one-year range: the bar runs from the year's low to its high, the dark marker is this week's reading, and the colored span behind it is the week's move, green when the gauge climbed its range and red when it fell. Tags mark position in that range: HIGH above the 65th percentile, LOW below the 35th, NEUTRAL between, with the tag's color carrying the read. Funding is BTC perpetual funding, OI-weighted across major venues and annualized; onchain yield is Aave v3's USDC market on Ethereum; stablecoin flows is the 7-day net change in supply of all USD-pegged stablecoins across all chains per DeFiLlama; open interest sums futures in the twelve largest futures assets (roughly 95% of all crypto futures OI) against total crypto market cap; ETF flows combines US spot Bitcoin and Ethereum funds on a rolling 7 days; and altcoins is the share of the top 100, excluding stablecoins and wrappers, beating BTC over 7 days. Sector returns are cap-weighted CoinGecko categories, top ten constituents each. Sources: GSR Research, Glassnode, Deribit, CoinGecko, DeFiLlama, FRED, Tokenomist.
This material is provided by GSR (the “Firm”) solely for informational purposes. It is not intended to be advice or a recommendation to buy, sell or hold any investment mentioned. Investors should form their own views in relation to any proposed investment.
It is intended only for sophisticated, institutional investors and does not constitute an offer or commitment, a solicitation of an offer or commitment, or any advice or recommendation, to enter into or conclude any transaction (whether on the terms shown or otherwise), or to provide investment services in any state or country where such an offer or solicitation or provision would be illegal. The Firm is not and does not act as an advisor or fiduciary in providing this material.
This material is not an independent research report, and has not been prepared in accordance with any legal requirements by any regulator (including the FCA, FINRA or CFTC) designed to promote the independence of investment research.
This material is not independent of the Firm’s proprietary interests, which may conflict with the interests of any counterparty of the Firm. The Firm may trade investments discussed in this material for its own account, may trade contrary to the views expressed in this material, and may have positions in other related instruments. The Firm is not subject to any prohibition on dealing ahead of the dissemination of this material.
Information contained herein is based on sources considered to be reliable, but is not guaranteed to be accurate or complete. Any opinions or estimates expressed herein reflect a judgment made by the author(s) as of the date of publication, and are subject to change without notice. The Firm does not plan to update this information.
Trading and investing in digital assets involves significant risks including price volatility and illiquidity and may not be suitable for all investors. The Firm is not liable whatsoever for any direct or consequential loss arising from the use of this material. Copyright of this material belongs to GSR. Neither this material nor any copy thereof may be taken, reproduced or redistributed, directly or indirectly, without prior written permission of GSR.
Please see here for additional Regulatory Legal Notices relevant to US, UK and Singapore.