Share:

Overview
- BTC fell ~14% to $65k after breaking below its 200-week moving average over the weekend, with ETH ~14% lower, the alt basket down ~12%, gold ~6% lower, and all 15 sectors closing red.
- October CPI rose 0.4% against a 0.3% consensus, with core up 0.3% for a third straight month, and CME FedWatch now fully prices a December hike, with odds of a 50bp move at about 13%.
- BTC traded about 3.6% above the global price on Upbit on Saturday, up from about 0.3% on November 1, while Coinbase traded at a discount to the global price on every day of the month.
- ETF flows rose from -$2B to -$1.4B, and 62 of the top 100 alts beat Bitcoin, while funding fell from +6.6% to +2.2% annualized and stablecoin net supply change was -$4.2B in a sixth straight week of net contraction.
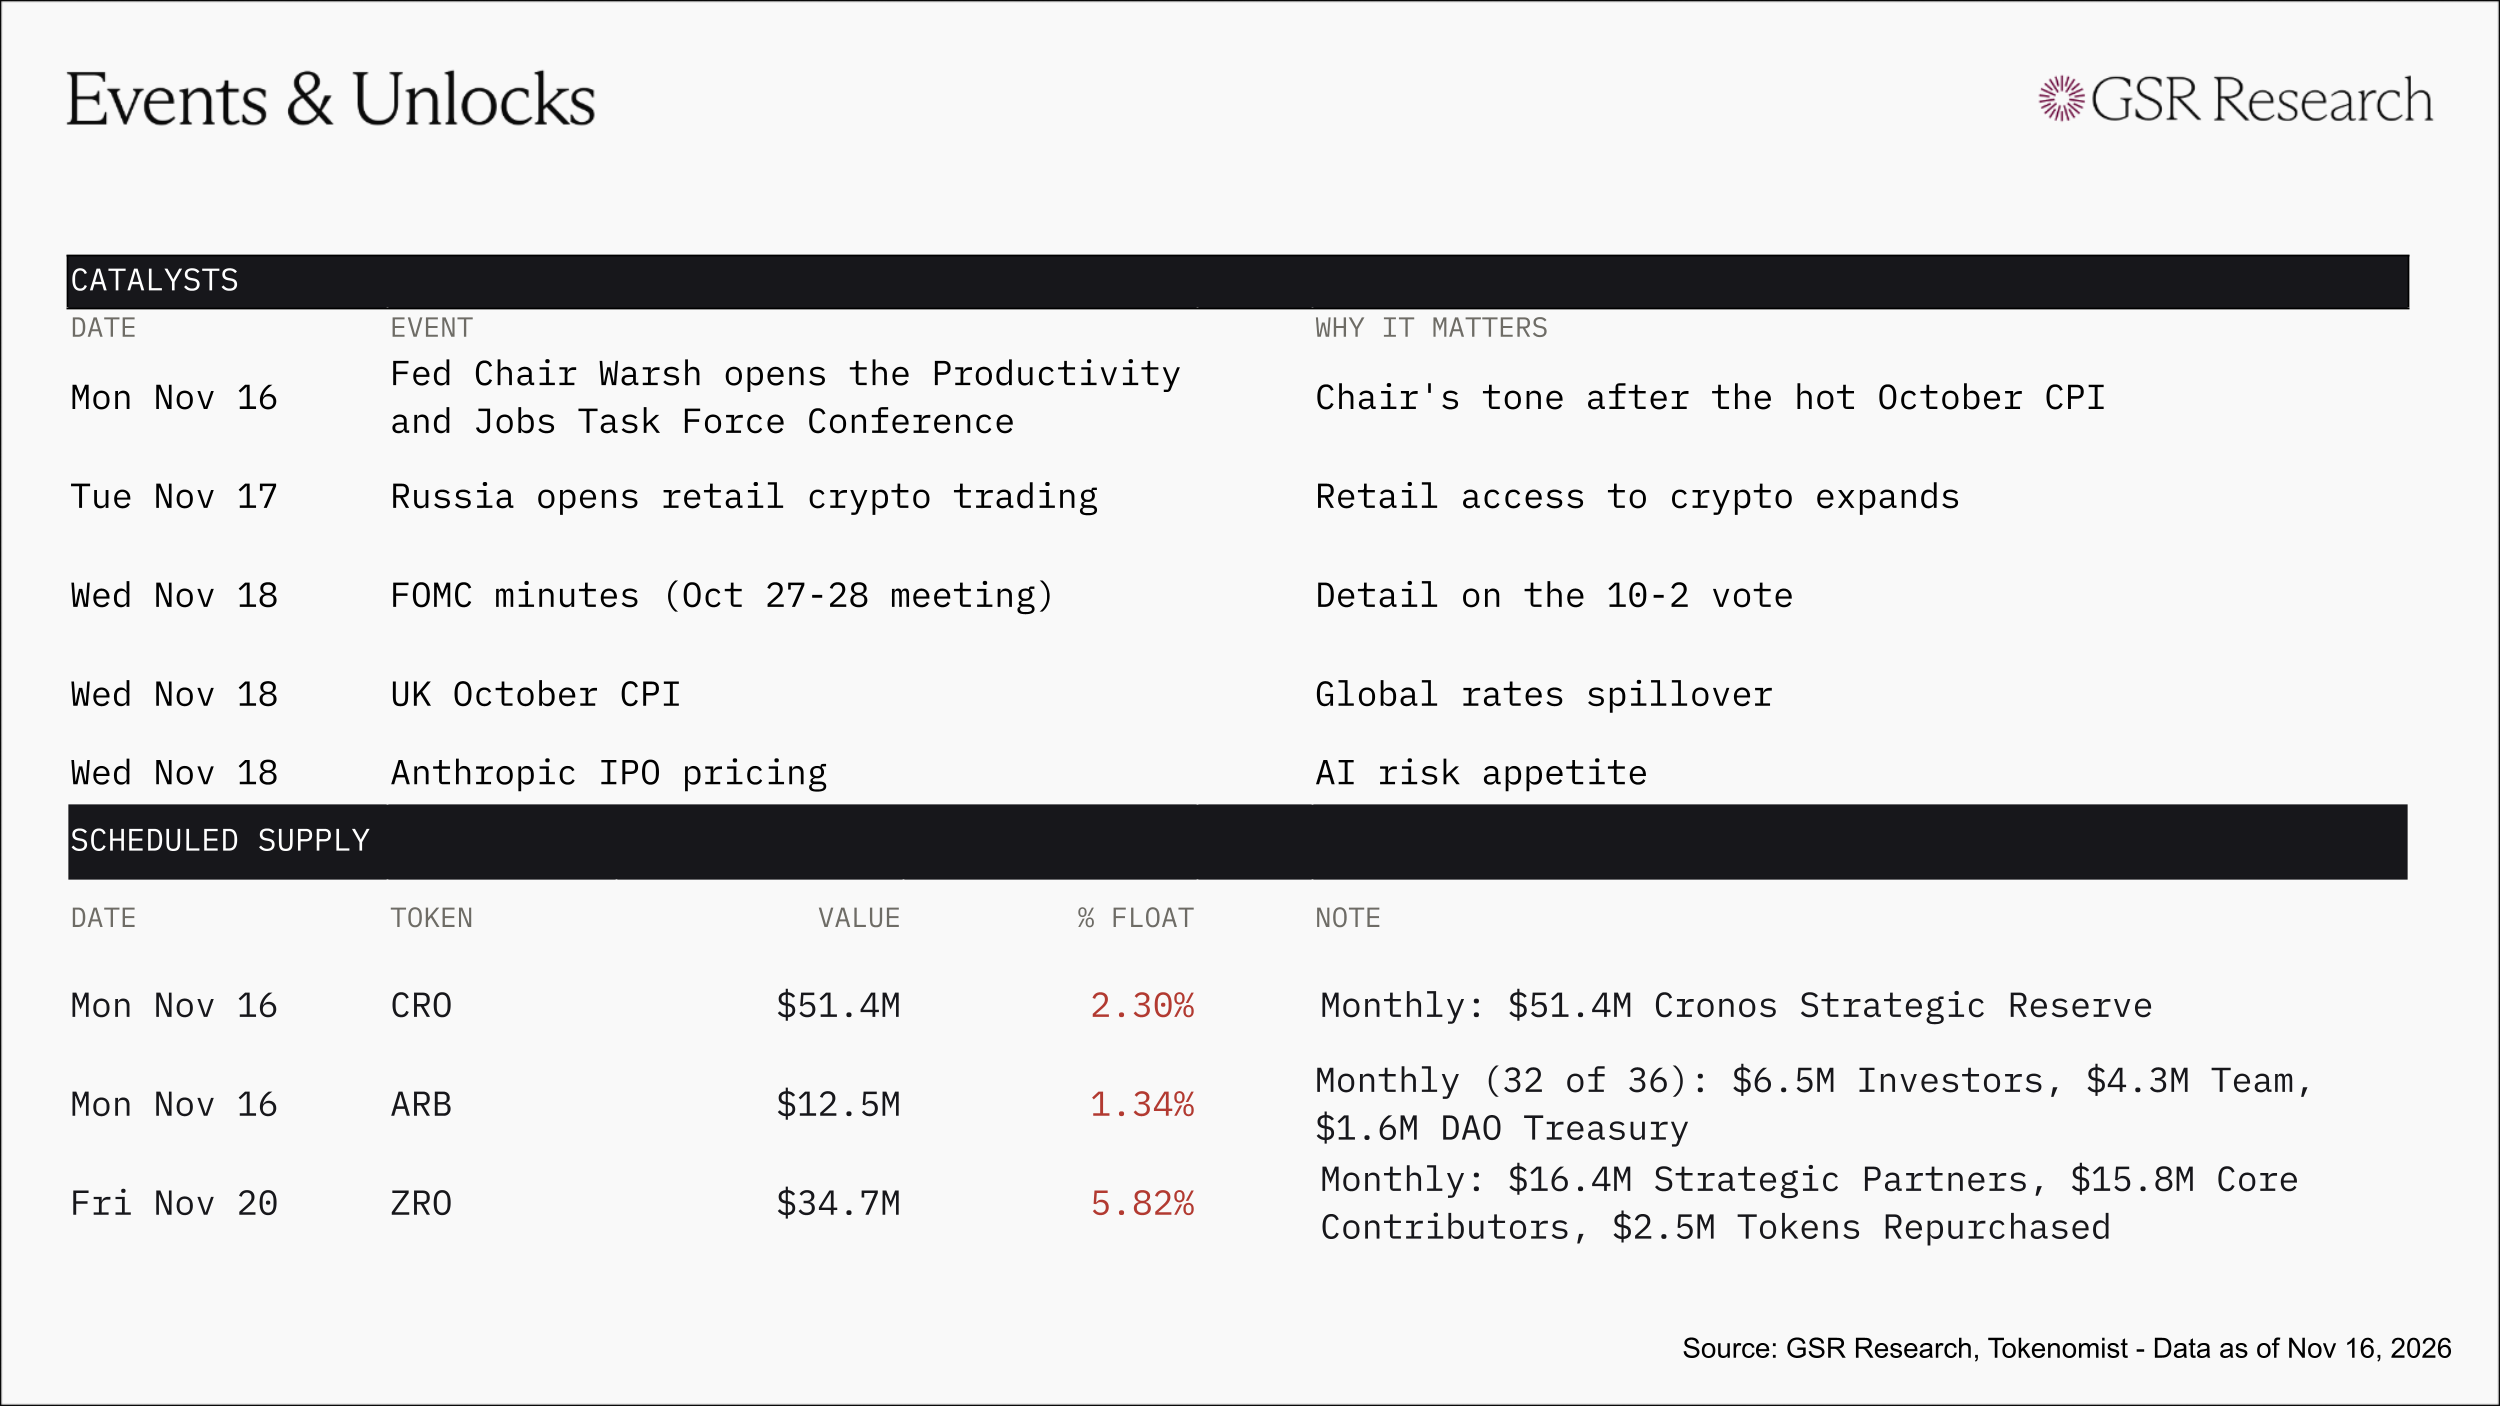
- All eyes are on Anthropic’s IPO, Wednesday's FOMC minutes, and remarks from Fed Chair Warsh, Vice Chair Jefferson, and Governor Cook.
The Week in Review
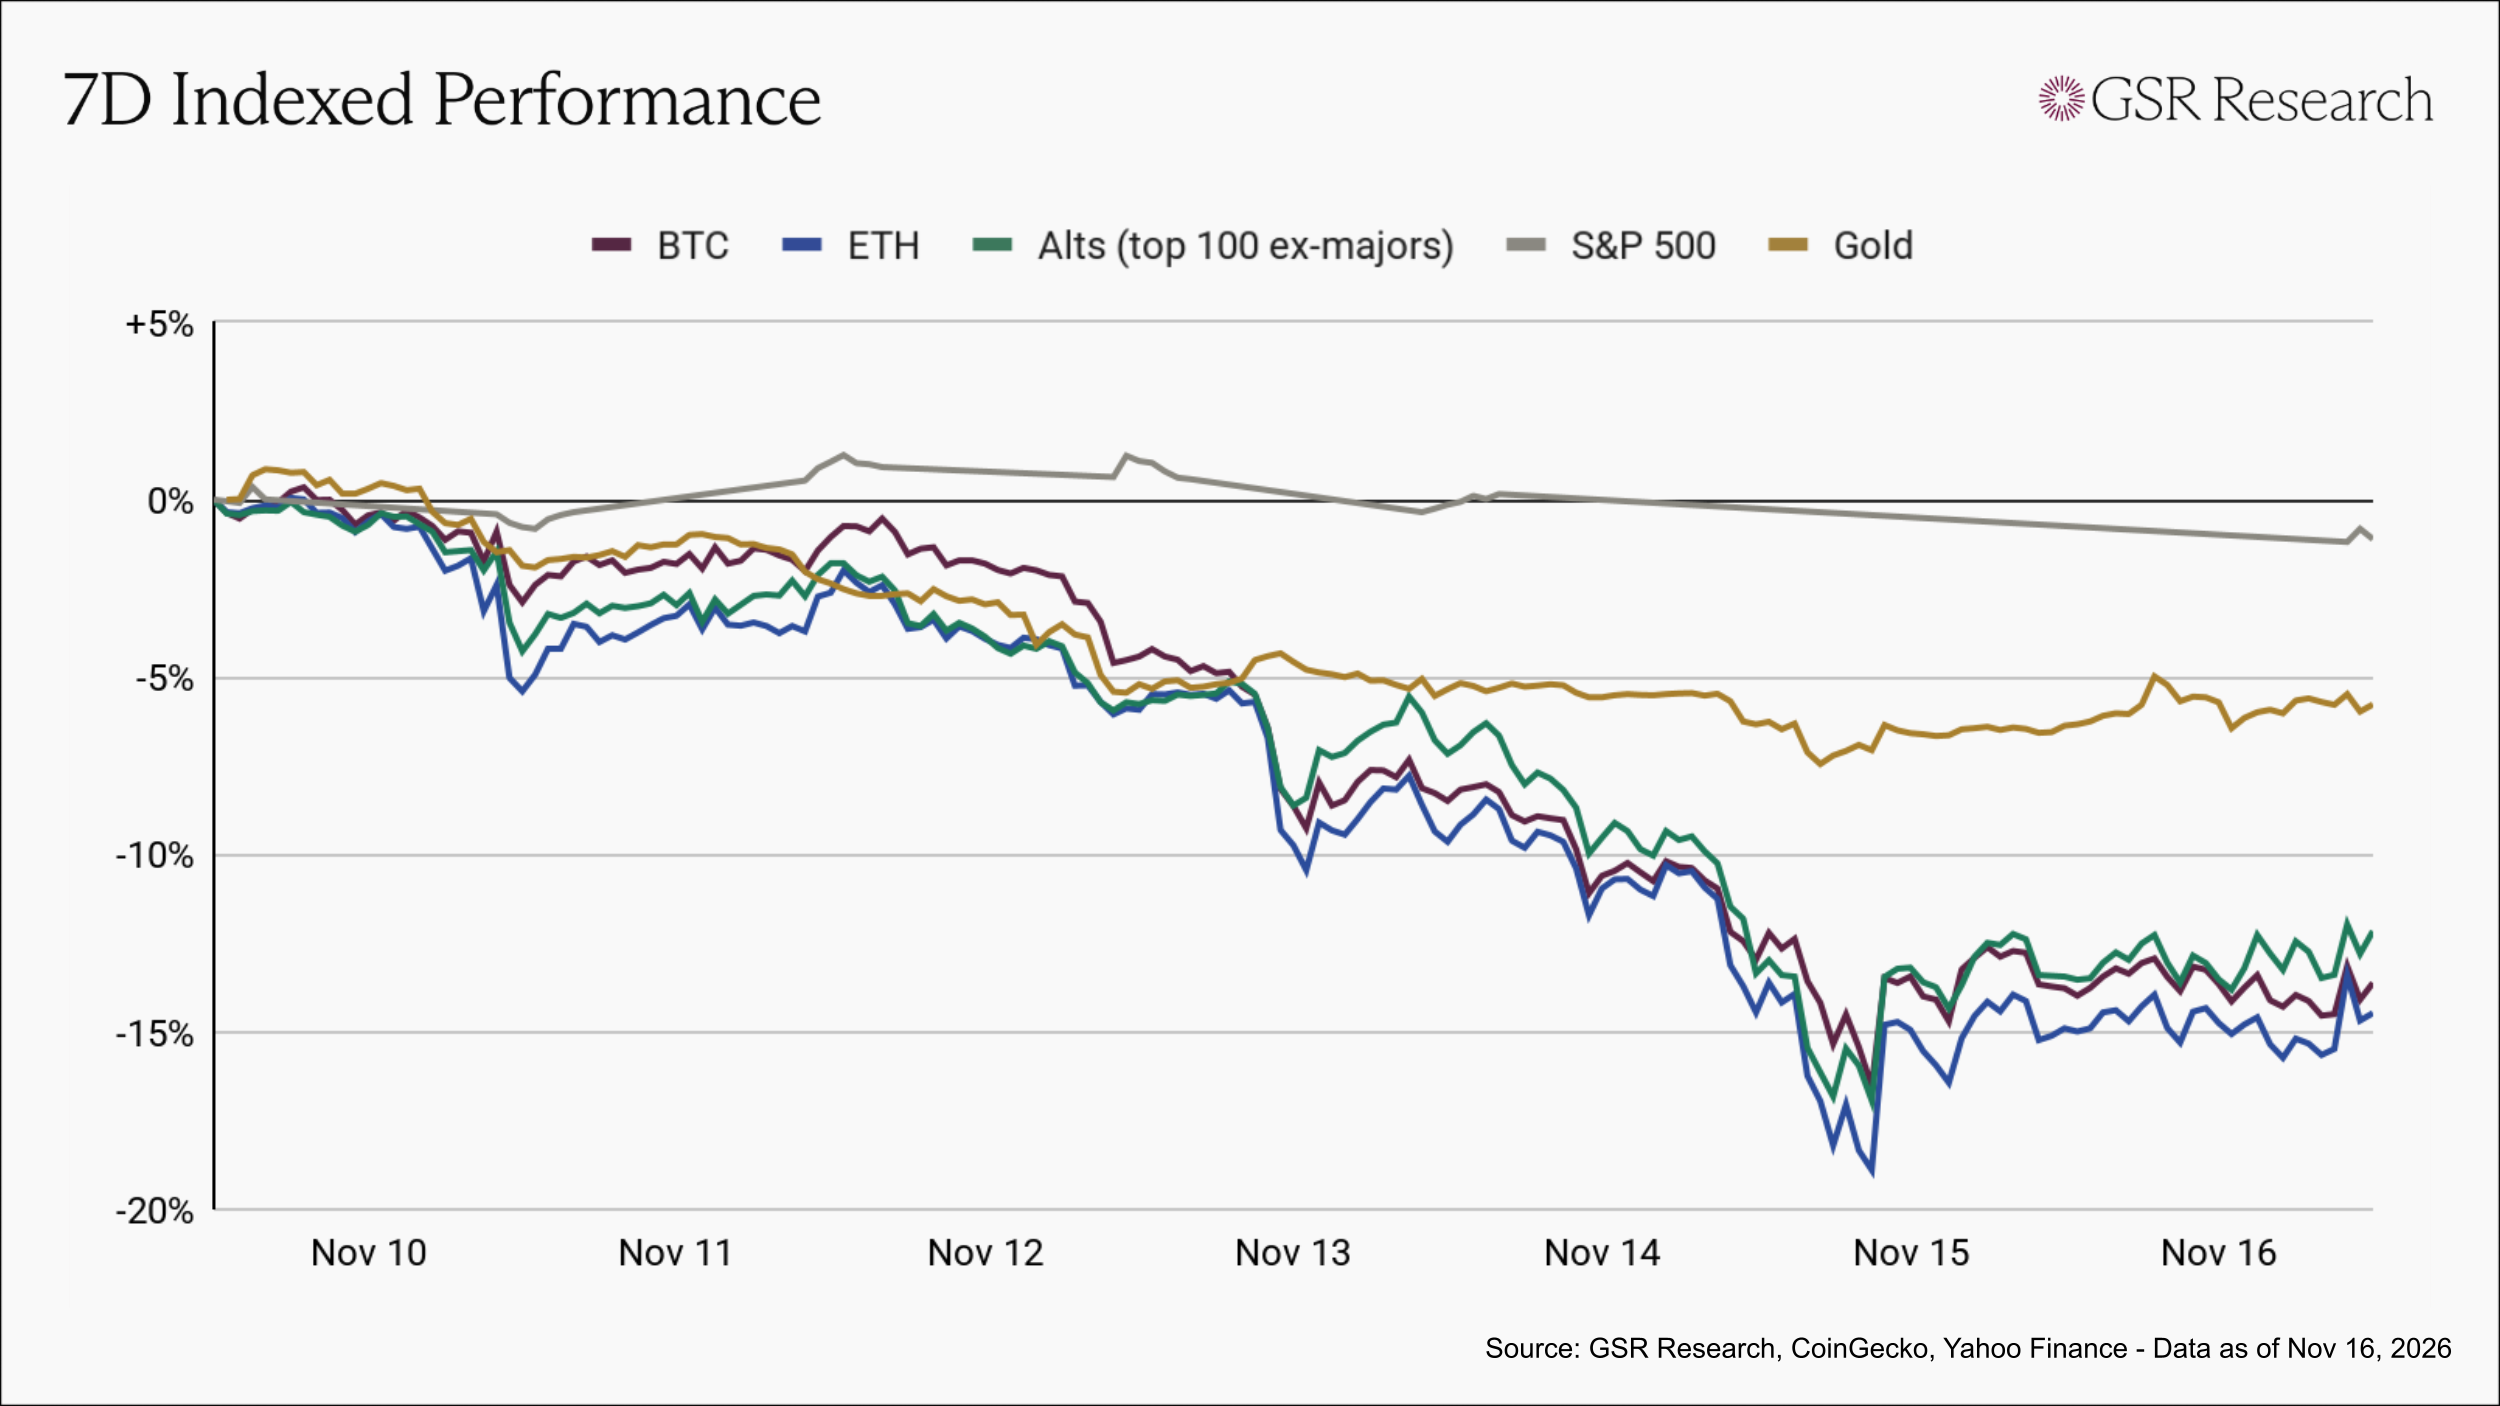
Fed Governor Waller said in London on Tuesday morning that he would support a 25bp hike at the December 8-9 FOMC, and October CPI, released hours later, came in above forecasts, with core rising 0.3% against a 0.2% consensus. CME FedWatch moved to fully price a December hike, with odds of a 50bp move rising from near zero to 13.6%, and the 10-year Treasury yield climbed above 5%. BTC slipped from about $74,300 before the release to $72,800 that afternoon, then recovered to $74,600 on Wednesday. The rebound faded after reports on Wednesday evening that Nvidia’s board was preparing to oust CEO Jensen Huang sent the stock down 8.2% in after-hours trading. Nvidia announced Huang’s resignation on Thursday, with CFO Colette Kress named interim CEO, and BTC fell steadily through the session to about $71,300 by Thursday evening, driven in part by the selloff in tech.
The selling accelerated overnight. BTC broke below $70,000 late Thursday and fell to about $68,000 in early Friday trading, with about $1.47B of crypto positions liquidated over 24 hours. October PPI came in softer than expected at 0.3% on Friday morning, but BTC recovered only to about $69,300 as three Fed officials backed further tightening and the 10-year yield closed the week at 5.15%, up 29bp, with the dollar index at a 19-month high. BTC closed Friday at $68,314, just above its 200-week moving average near $68,000. Much of the selling appears to have come from U.S. spot sellers, with spot selling on Coinbase running heavier than on other major exchanges since Monday, and spot Bitcoin ETFs posting outflows in all five sessions for a weekly total of -$1.07B, $908M of it from IBIT. The selling resumed on Saturday, when BTC fell through its 200-week moving average and slid below $63,000 by Saturday night, its lowest level since mid-July, and total crypto liquidations topped $2B over 24 hours. BTC finished down ~14% at $65k, ETH ~14% lower, the alt basket down ~12%, gold ~6% lower, and the S&P ~1% lower.
Market Pulse
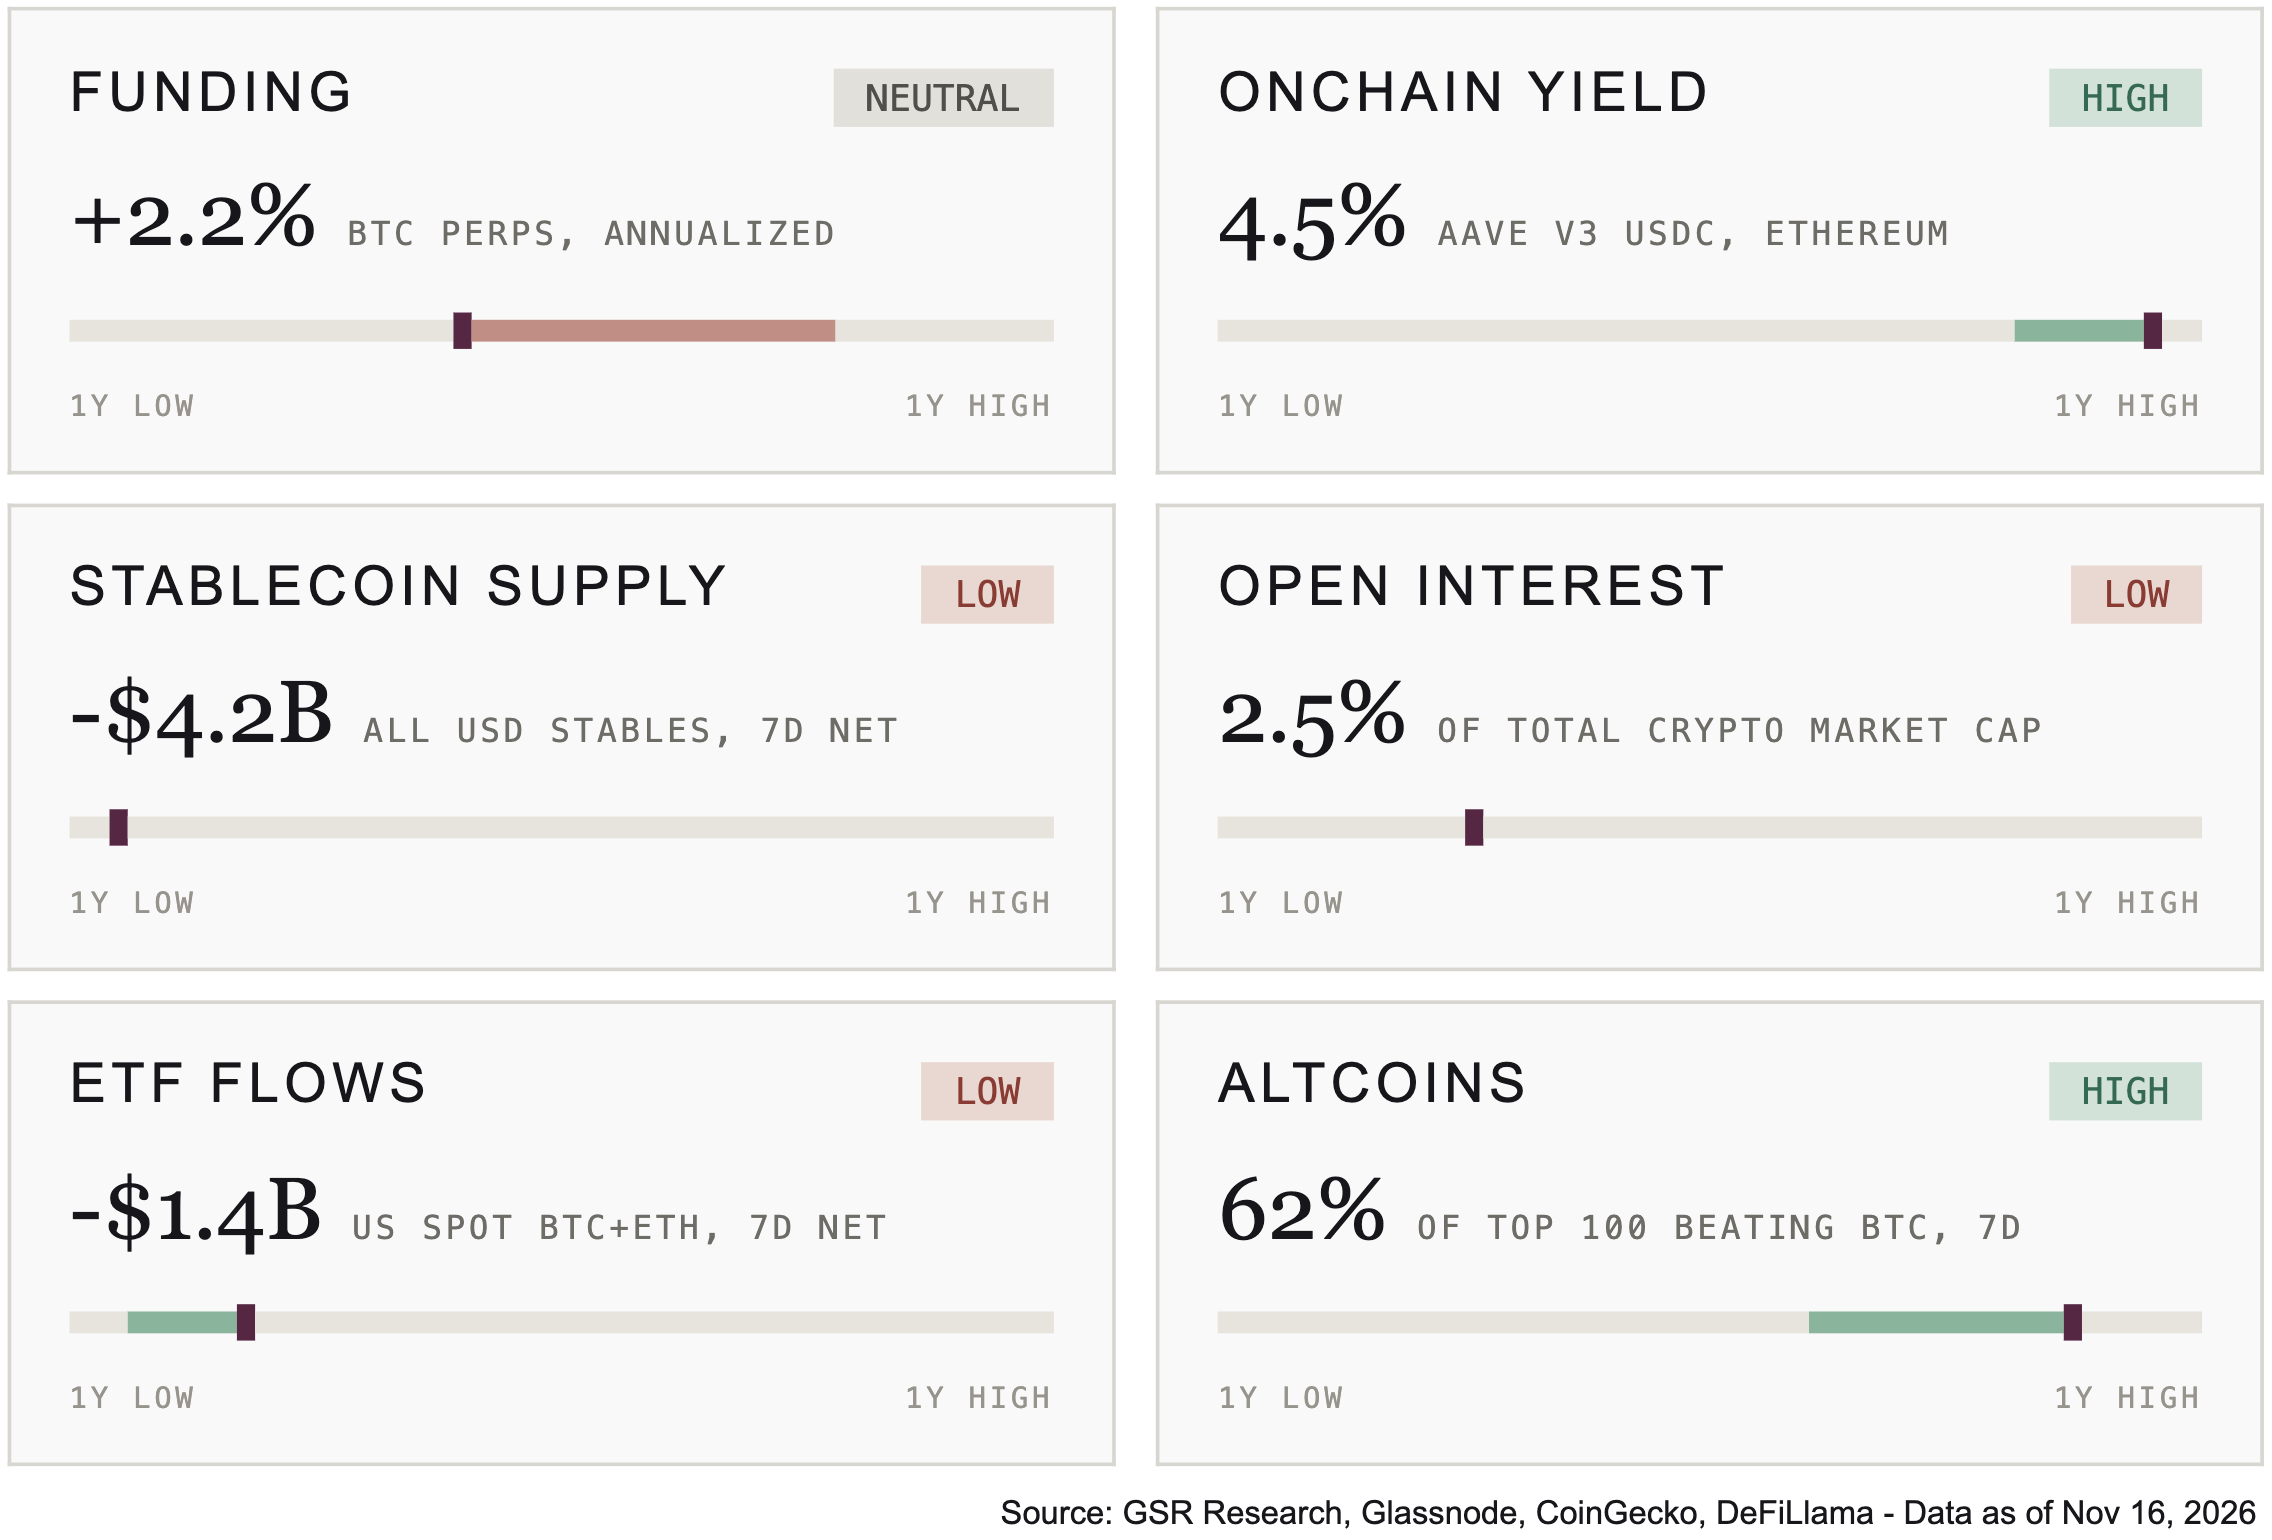
Funding cooled into the neutral range this week, while onchain yield and altcoin breadth both moved into the high range. Funding fell from +6.6% to +2.2% annualized, and onchain yield rose from 3.8% to 4.5%. ETF flows rose from -$2B to -$1.4B but stayed near the bottom of their one-year range, and Stablecoin Supply change rose from -$4.8B to -$4.2B, a sixth straight week of net contraction that leaves it near its one-year low. 62 of the top 100 altcoins beat Bitcoin, up from 45 the week prior.
Chart of the Week: Upbit Premium Climbs to 3.6% as BTC Falls
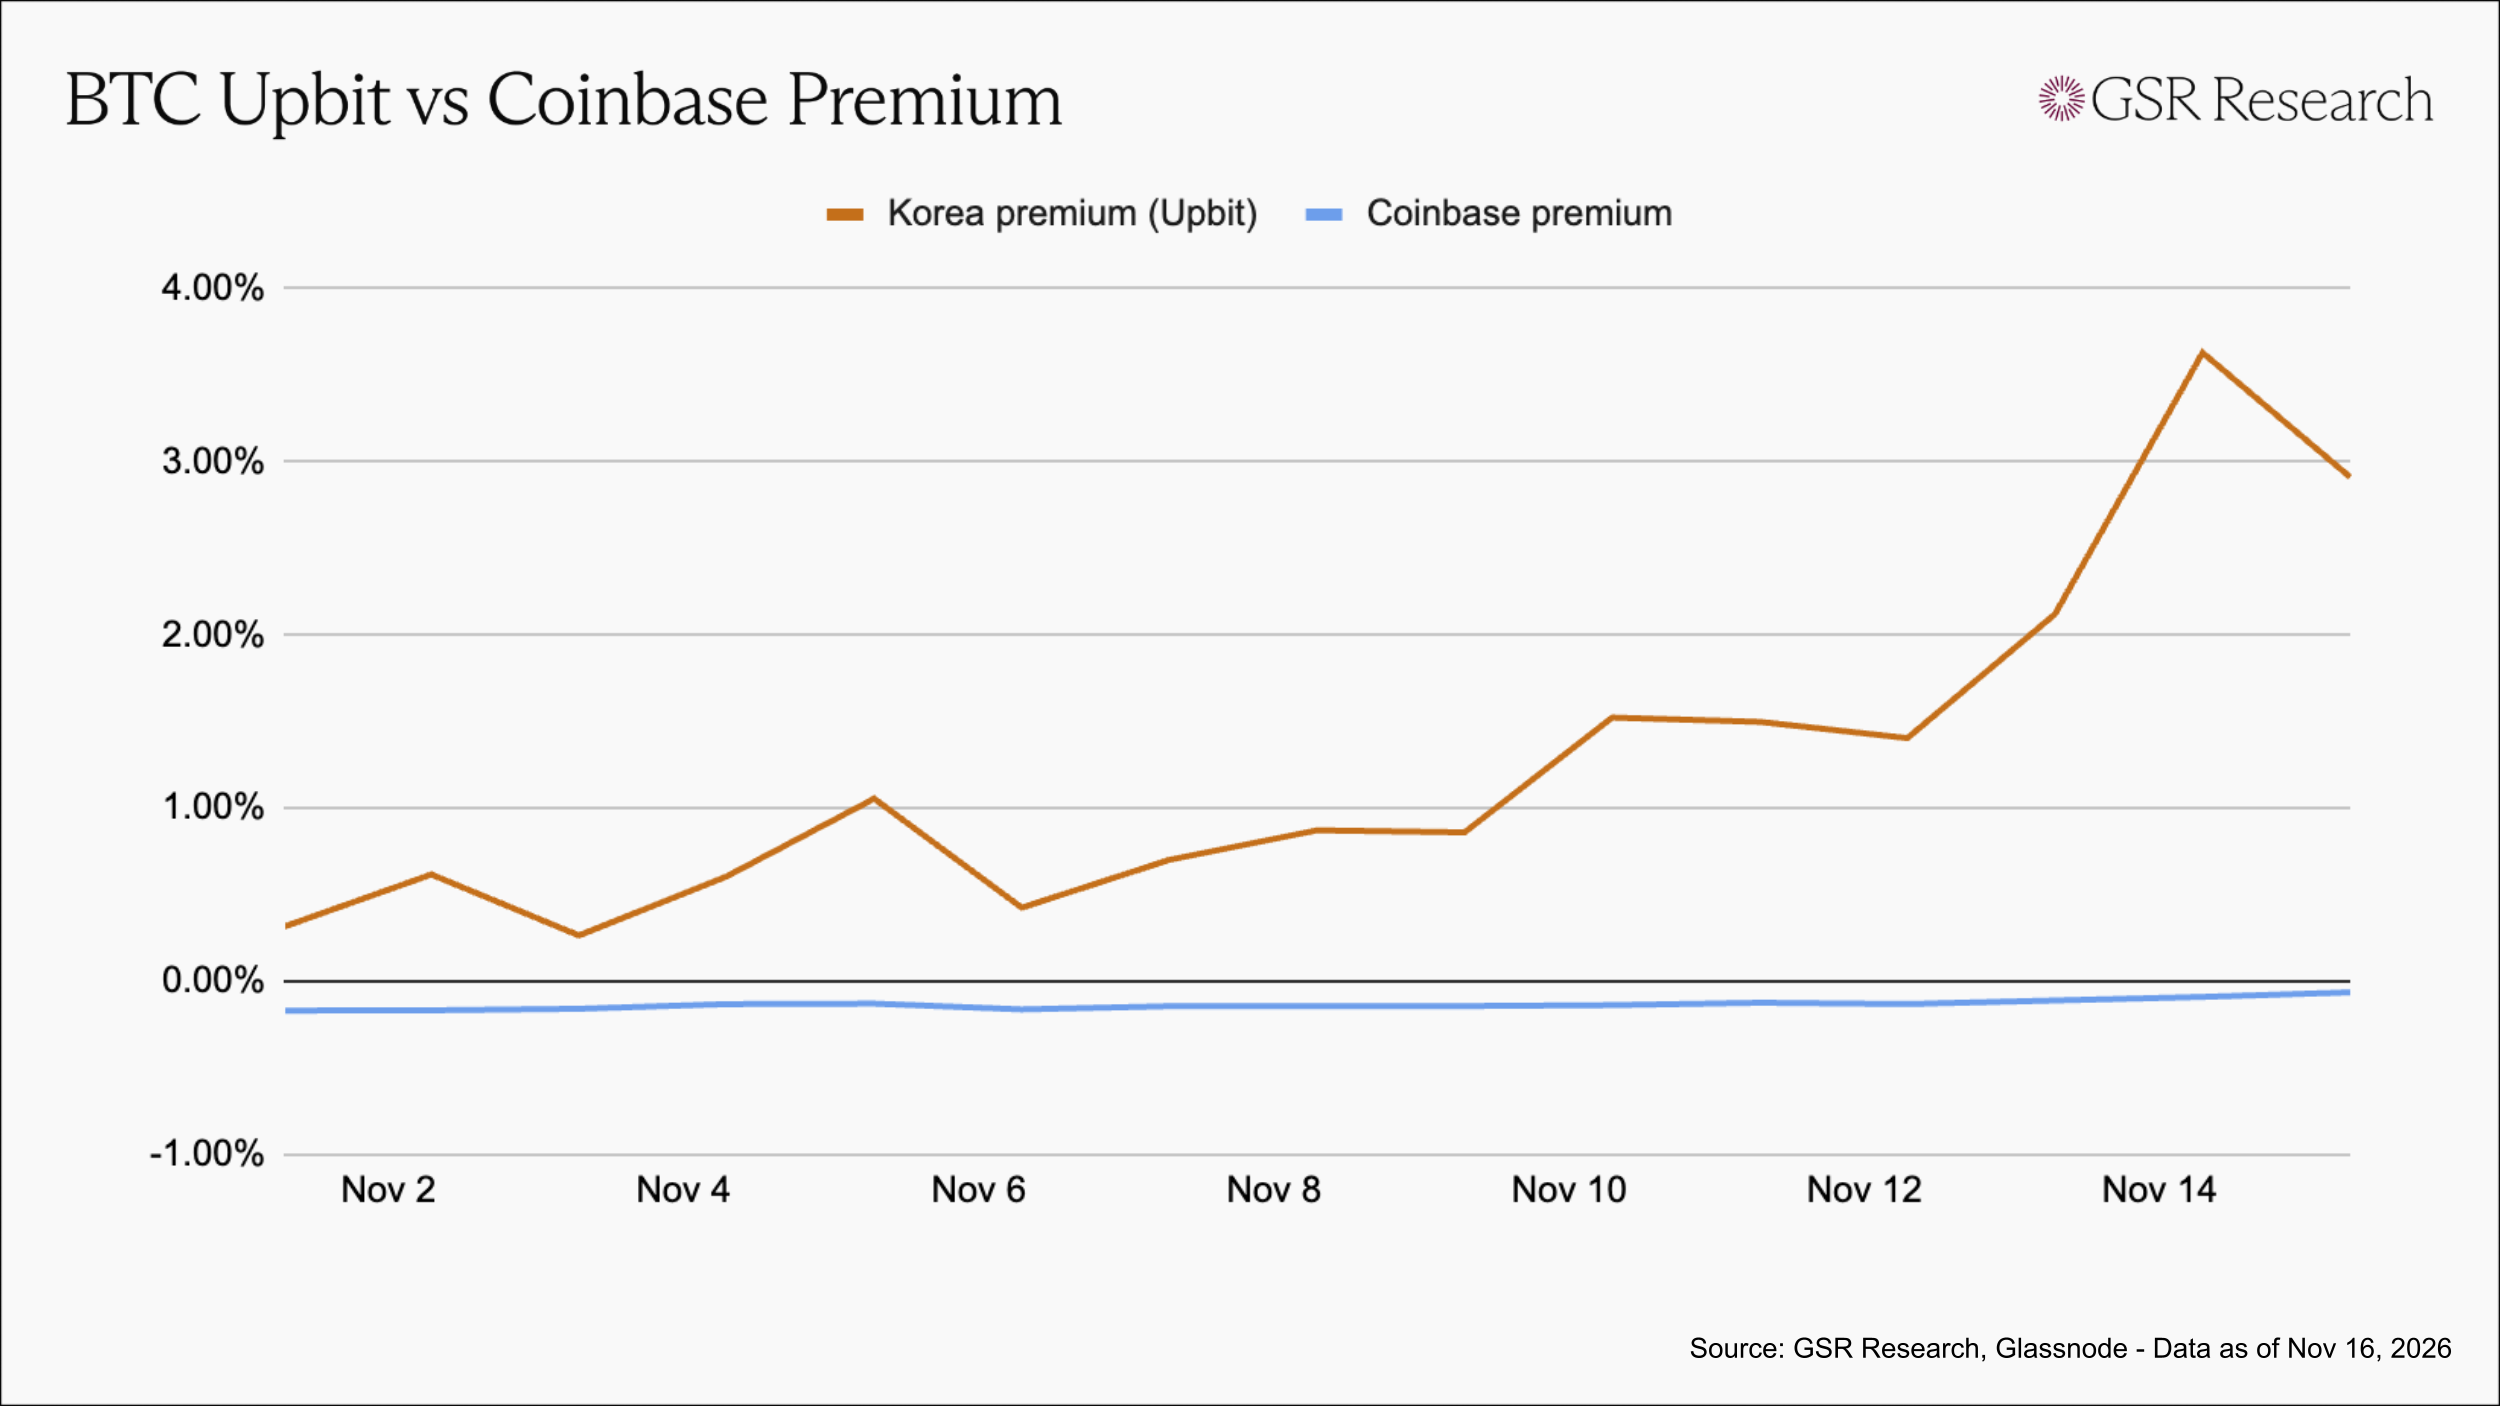
BTC traded roughly 3.6% above the global price on Upbit, Korea's largest exchange, on November 14, the day it fell to its lowest level since mid-July, up from 0.3% on November 1. The premium widened in steps, rising above 1.5% on November 10, the day of the hot CPI print, and above 2% on November 13 as BTC broke below $70,000, before ending November 15 at about 2.9%. While BTC sold off on every major venue, Korean buyers continued paying above the global price on every day of the decline. The premium had previously sat near zero in early November, and Korean prices traded at a discount to global prices for much of the summer, so this month’s move marks a shift toward Korean buying into weakness.
Korean demand for spot BTC rose as prices fell, and the premium held because it is hard to arbitrage. Korean exchanges only accept won deposits from real-name accounts at local banks, and foreign exchange rules limit how much capital traders can move abroad to buy BTC on offshore venues, so single percentage gaps can stay open for days.
Coinbase, meanwhile, traded at a slight discount to the global price on every day of the month. As the largest U.S. spot venue and the custodian for most U.S. spot Bitcoin ETFs, Coinbase’s premium is widely read as a gauge of U.S. demand, with a discount meaning U.S. sellers are pushing Coinbase’s price below other venues. Because capital moves freely between Coinbase and offshore exchanges, its premium usually stays within a few tenths of a percent, so even a small discount held over several weeks reflects persistent U.S. selling.
Sector Breakdown
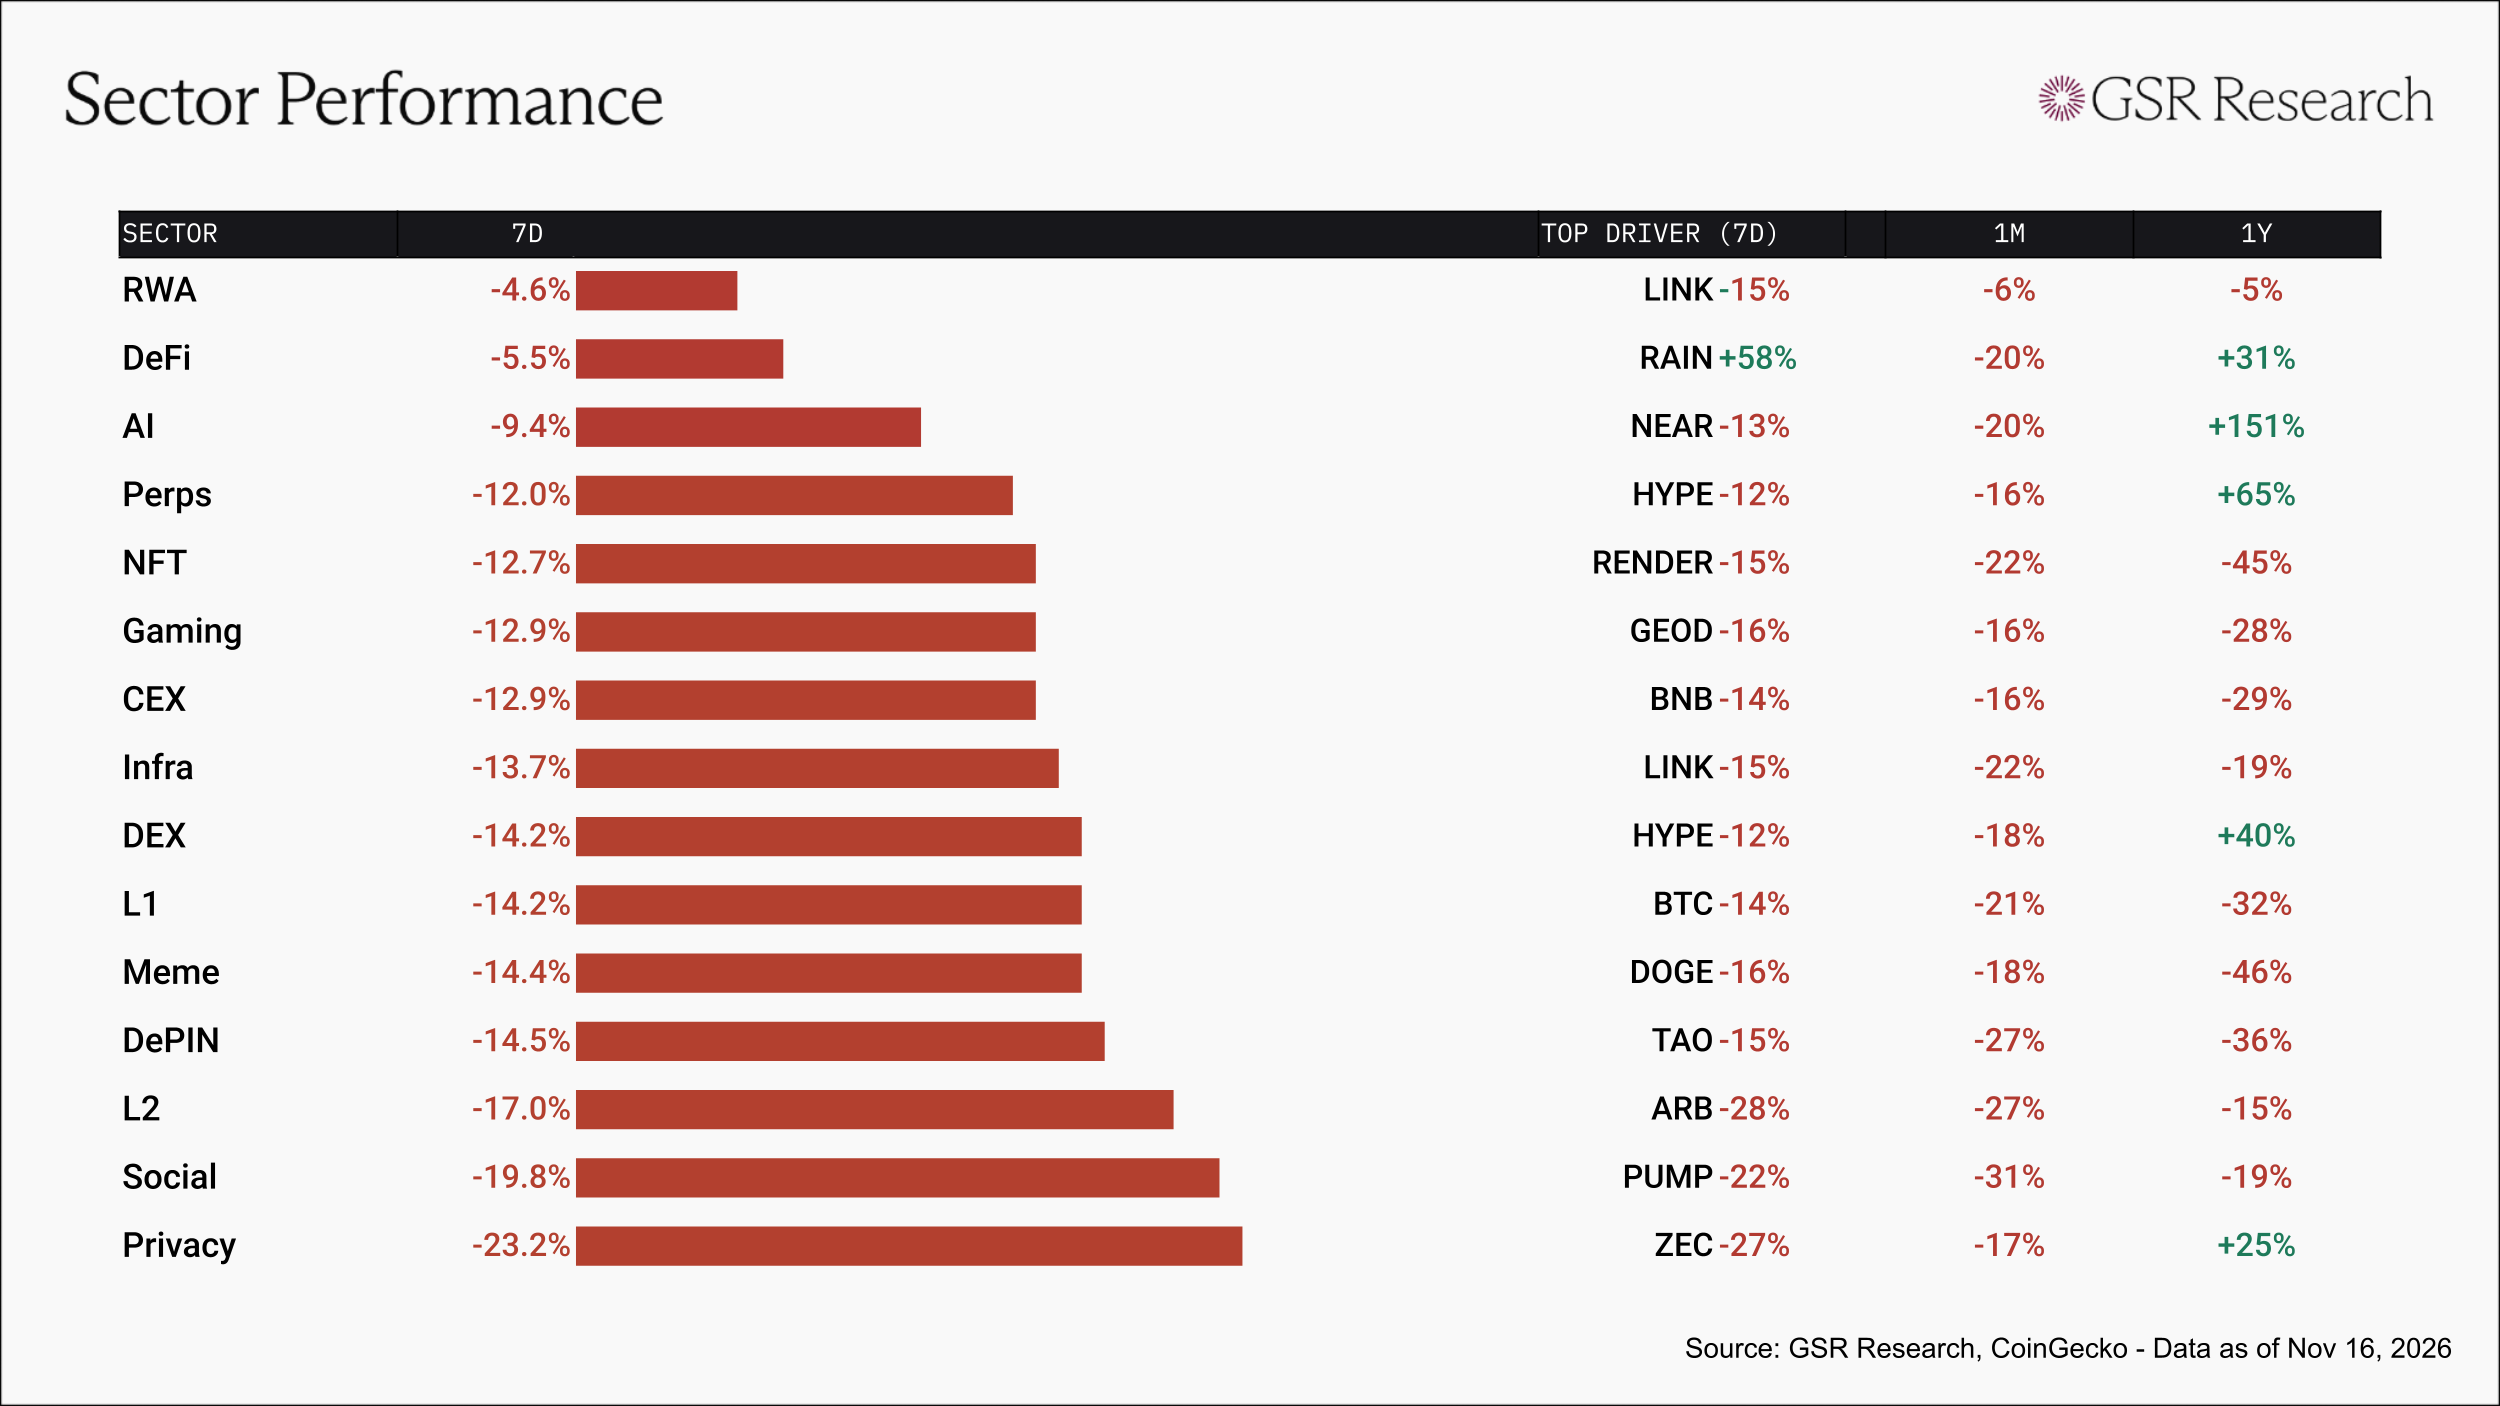
All 15 sectors closed red this week, as RWA fell least at -4.6% despite LINK (-15%). DeFi (-5.5%) held up on RAIN (+58%), and AI (-9.4%) fell with NEAR (-13%).
Privacy fell furthest at -23.2% on ZEC (-27%), which dropped below $1,000 on Wednesday for the first time since September, giving back its gains from the NU7 upgrade amid outflows from Grayscale's Zcash trust. Social (-19.8%) tracked PUMP (-22%), and L2 (-17.0%) fell with ARB (-28%). The L2 sector is now down 27% on the month. The rest of the board fell 12.0% to 14.5%, with Perps (-12.0%) and DEX (-14.2%) on HYPE (-12%), which fell despite a Q3 report showing record open interest and $190.9M of protocol revenue, NFT (-12.7%) on RENDER (-15%), CEX (-12.9%) on BNB (-14%), Infra (-13.7%) on LINK (-15%), L1 (-14.2%) on BTC (-14%), Meme (-14.4%) on DOGE (-16%), and DePIN (-14.5%) on TAO (-15%).
The Week Ahead
Data appendix. Each Market Pulse tile shows where a gauge sits in its own trailing one-year range: the bar runs from the year's low to its high, the dark marker is this week's reading, and the colored span behind it is the week's move, green when the gauge climbed its range and red when it fell. Tags mark position in that range: HIGH above the 65th percentile, LOW below the 35th, NEUTRAL between, with the tag's color carrying the read. Funding is BTC perpetual funding, OI-weighted across major venues and annualized; onchain yield is Aave v3's USDC market on Ethereum; stablecoin flows is the 7-day net change in supply of all USD-pegged stablecoins across all chains per DeFiLlama; open interest sums futures in the twelve largest futures assets (roughly 95% of all crypto futures OI) against total crypto market cap; ETF flows combines U.S. spot Bitcoin and Ethereum funds on a rolling 7 days; and altcoins is the share of the top 100, excluding stablecoins and wrappers, beating BTC over 7 days. Sector returns are cap-weighted CoinGecko categories, top ten constituents each. Sources: GSR Research, Glassnode, Deribit, CoinGecko, DeFiLlama, FRED, Tokenomist.
This material is provided by GSR (the “Firm”) solely for informational purposes. It is not intended to be advice or a recommendation to buy, sell or hold any investment mentioned. Investors should form their own views in relation to any proposed investment.
It is intended only for sophisticated, institutional investors and does not constitute an offer or commitment, a solicitation of an offer or commitment, or any advice or recommendation, to enter into or conclude any transaction (whether on the terms shown or otherwise), or to provide investment services in any state or country where such an offer or solicitation or provision would be illegal. The Firm is not and does not act as an advisor or fiduciary in providing this material.
This material is not an independent research report, and has not been prepared in accordance with any legal requirements by any regulator (including the FCA, FINRA or CFTC) designed to promote the independence of investment research.
This material is not independent of the Firm’s proprietary interests, which may conflict with the interests of any counterparty of the Firm. The Firm may trade investments discussed in this material for its own account, may trade contrary to the views expressed in this material, and may have positions in other related instruments. The Firm is not subject to any prohibition on dealing ahead of the dissemination of this material.
Information contained herein is based on sources considered to be reliable, but is not guaranteed to be accurate or complete. Any opinions or estimates expressed herein reflect a judgment made by the author(s) as of the date of publication, and are subject to change without notice. The Firm does not plan to update this information.
Trading and investing in digital assets involves significant risks including price volatility and illiquidity and may not be suitable for all investors. The Firm is not liable whatsoever for any direct or consequential loss arising from the use of this material. Copyright of this material belongs to GSR. Neither this material nor any copy thereof may be taken, reproduced or redistributed, directly or indirectly, without prior written permission of GSR.
Please see here for additional Regulatory Legal Notices relevant to US, UK and Singapore.